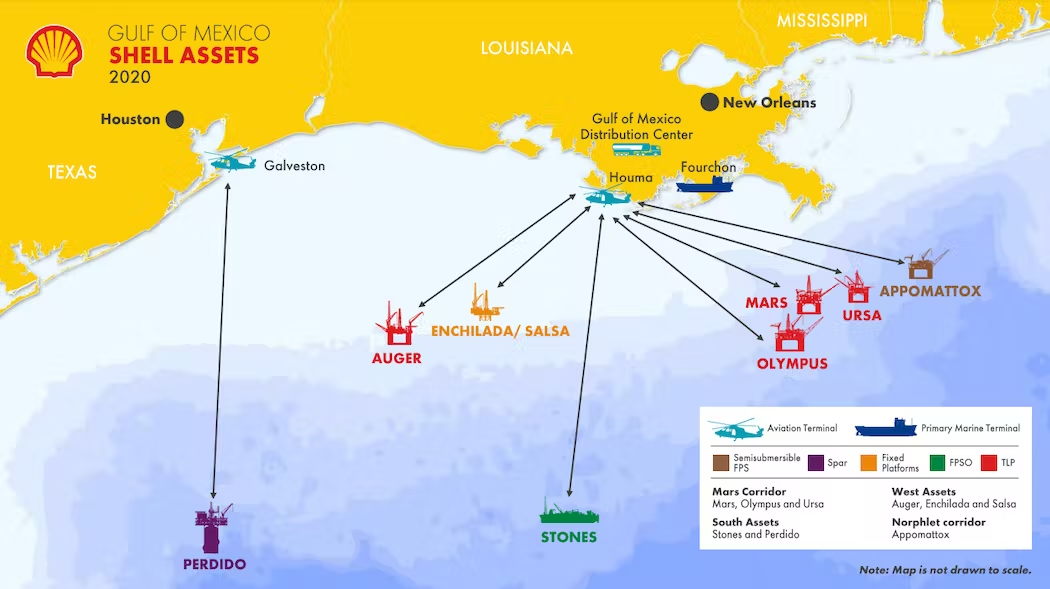
This is a good example of the interconnectivity of deepwater projects with major Shell, Chevron, and Equinor facilities shut-in as a result of a relatively minor downstream pipeline incident.
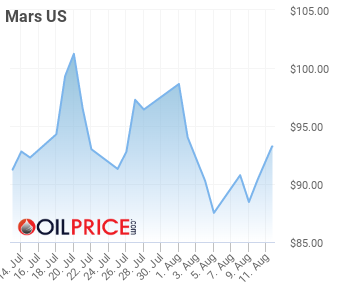
Mars crude price appears to have reacted to the shut-in news:
A small pipeline leak (estimated 2 bbl spill) at an onshore booster station is having a major impact on Gulf of Mexico production. Per Reuters, as much as 600,000 bopd could be temporarily shut-in. GoM production averaged 1.6 million bopd in May.
These major platforms are reported to be shut-in:
Shell: Mars, Ursa, and Olympus
Chevron: Jack/St. Malo, Tahiti, and Big Foot
Equinor: Titan
Shell, the pipeline operator, did not provide an estimate on the resumption of production.
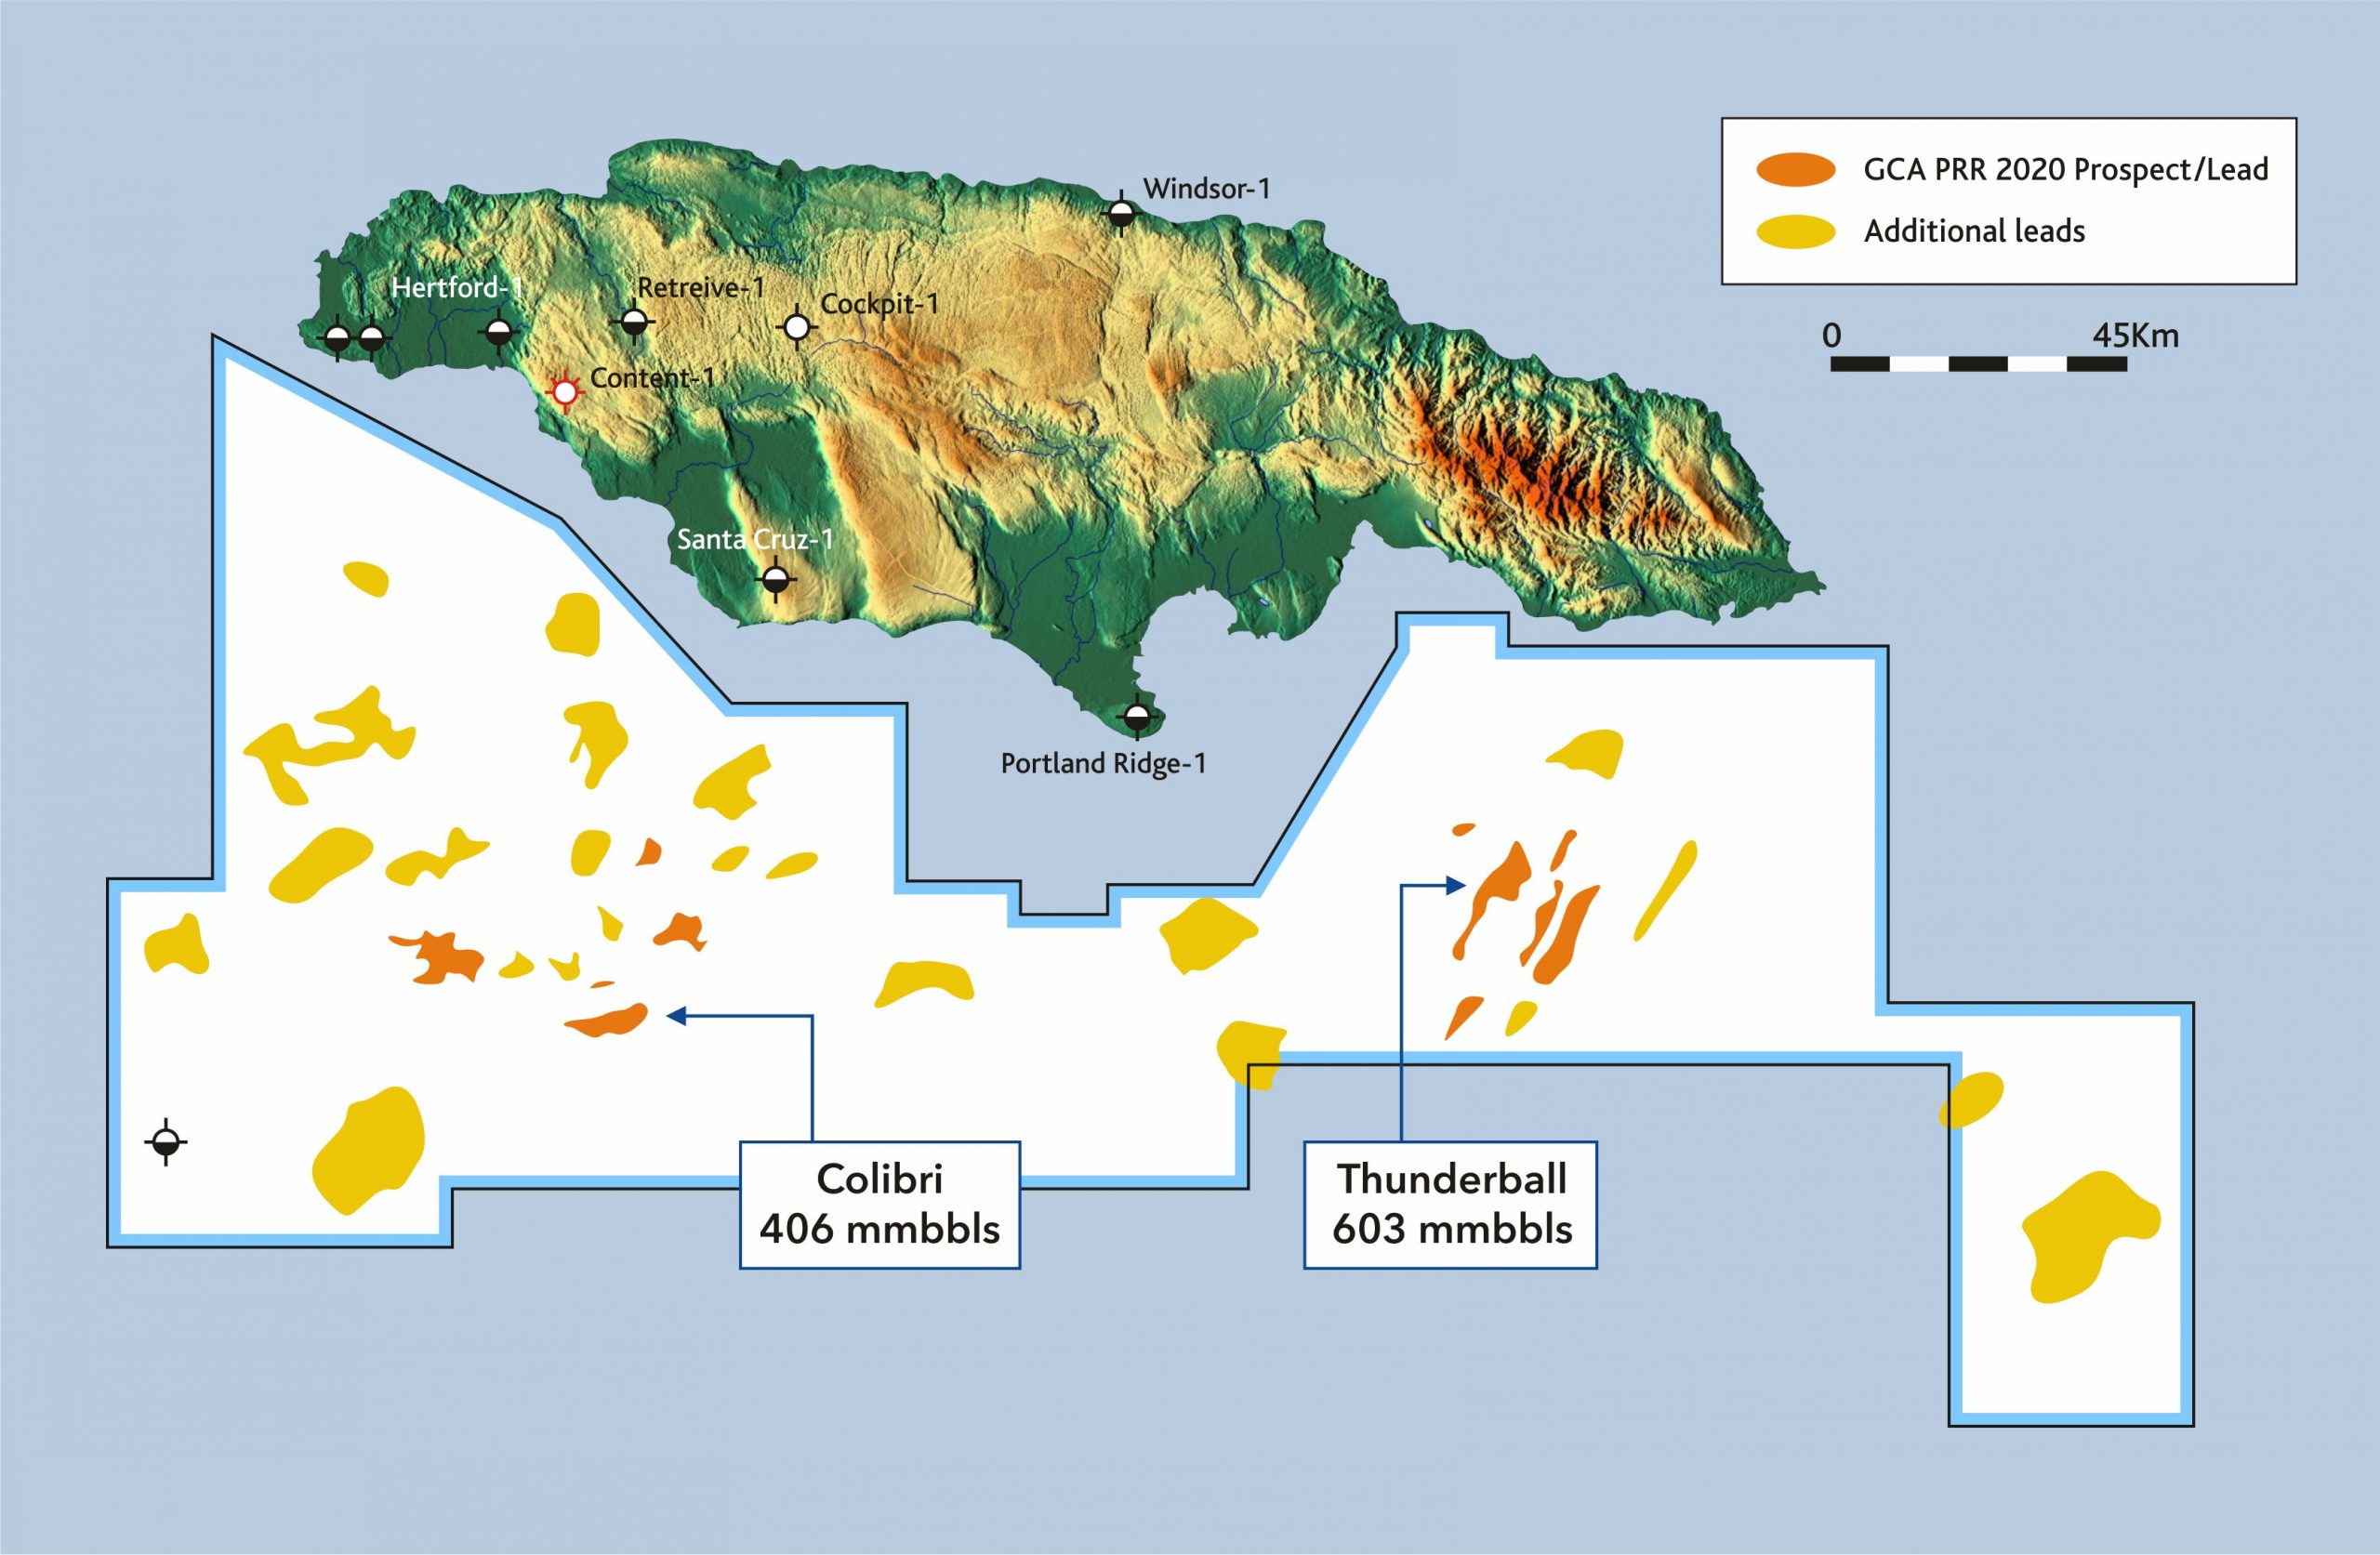
With extensive seismic data coverage, including 2,250 km2 of 3D data, numerous plays and prospects have already been identified and mapped across the area – leading to over 2.4 billion barrels unrisked mean prospective resources being assigned to the licence. The drill-ready, high-impact Colibri prospect alone contains mean prospective resources of 406 mmbbls.
The Colibri prospect is in 750 m of water, and according to this article, would be developed with a tenstion-leg platform if a commercial discovery is made.
The dashed red line outlines China’s claim. Needless to say, Brunei, Indonesia, Malaysia, the Philippines, Taiwan, and Vietnam differ with China’s creative interpretation.
Map Source: CENTER FOR STRATEGIC AND INTERNATIONAL STUDIES, PERMANENT COURT OF ARBITRATION
In recent years, satellite imagery has shown China’s increased efforts to reclaim land in the South China Sea by physically increasing the size of islands or creating new islands altogether. In addition to piling sand onto existing reefs, China has constructed ports, military installations, and airstrips—particularly in the Paracel and Spratly Islands, where it has twenty and seven outposts, respectively.
Never mind that Beijing’s claims are fundamentally incompatible with established international law on maritime boundaries, the United Nations Convention on the Law of the Sea, which China has ratified and by which it professes to abide. Never mind, as well, that the claims have been ruled fraudulent by an international tribunal in The Hague.
Tucked into the end of the nearly $370 billion deal struck last week by Senate Majority Leader Chuck Schumer (D-N.Y.) and Senate Energy and Natural Resources Chair Joe Manchin (D-W.Va.) is a requirement for the Interior Department to reinstate a massive 80 million-acre Gulf of Mexico lease sale that a federal judge blocked earlier this year for violating NEPA.
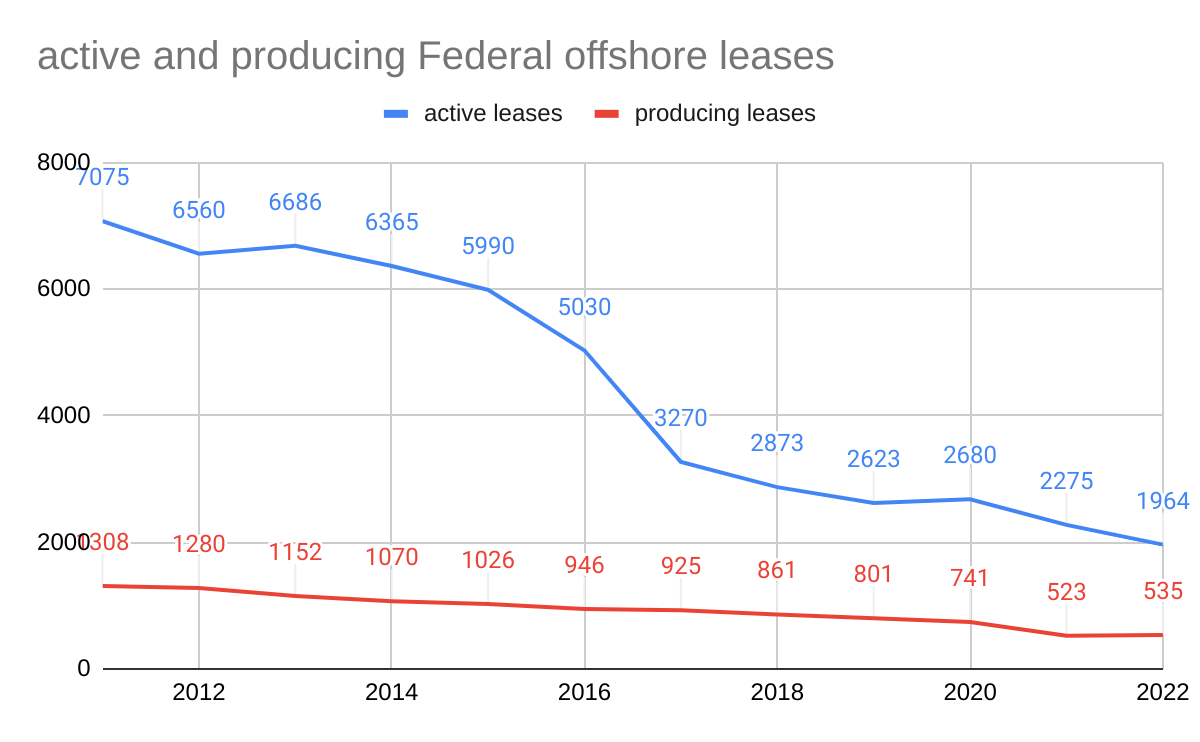
Tracts covering 1.7 million acres received bids at Lease Sale 257. 30.5% of those tracts received bids for CCS purposes, leaving about 1.2 million acres receiving bids for oil and gas exploration. Nonetheless, some continue to distort the magnitude of this rather ordinary lease sale. It’s also important to note that the number of active US offshore leases has declined by 72% since 2011, and is now under 2000 for the first time in decades.
Westwood has highlighted 13 wells planned for the remainder of 2022 as ‘key wells to watch’. These include a number of frontier play tests, for example Raia offshore Mozambique, and Pensacola, offshore UK; extensions of proven plays, including Zanderij offshore Suriname and Hoodoo, US Gulf of Mexico; and large prospects in proven plays, such as Wei, offshore Guyana.
The Hoodoo prospect cited by Westwood is operated by BHP and is in East Breaks Blocks 699 and 700. At Sale 257 (11/17/2021), BHP was the sole bidder on 4 blocks just to the north of this prospect. The lease sale was vacated by a Federal judge in January. If the vacature of Sale 257 is not reversed, either by appeal or legislation, one or both of the following outcomes could easily occur:
BHP loses the opportunity to potentially develop those blocks as part of or in conjunction with the Hoodoo project.
Based on their knowledge of the BHP bids, which are public information, other companies could submit bids for these blocks in a future sale. BHP would have to defensively raise their bids or lose the blocks to another company.
Either outcome would be unfair to BHP and would discourage investment in OCS exploration and development.

 Bud's Offshore Energy (BOE)
