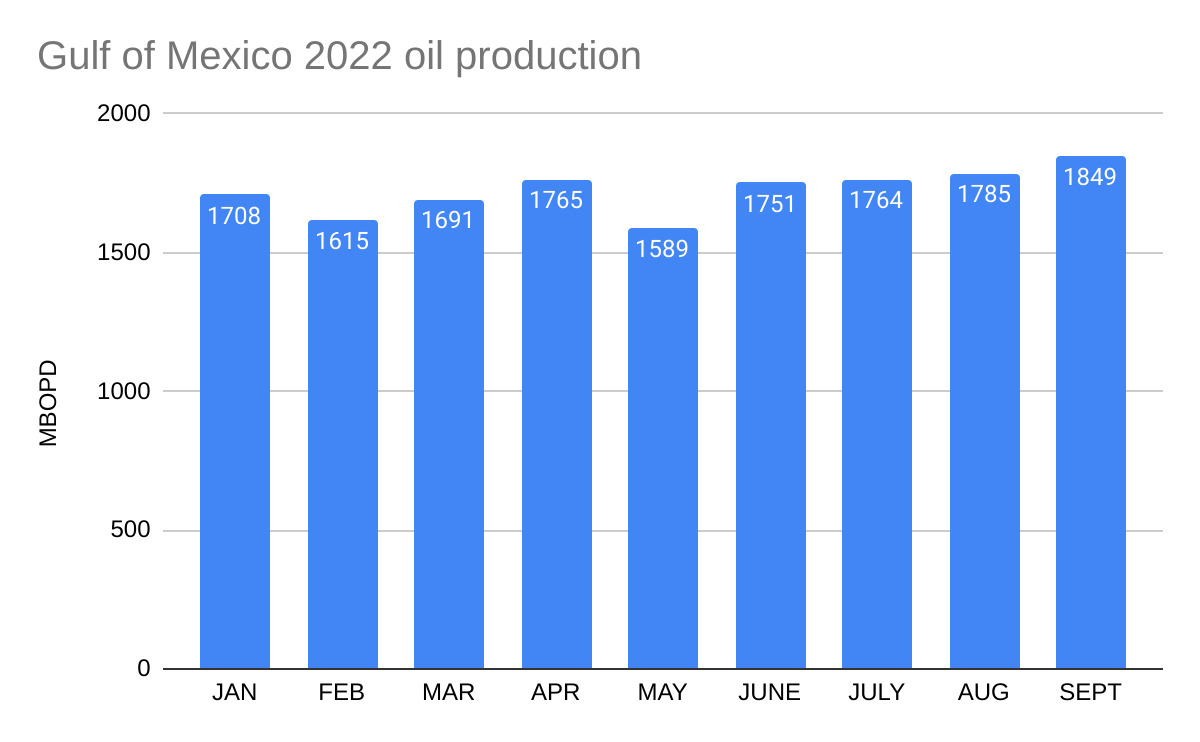
Exxon is now producing >360,000 bopd from just two Guyana FPSOs. So these two FPSOs are producing about 20% as much oil as the Gulf of Mexico or Norway. A third FPSO will add 220,000 bopd in 2023.
Guyana’s oil output is expected to increase significantly in 2023, as both projects maintain steadier production at capacity throughout the year, and as the third project, Payara, comes on stream in the second half of the year. Payara will add another 220,000 bpd of production capacity to Stabroek Block output, taking it to 580,000 bpd.
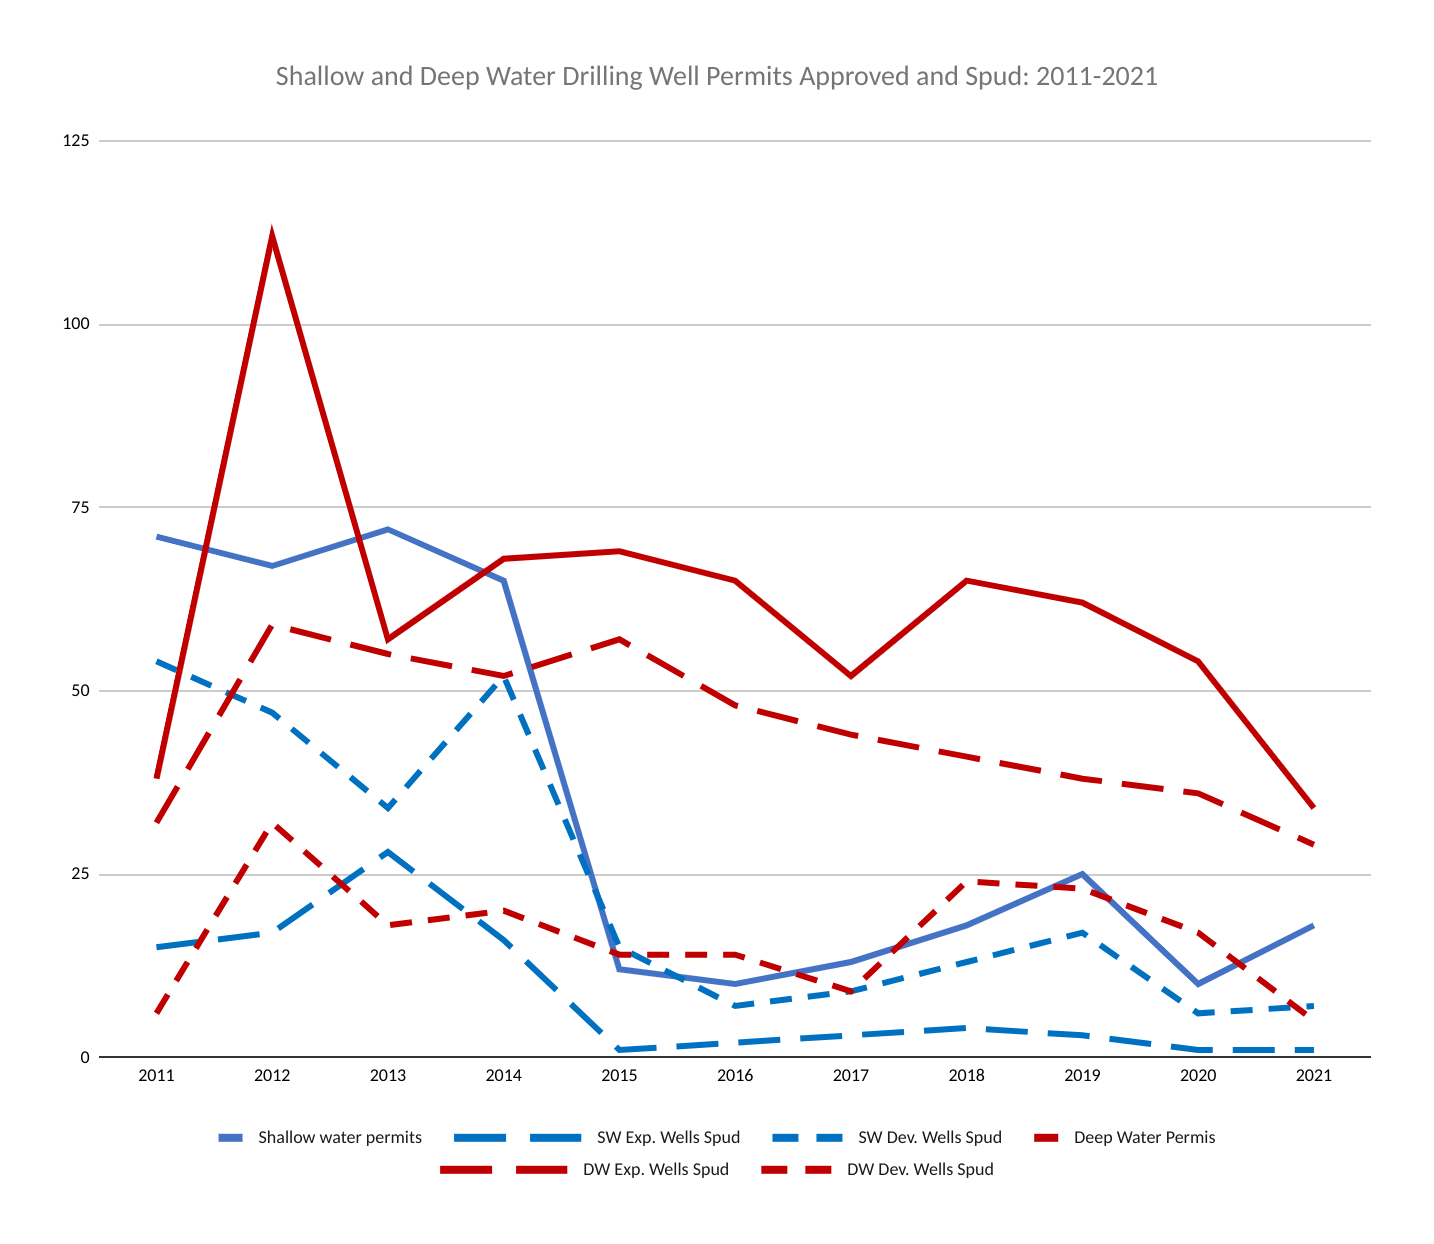
Lars Herbst analyzed GoM permitting and drilling activity from 2011 to 2021. His data and observations are summarized below.
Shelf (shallow water) exploratory drilling is at historic low levels with only a single exploration well drilled in both 2020 and 2021. That trend appears to have continued into 2022, as only one shelf exploration well (drilled by Contango) has been spudded YTD.
2021 also saw a significant drop in deep water development wells.
Over the time period examined, deep water development is led by deepwater exploration. The same cannot be said for the development of shallow water leases where prospects are more mature and data are more available.
The only shelf well drilled in 2021 (Walter Oil and Gas) was in relatively deeper water (566 feet). That well was drilled with a deepwater semisubmersible (the Valaris 8503). This is the shallowest water depth for a GoM semisubmersible drilling operation in recent history. The rig had a modified DP/moored configuration with explosive disconnects on the mooring lines so the rig could move off location if needed during an emergency disconnect scenario. That mooring disconnect would also let the rig evade hurricanes without the need for anchor handling vessels.
The 2012 spike in deepwater permit approvals is the result of the Macondo drilling moratorium backlog.
GOM OCS New Drilling Well Permits and Well Spuds 2011-2021
Year
New Shallow Water Drilling Well Permits Approved
Shallow Water Expl.; New Well Spuds
Shallow Water Dev.; New Well Spuds
New Deep Water Drilling; Well Permits Approved
Deep Water Exp.; New Well Spuds
Deep Water Dev.; New Well Spuds
2011
71
15
54
38
32
6
2012
67
17
47
112
59
32
2013
72
28
34
57
55
18
2014
65
16
52
68
52
20
2015
12
1
15
69
57
14
2016
10
2
7
65
48
14
2017
13
3
9
52
44
9
2018
18
4
13
65
41
24
2019
25
3
17
62
38
23
2020
10
1
6
54
36
17
2021
18
1
7
34
29
5
TOTAL
381
90
261
676
491
182
Note: Only includes new wells not sidetrack or bypass boreholes.
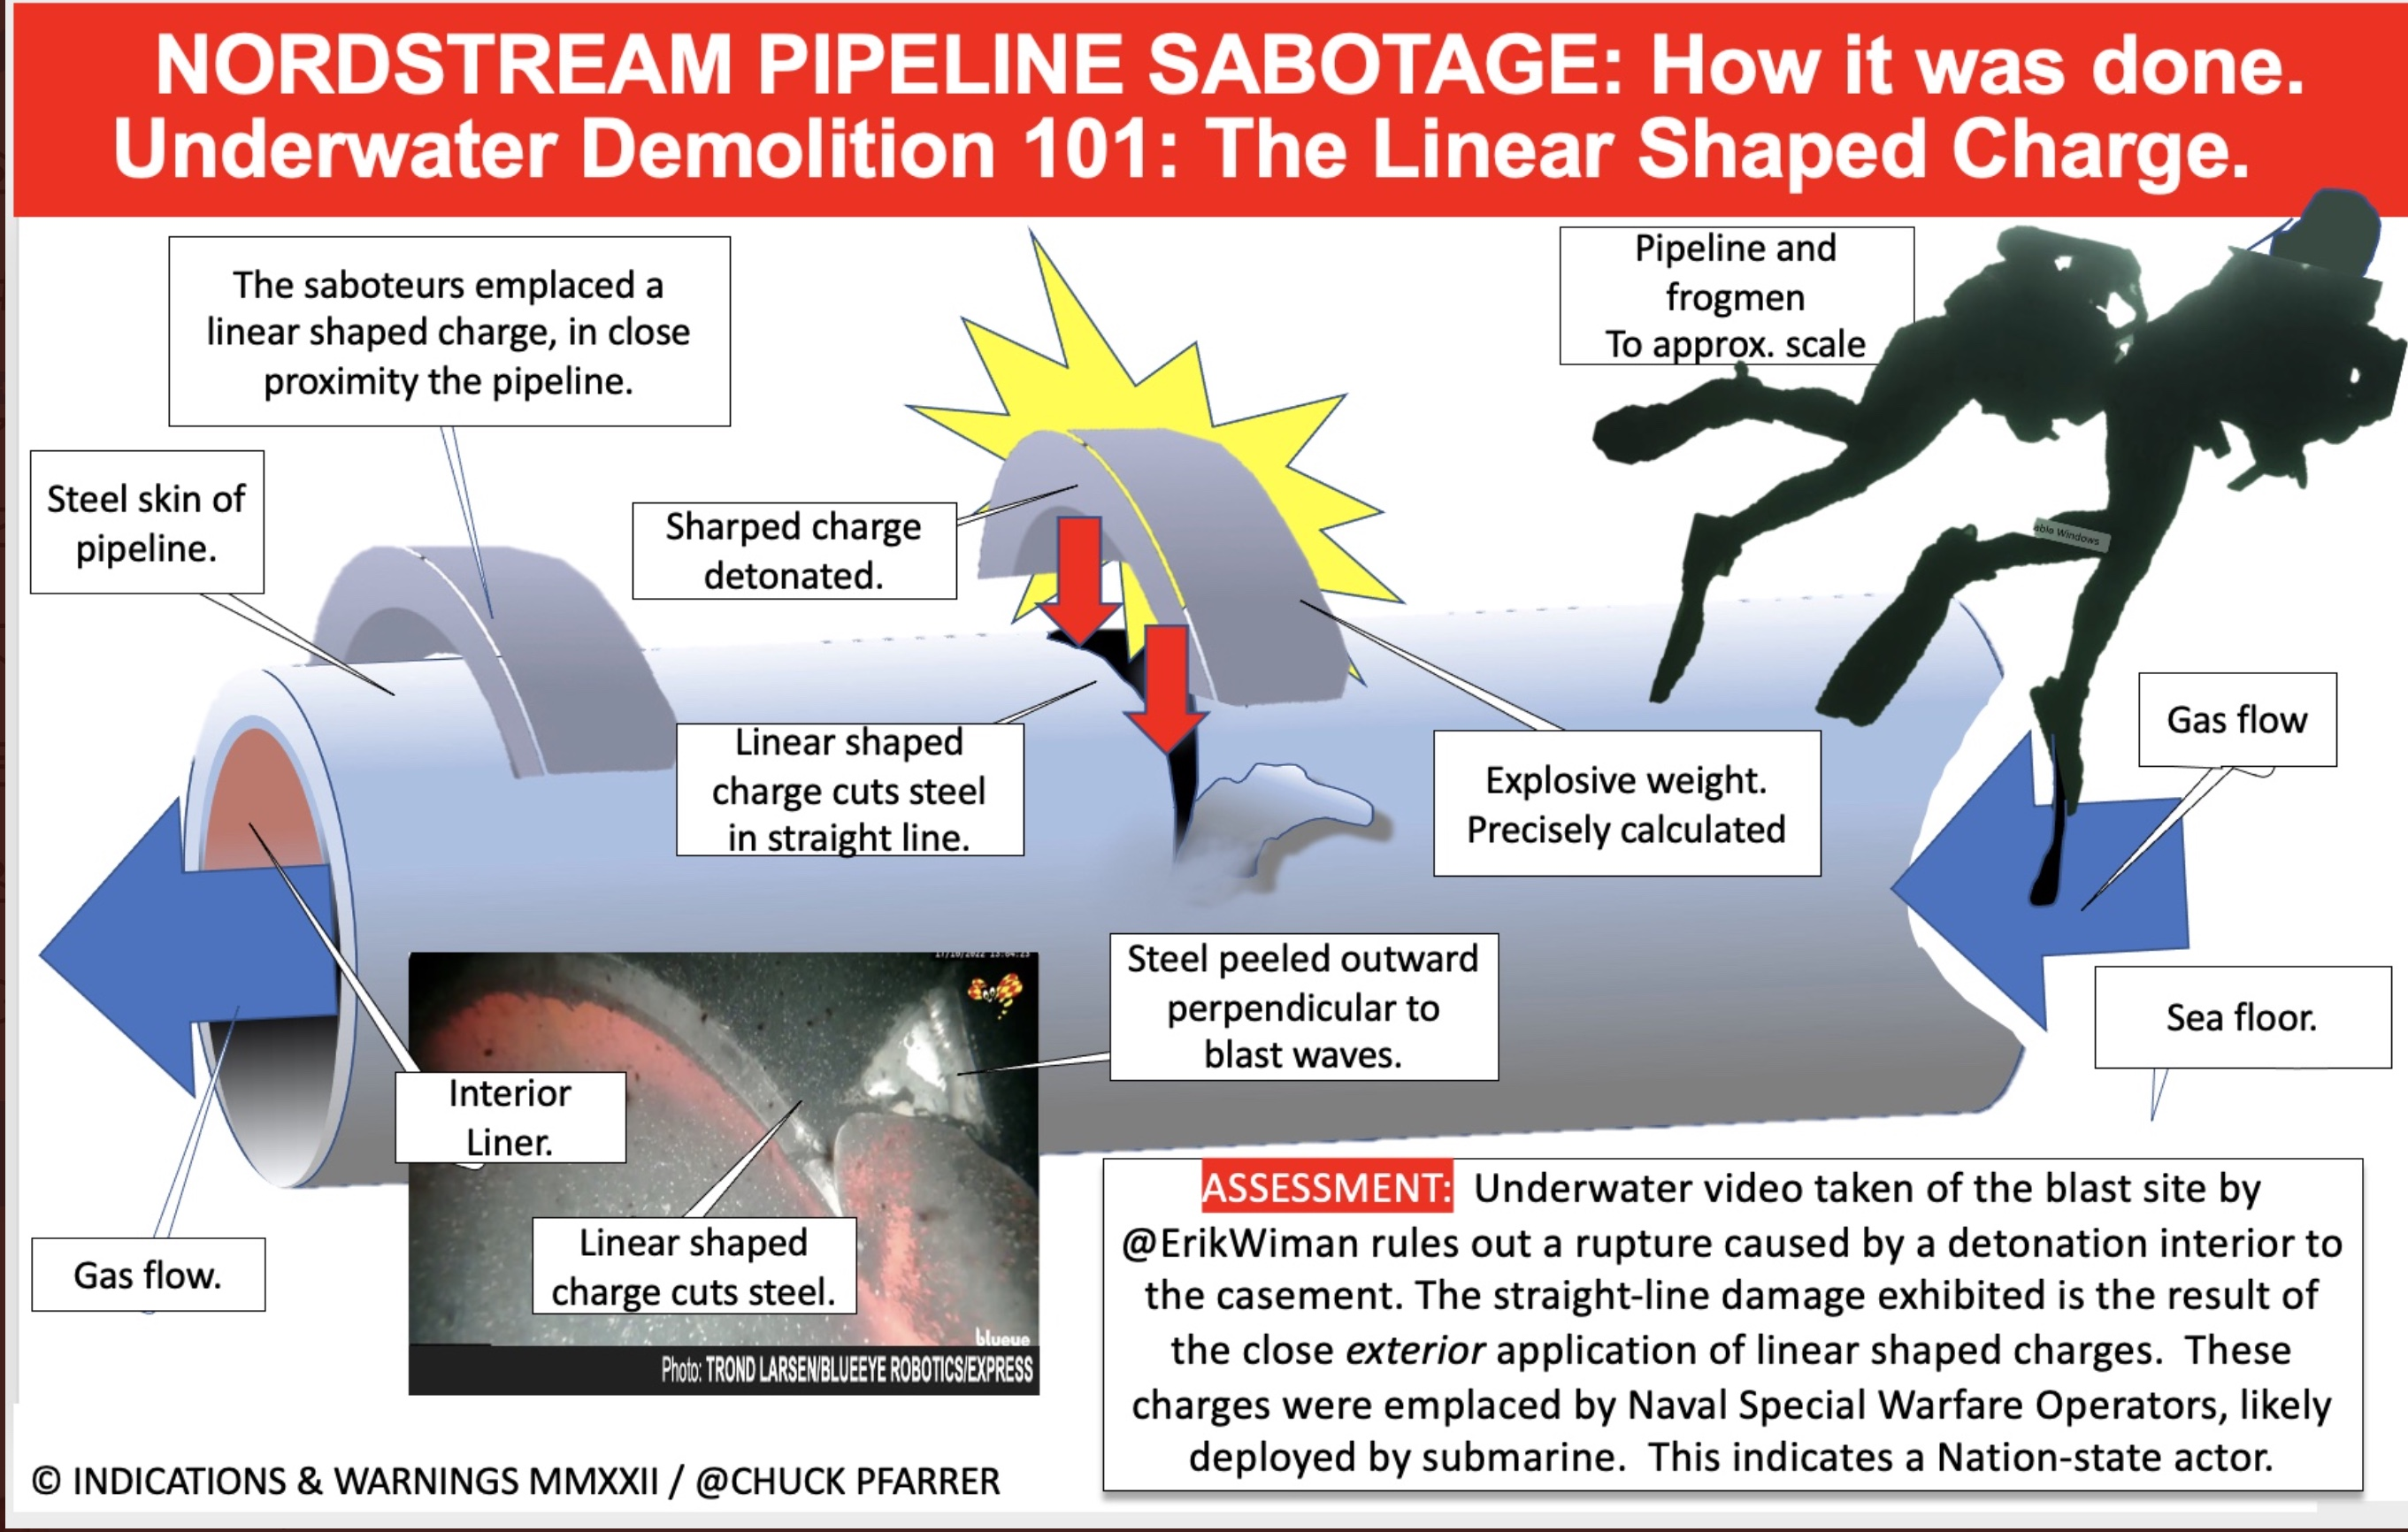
As reported by Tagespiegel, the EU states have agreed to better protect critical infrastructure. Yet apparently the status of the Nord Stream investigation(s) was not discussed. When will the findings be released? How and when will the responsible parties be identified?
Despite the spectacular 2022 lease sales, not all is rosy for US offshore wind development.
In 2011, then-Interior Secretary Ken Salazar said the Obama administration had set a goal of “10 gigawatts of offshore wind generating capacity by 2020 and 54 gigawatts by 2030.” How has that worked? Well, 11 years after Salazar’s speech, the US has seven turbines operating offshore with a total of capacity of 42 megawatts — or some 9,958 megawatts short of the goal laid out by Salazar.
Gordon Hughes, a professor of economics at the University of Edinburgh, has found that the output of Europe’s offshore wind turbines has been declining by about 4.5% per year. In a report titled “Wind Power Economics: Rhetoric and Reality,” published by the London-based Renewable Energy Foundation in 2020, Hughes concluded that declining output will result in higher operating costs that will start to exceed revenues “after 12 or 15 years.
…addressing climate change through ocean “industrialization” using an “inefficient, expensive and largely untested strategy” was not the right path forward – Kari Martin, Clean Ocean Action
“By undertaking an industrialization project this big, it far outweighs any (climate change) benefit anybody’s ever talked about, or even tried to quantify,” he said. “The harms of this undertaking is, in my view, far worse than any benefits we could realize.” – Michael Dean, Middletown, NJ
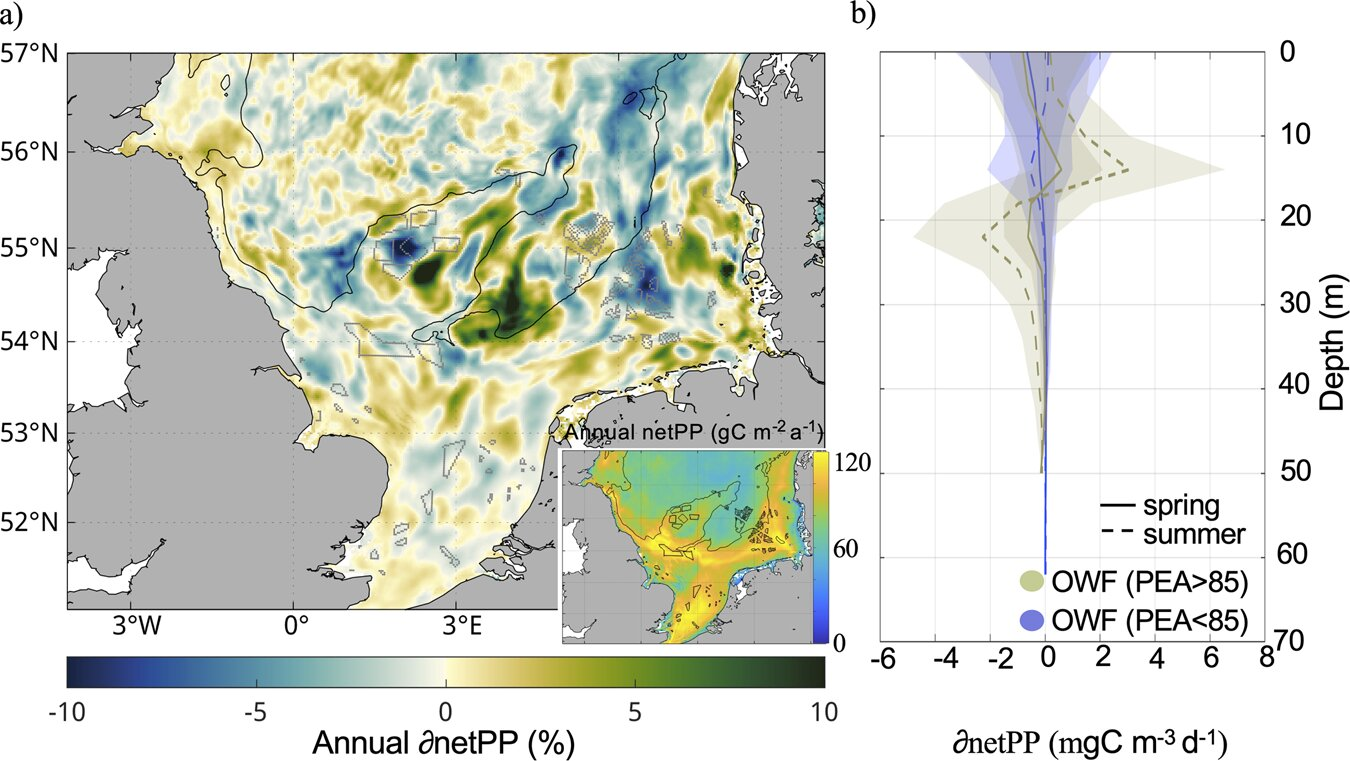
In their latest publication, (scientists at the Helmholtz-Zentrum Hereon) now show that large-scale wind farms can strongly influence marine primary production as well as the oxygen levels in and beyond the wind farm areas. Their results were published in the journal Communications Earth & Environment.
… For example, Nils Christiansen’s team proved that wake turbulences—air vortices caused by wind turbines—change the flow and stratification of the water beneath them. But the climate just above the sea surface is also being permanently changed, as another team led by Dr. Naveed Akhtar was able to show.
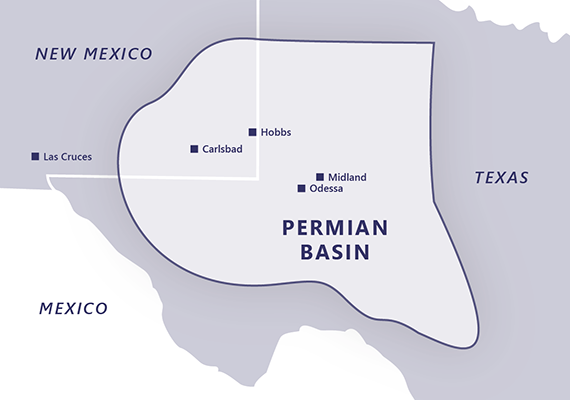
Like its salty neighbor to the east, the Permian Basin of west Texas and southeastern New Mexico has been proclaimed dead on many occasions. Such proclamations of their demise, however, are mere exaggerations as the Gulf of Mexico and the Permian Basin continue to thrive.
These historic oil and gas production powerhouses have delivered to global markets billions of barrels of oil and trillions of cubic feet of natural gas over the past century. Through the booms and the busts, the resiliency of each was made possible by the combination of ingenuity and perseverance and by advancements in techniques and technologies.
Thirty years ago the Gulf of Mexico was called “the Dead Sea” because of the decline in drilling and production activity. Deepwater technology reversed that trend and led to record Gulf of Mexico oil production averaging 1.9 million BOPD in 2019.
Similarly, horizontal drilling and hydraulic fracturing technology launched the shale revolution, and Permian oil production has risen impressively to 5.4 million BOPD.
Both the Permian and the GoM have the potential to sustain or increase production. The Permian Basin, much of which is privately owned, is more adaptable to market conditions and less exposed to political risks. The offshore program is dependent on effective long-term planning and supportive lease management policies. Unfortunately, the proposed 5 year leasing plan suggests a commitment to throttling offshore production rather than sustaining it. When will our energy policy pendulum swing back to a more balanced position?
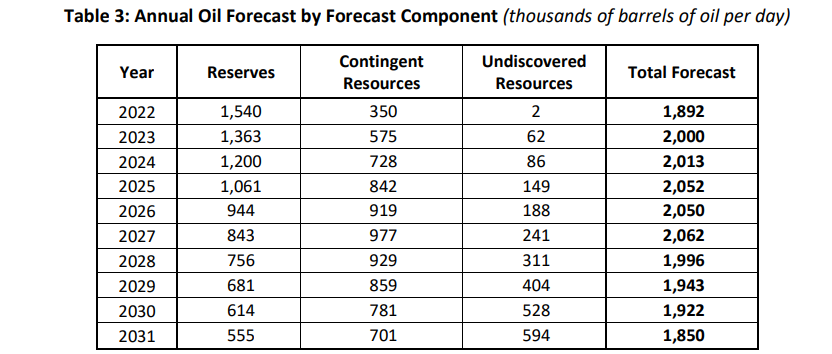
“BOEM’s short-term (20-year) production forecast for existing leases shows steady growth from 2022 through 2024 and declining thereafter (see Section 5.2.1). The long-term nature of OCS oil and gas development, such that production on a lease can continue for decades makes consideration of future climate pathways relevant to the Secretary’s determinations with respect to how the OCS leasing program best meets the Nation’s energy needs.“
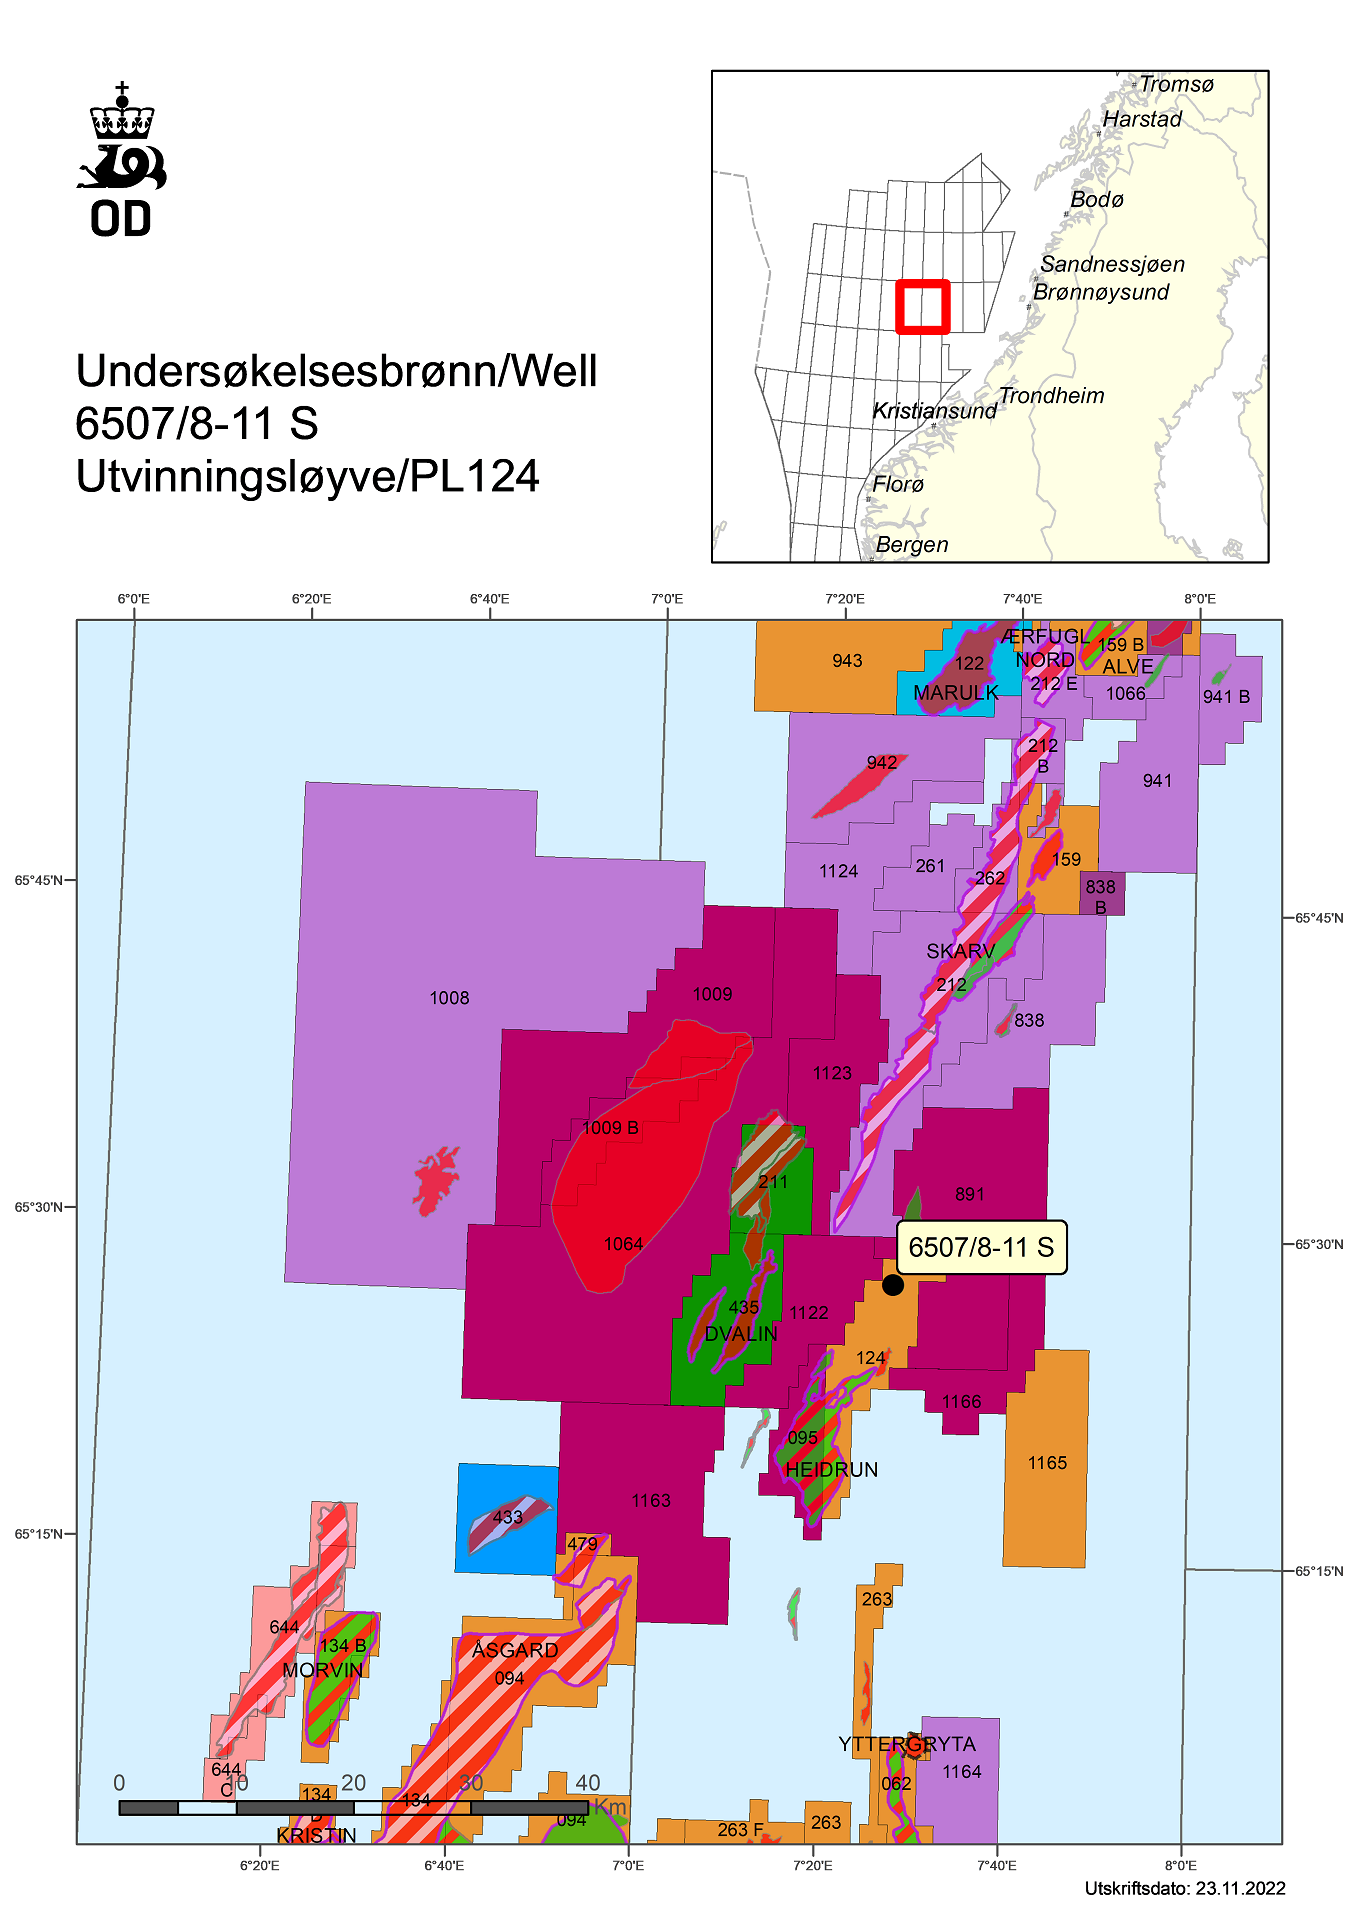
OSLO, Nov 29 (Reuters) – Norway will not issue licences for energy companies to explore for oil and gas in frontier areas during the life of the current parliament, which ends in 2025, its oil and energy minister told Reuters on Tuesday.
“SV (Socialist Left Party) has had this as a demand for this year and we went along with that. And have accepted that this can be held off for this parliamentary period,” (per Minister of Petroleum and Energy Minister Terje Aasland).
Aasland said there was “no drama” in the decision as authorities still issue licences to oil companies in a parallel licensing around called the APA round, in so-called mature areas that are already open to oil companies.
The comment (pasted below) by the trade associations asserts that BSEE ignored the requirements of the National Technology Transfer and Advancement Act (NTTAA).
Reaction:
BSEE and its predecessors (MMS and the Conservation Div. of USGS) have been incorporating industry standards since 1969, 27 years prior to the enactment of the NTTAA (1996).
The keystone of the BOP regulations, API Standard 53, is cited in 250.730, the very section of the rule that is under discussion. Seven other industry standards are cited in that section of the rule. Does this imply ignoring the NTTAA?
Regulators cannot cede their authority to standards development organizations. If a standard is outdated or deficient, the regulator must address the issues of concern.
Deviations between provisions in the regulations and API Standard 53 are expected and specifically provided for in 250.730 as follows: “If there is a conflict between API Standard 53 and the requirements of this subpart, you must follow the requirements of this subpart.“
For years, the production safety system regulations specified different leakage rates for surface and subsurface safety valves than those allowed in the API standards. An MMS research project addressed and helped resolve these differences.
While essential to safety and regulatory programs, standards are not a panacea; nor is the standards development process without weaknesses. One need only consider the case of the delayed cementing (zonal isolation) standard to appreciate both the importance of standards and the potential weaknesses in the development process.

 Bud's Offshore Energy (BOE)

This Well Control Rule comment, endorsed by 7 trade associations, hit a nerve. Here’s why.
Posted in drilling, Offshore Energy - General, Regulation, well control incidents, tagged BSEE, NTTAA, standards, standards vs. regulations, trade association comments, Well Control Rule on November 30, 2022| Leave a Comment »
The comment (pasted below) by the trade associations asserts that BSEE ignored the requirements of the National Technology Transfer and Advancement Act (NTTAA).
Reaction:
Read Full Post »