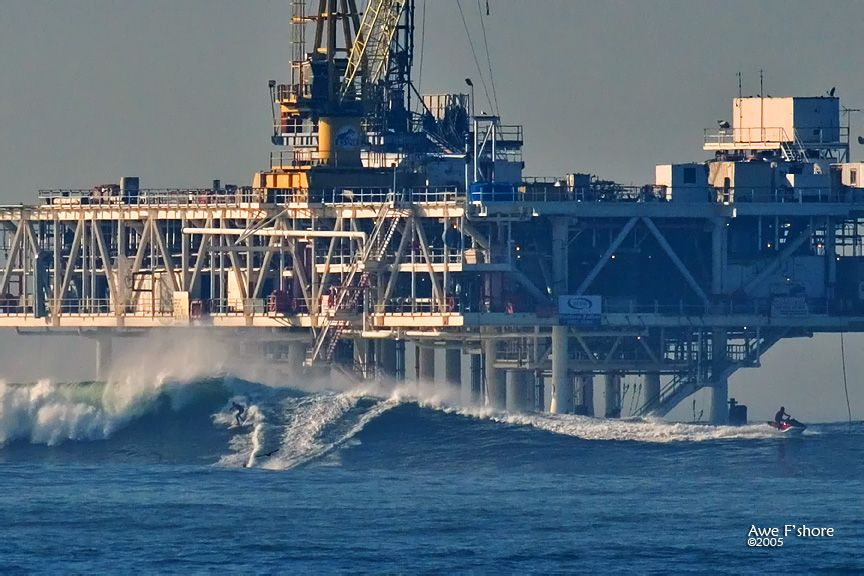
Eloquent eulogy by DCOR (platform operator) CEO Alan Templeton: “Last Sunday, August 10, I joined a small group of DCOR personnel on Platform Esther to witness her final moments of operation. At exactly 3:00 p.m., we pressed the ESD on the production deck, and one by one, the sounds of compressors and pumps faded until the platform fell silent — a profound and bittersweet moment in California’s energy history.
For over half a century, Esther stood off the coast of Orange County, first installed in the early 1960s as one of California’s iconic man-made oil islands. She blended into the horizon while quietly producing oil and gas, surviving storms, and later being rebuilt in 1985 into the platform we know today. More than just steel and pilings, Esther was a proving ground for innovation, a dependable asset, and a source of pride for the men and women who worked safely on her decks.
While she has now been permanently shut in, her legacy remains — a testament to the ingenuity, resilience, and dedication that have defined California’s offshore industry for generations.“
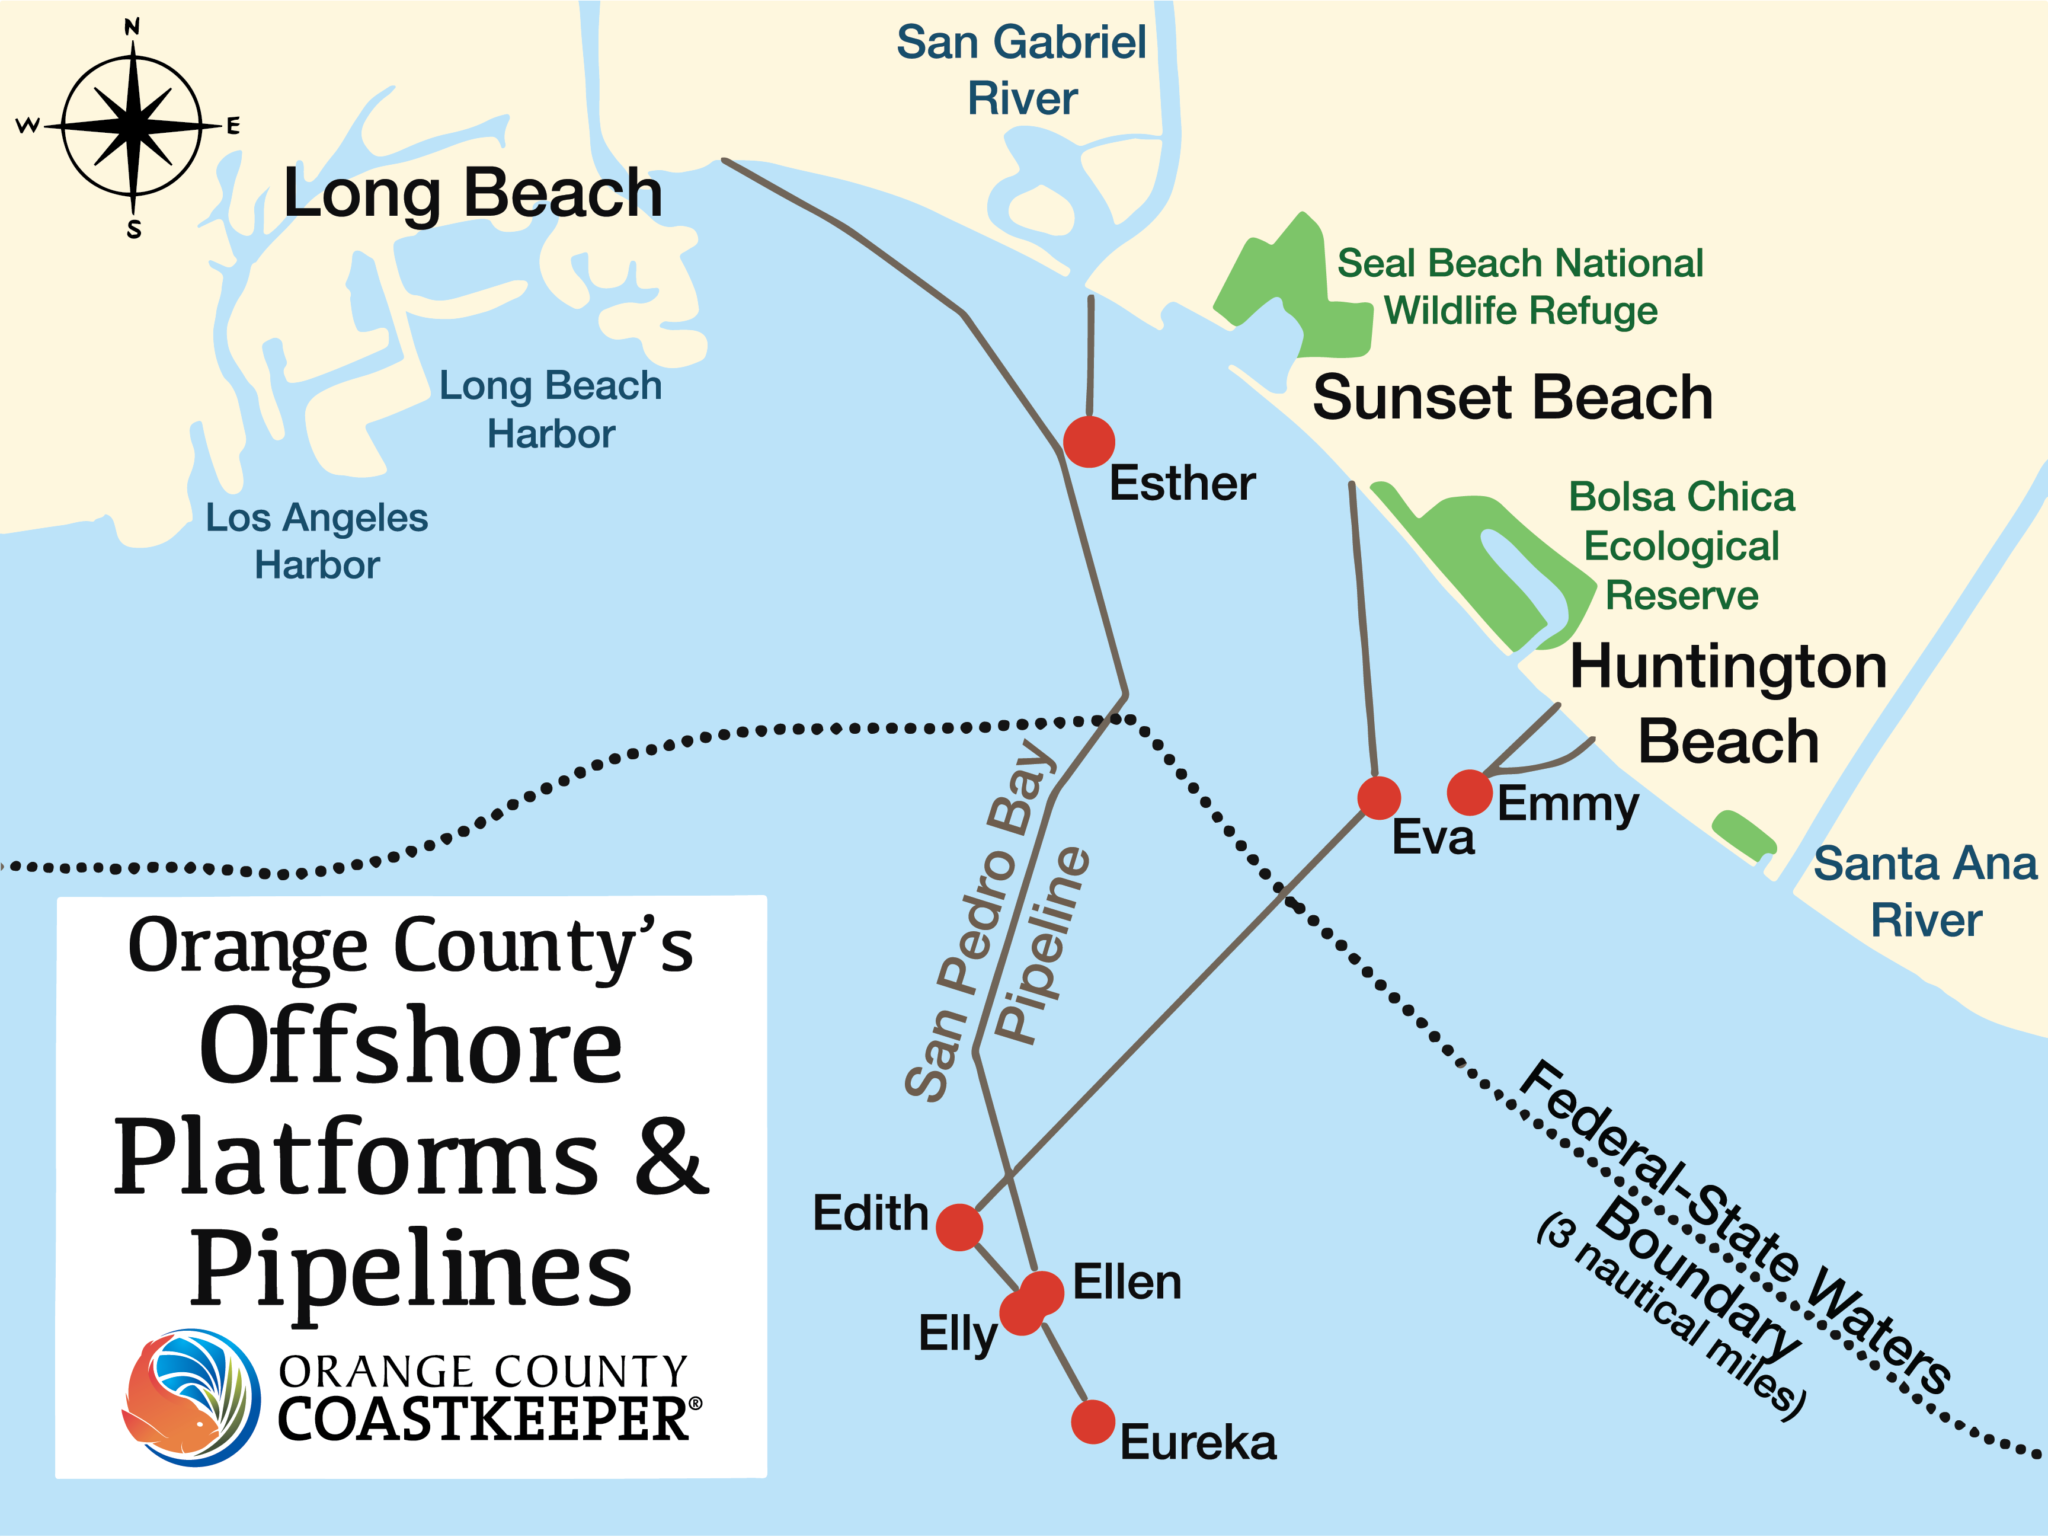
Litigation prematurely ended production at Esther, which would have had an estimated 15 more years of operative life. The attached settlement agreement, shared by John Smith, ends a dispute between the State Lands Commission and DCOR over repurposing a pipeline to transport oil from state Platform Eva to Federal Platform Edith (diagram above).
In exchange for relinquishing its mineral rights and decommissioning Platform Esther, the settlement grants DCOR a $10 million royalty credit on future oil produced from Platform Eva. This credit is significantly less than the value of remaining production from Esther.
Platform Esther, is one of three remaining oil production platforms in California state waters.
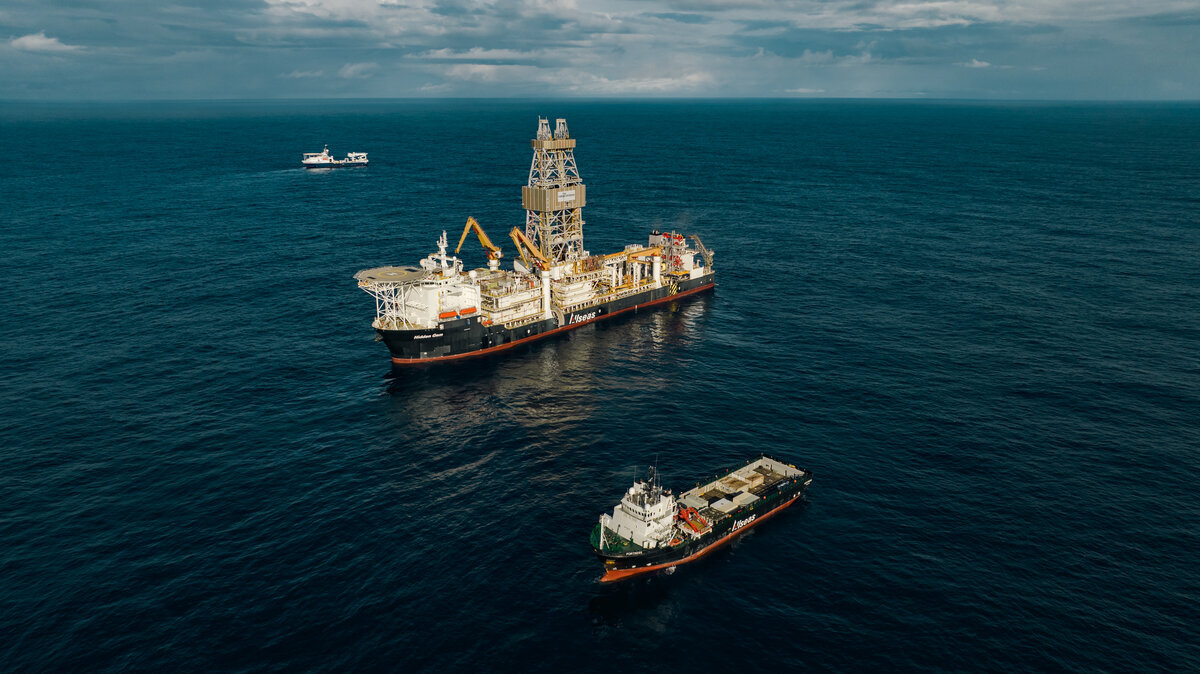
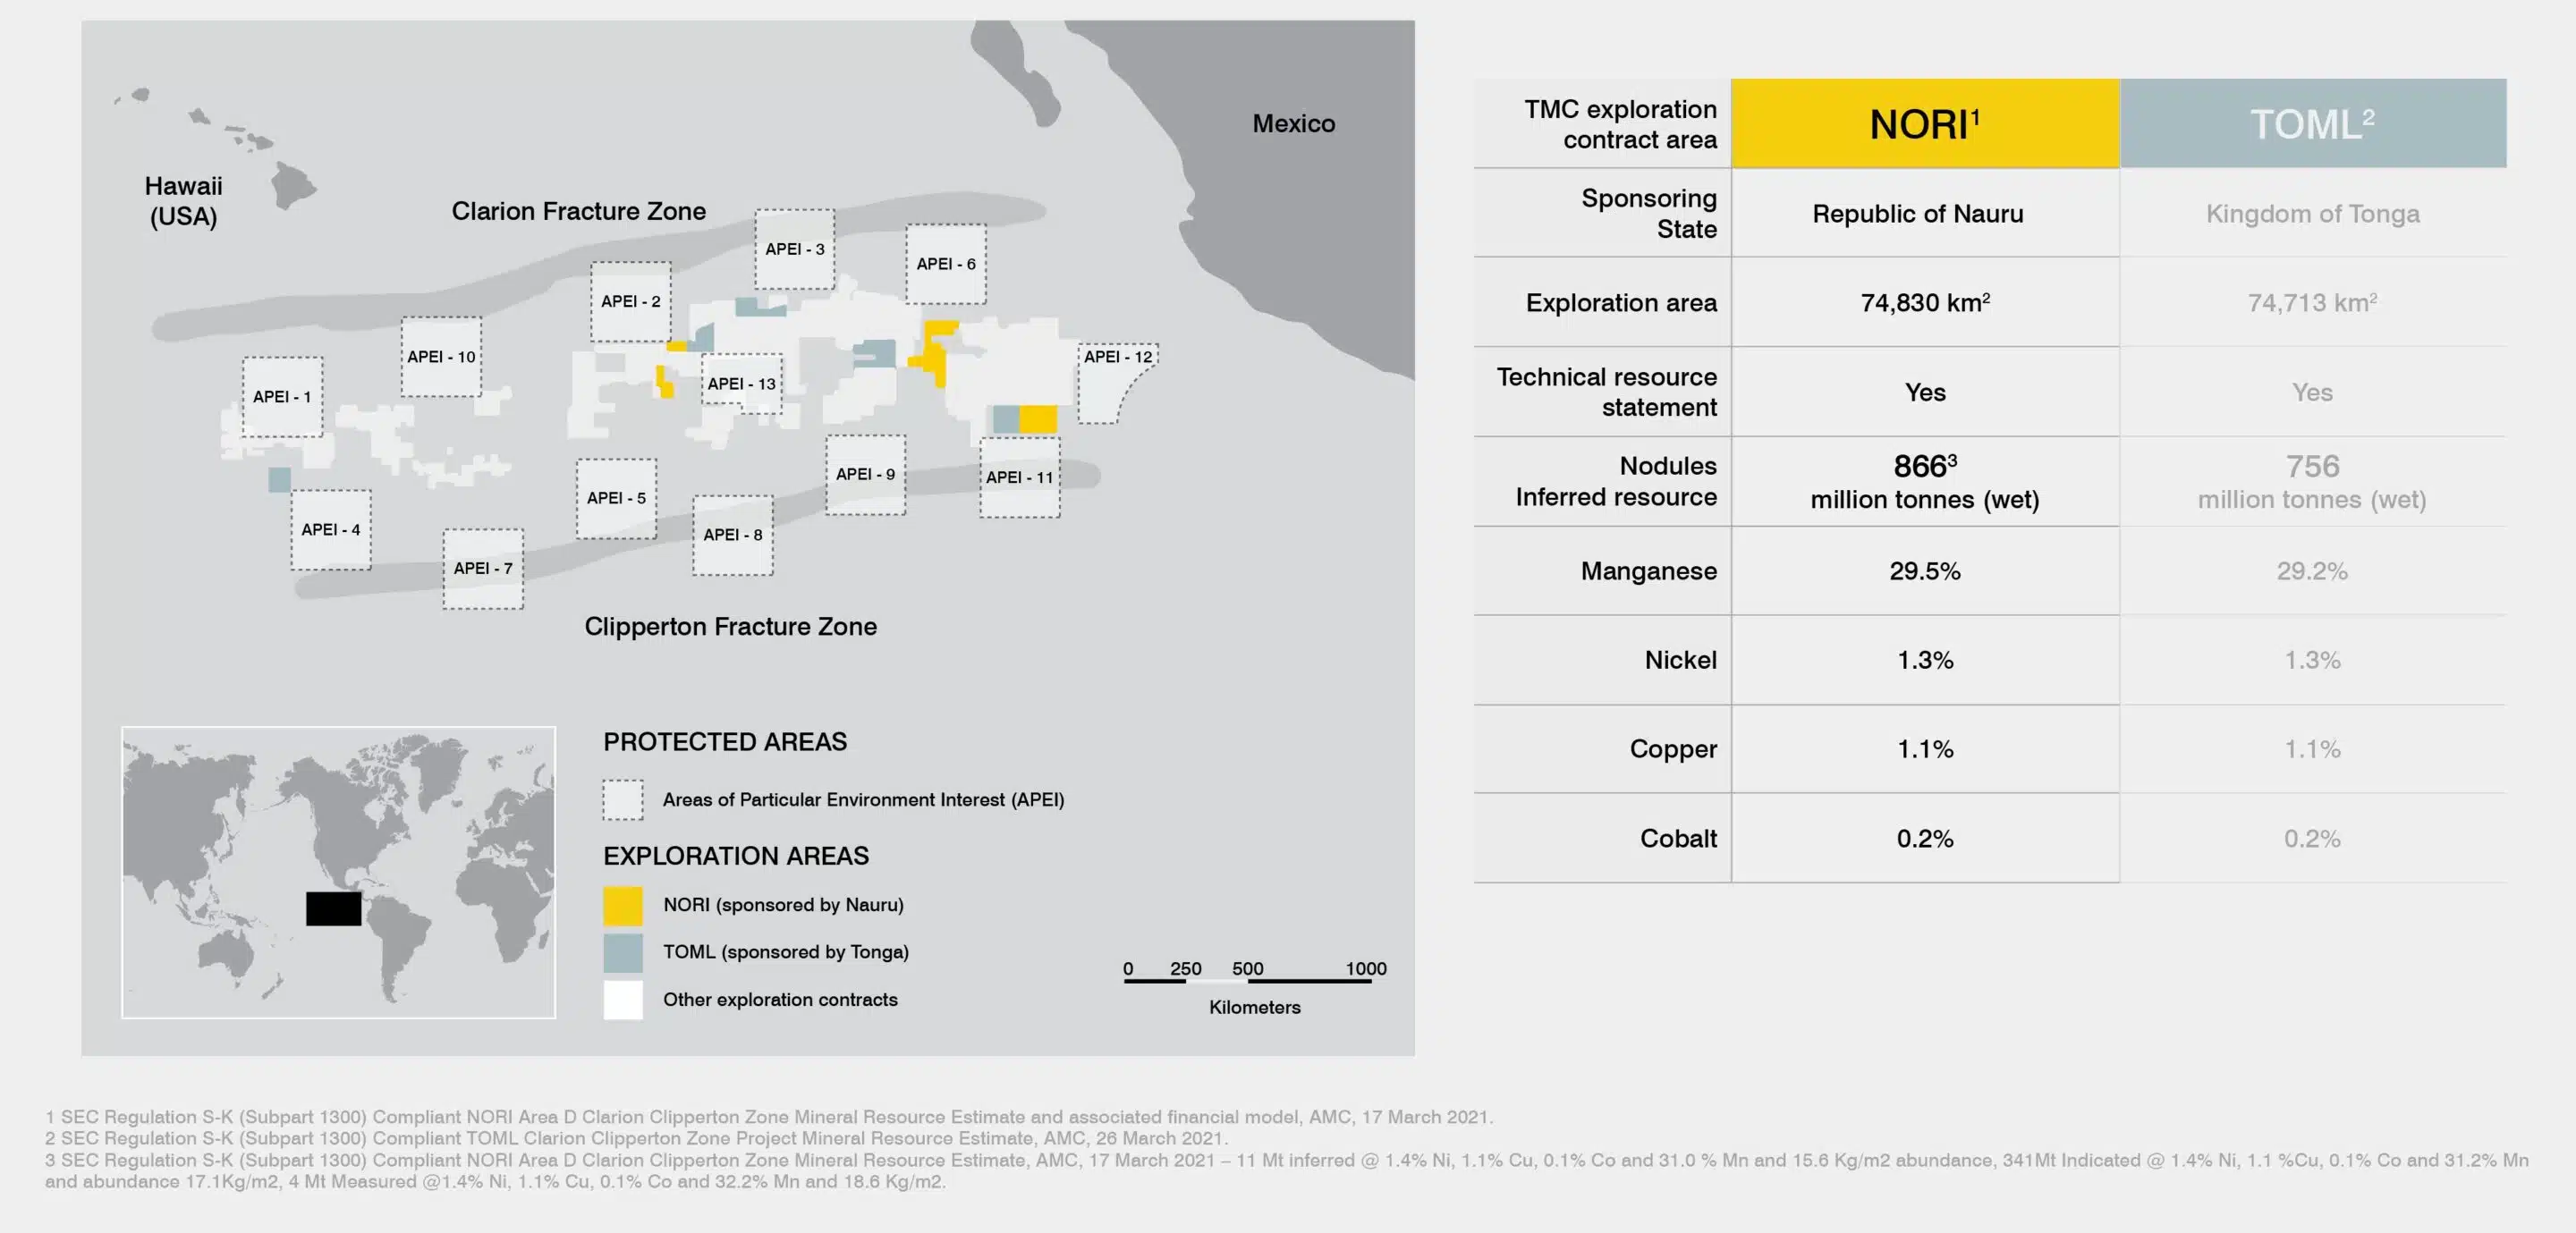
On August 11, 2025, TMC USA received notice of full compliance from the National Oceanic and Atmospheric Administration (NOAA) on its exploration applications, and reconfirmation that TMC USA has priority right over both exploration areas
Both applications entered the certification stage in late July, which we expect to be approximately 100 days
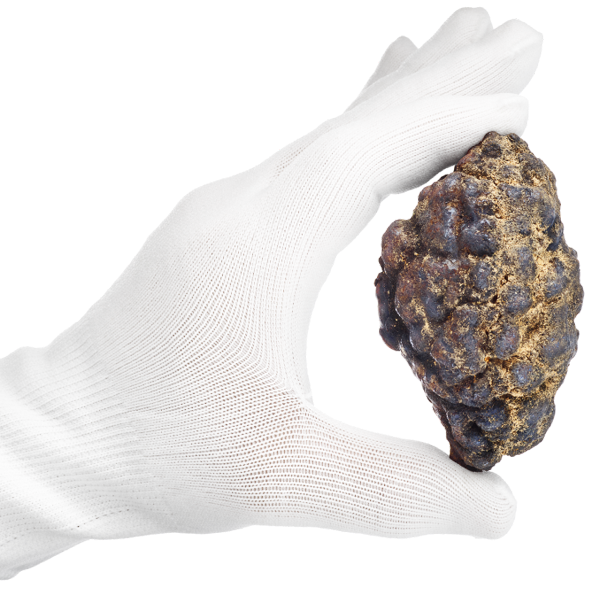
In light of recent U.S. regulatory developments, TMC expects to commence commercial production from the NORI-D Area in the fourth quarter of 2027 if we receive a commercial permit before scaling to an average annual production rate of 10.8 million tonnes of wet nodules per annum (Mtpa) at steady state (2031 through 2043) production, with an expected 18-year life of mine (LOM);
Meanwhile, after missing deadlines in 2020 and 2023, the International Seabed Authority (ISA) again failed to deliver a Mining Code as communicated in their 2023 roadmap during the second part of their 30th session in July 2025. No new roadmap or new target date for adopting the final Mining Code has been agreed. The next ISA meeting is scheduled for March 2026. (Hence the importance of direct permitting through the US/NOAA.)
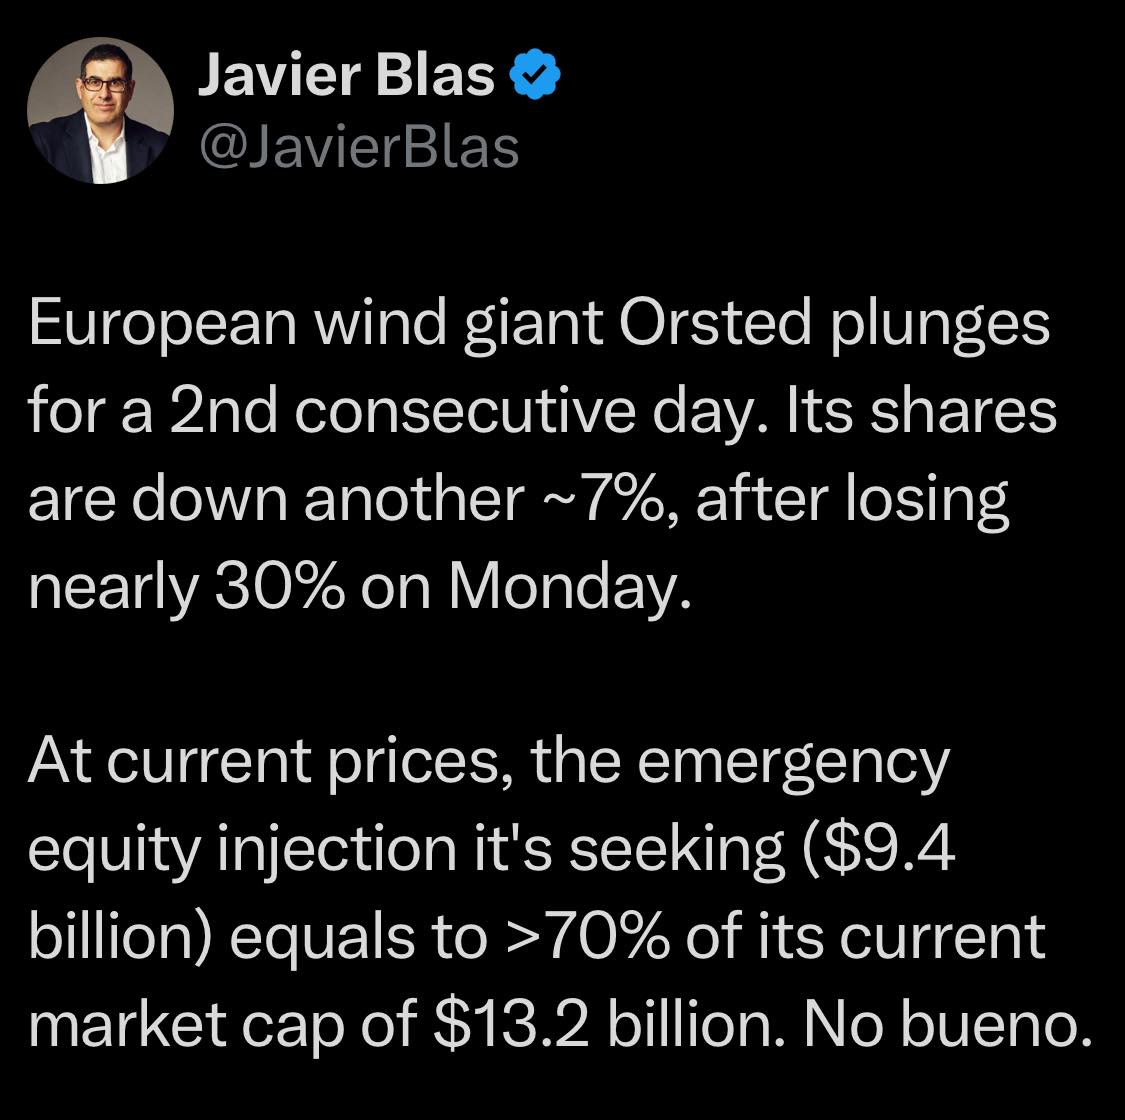
Following the announced $9 billion rights offering to shore up its finances, Orsted’s long-term issuer credit rating has been downgraded to BBB- by S&P, just one step above junk.
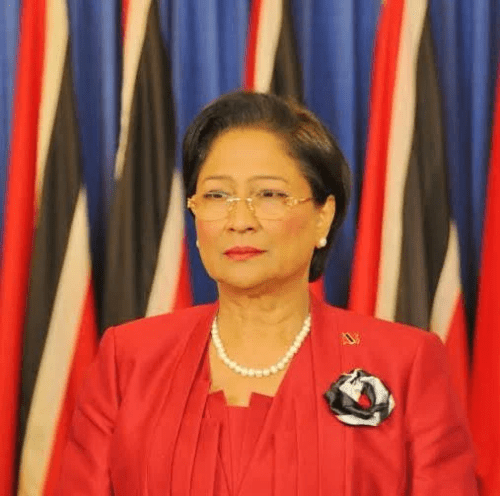
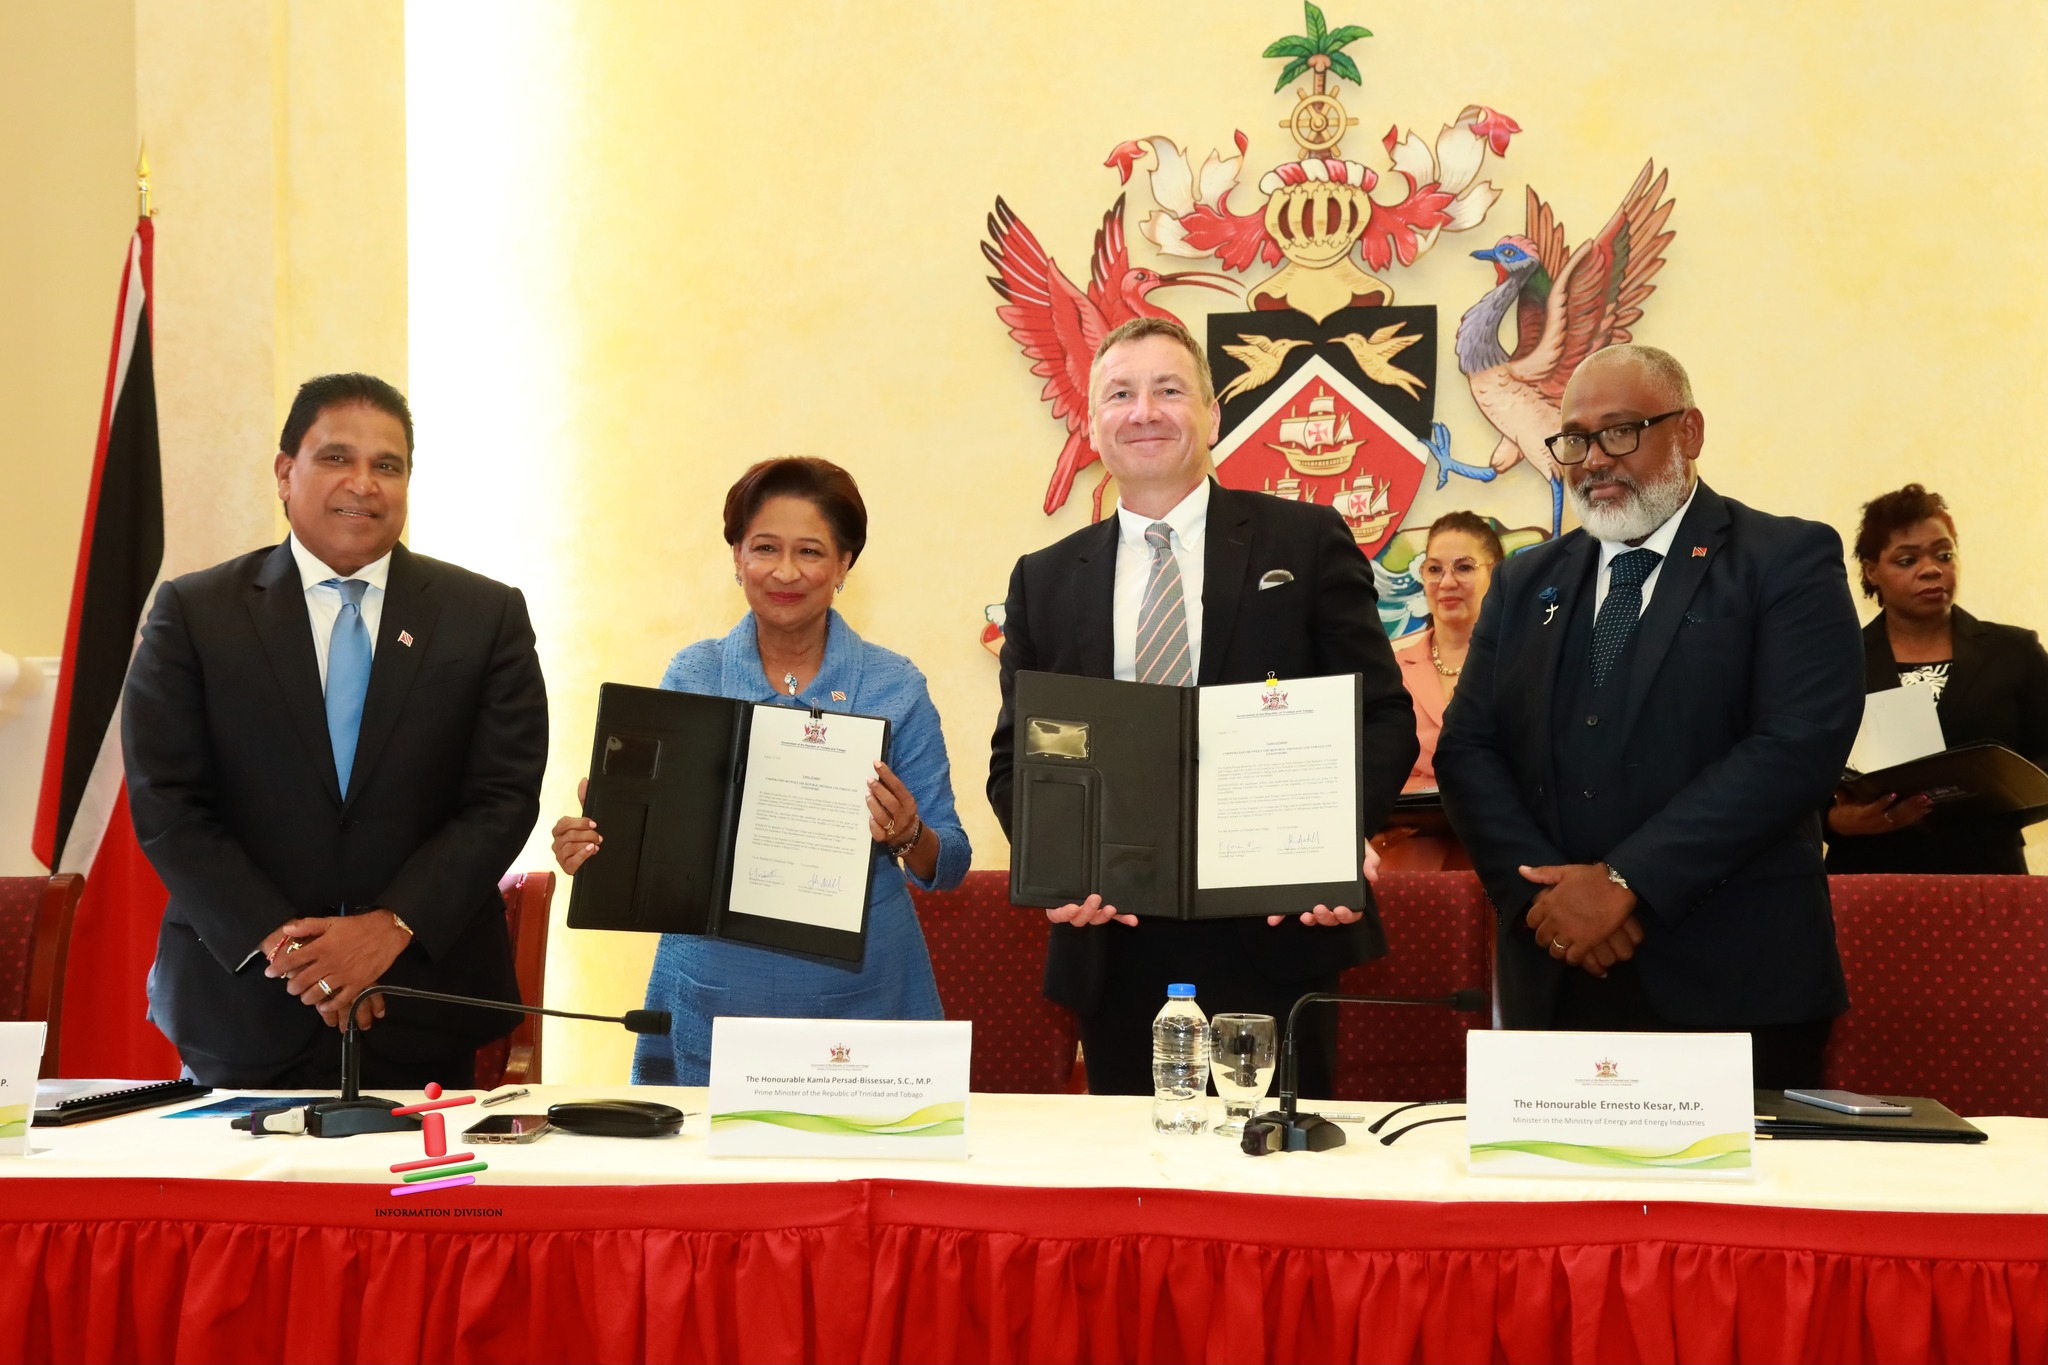
Trinidad’s Prime Minister Kamla Persad Bissesar: “Trinidad will not wait for the end of any energy era,” she said. “Our principle is simple: investment goes where it is welcomed and stays where it is well treated.”
The PM of a country with an oil production history that predates the Drake well in Pennsylvania leaves no doubt about her support for deepwater development. Her candid and clear messaging is most refreshing.
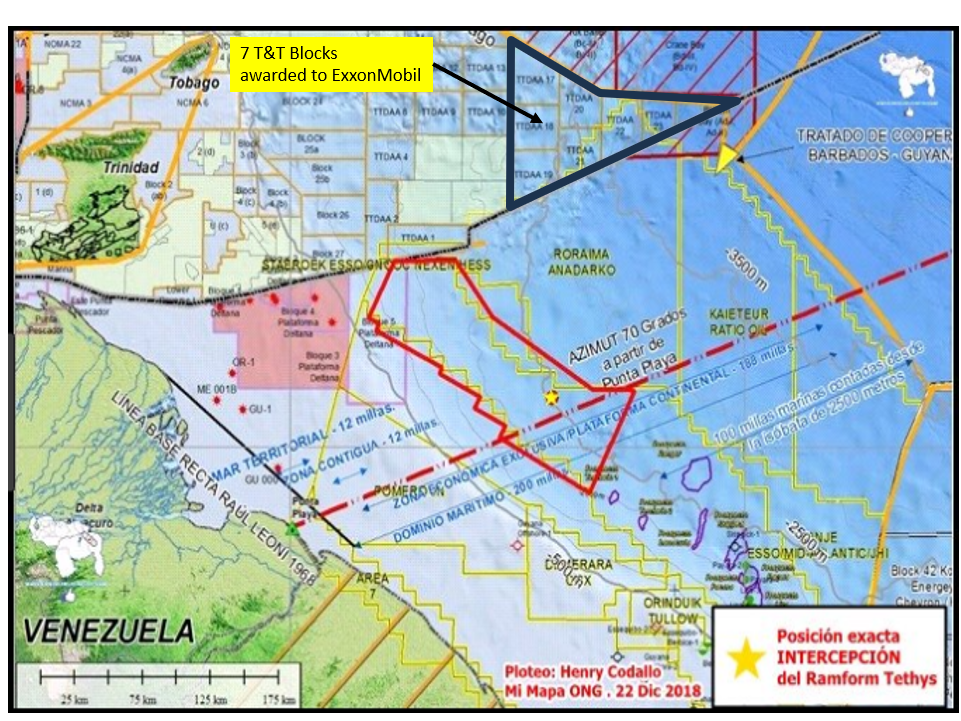
Consistent with her policy guidance, T&T signed a Production Sharing Contract with Exxon for a massive deepwater tract (Block Trinidad and Tobago Ultra Deep 1, map below). Per Ms. Persad Bissessar:
“Today’s signing underscores our government’s commitment to strengthening national energy security and to unlocking the full value of our hydrocarbon resources through discipline, policy, competitive terms and trusted partnerships.”
Although another Guyana is unlikely, the enormous lease block presents a great opportunity for Exxon. The consolidated block spans 7,765 square kilometers in the Eastern Tobago Basin in water depths exceeding 2,000 meters. By comparison, Trinidad and Tobago’s total surface area is about 5,128 square kilometers and a typical Gulf of America lease block is only 23 sq km. (Think about that! The size of US offshore lease blocks, which are the world’s smallest, needs to be reconsidered.)
Based on press reports, Exxon will carry out seismic acquisition within 12 months, followed by geological and geophysical studies, and drill up to 2 exploratory wells during the initial phases of the contract. (Reports differ as to whether one of those wells is mandatory, but presumably that won’t be an issue.)
Does this impressive deal reduce the likelihood that America’s largest oil company, which has essentially abandoned the Gulf of America except for its (fading?) carbon disposal ambitions, will participate in the upcoming Gulf lease sale? Politically, failure to participate would not seem to be very astute given the Administration’s promotion of domestic production and energy dominance.
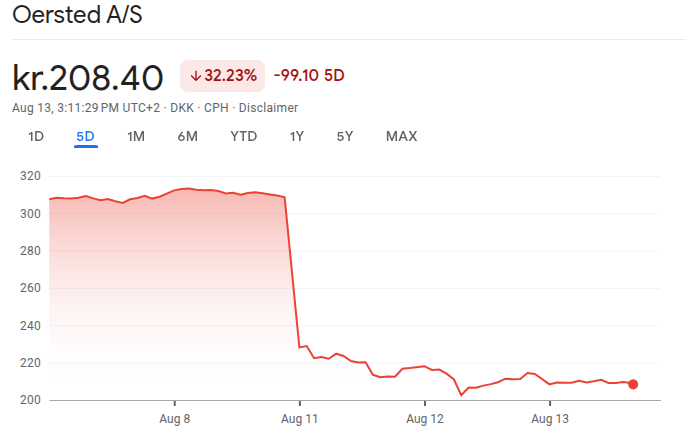
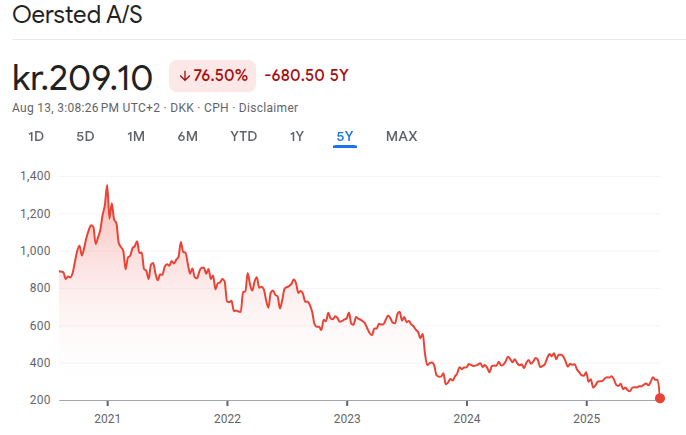
Ørsted’s stock price plummeted on Monday following the announcement of a $9.4 billion rights issue to fund the Sunrise Wind project. The share price has remained depressed (chart below).
Also, although Ørsted attributes its financial woes to the change in US policies, it’s apparent in the second chart (5 year trend) that the decline in Ørsted’s valuation has been ongoing since 2021.
In March, Fitch downgraded Ørsted’s rating to BBB from BBB+, and its subordinated rating to BB+ from BBB-. Further downgrades would seem to be a distinct possibility.
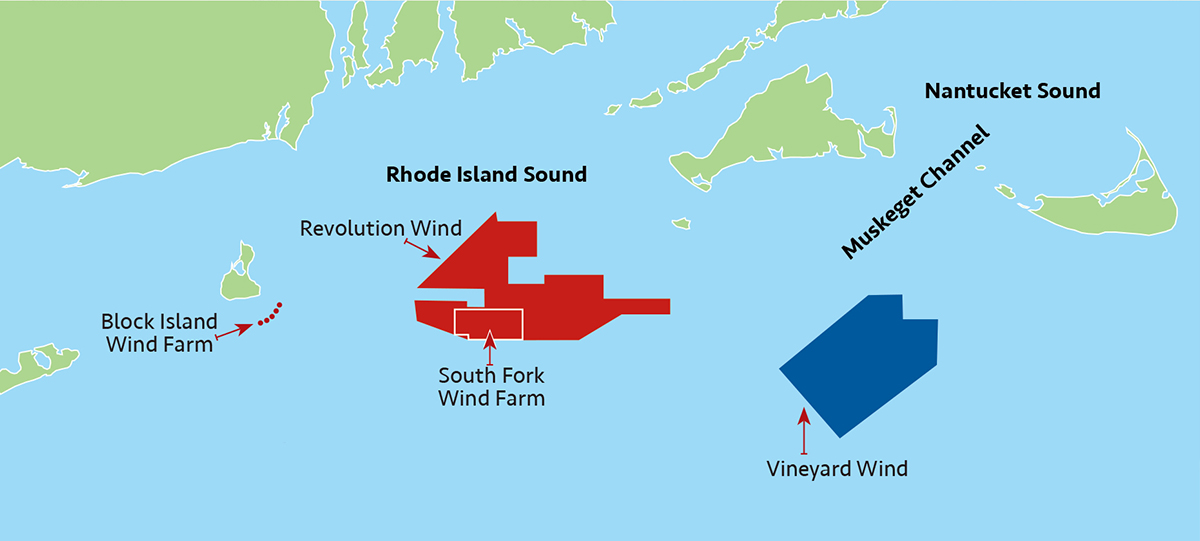
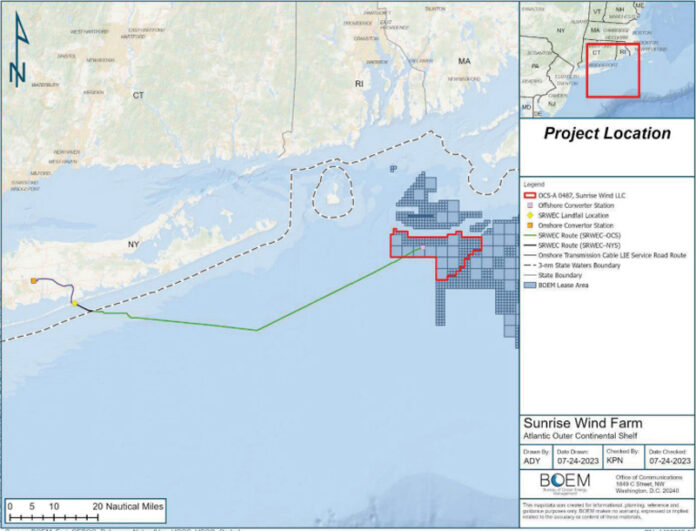
Meanwhile, decommissioning financing for the 3 Ørsted projects under construction in the US Atlantic is far from assured:
Revolution Wind:As they did for Vineyard Wind, BOEM approved Ørsted’s request to defer full decommissioning financial assurance until 15 years after the beginning of construction (see attached letter). This approval was prior to the Renewable Energy Modernization Rule (effective June 29, 2024), which eliminated the need for such waivers.
Sunrise Wind: Ørsted is now solely responsible for funding and constructing this project given the company’s failure to find investment partners. Presumably, decommissioning financial assurance was not required given BOEM’s latitude under the so-called “Modernization Rule.”
South Fork Wind: As is the case with Sunrise Wind, BOEM presumably allowed Ørsted to defer financial assurance for decommissioning as permitted by the “Modernization Rule.”
According to Ørsted, almost 70% of the turbines are installed at Revolution Wind and the first foundations have been installed at Sunrise Wind. South Fork Wind, 12 turbines and an offshore substation, is complete.
Given Ørsted’s strained finances, will BOEM now opt to require decommissioning assurance as provided for in 30 CFR § 585.517?
Ørsted’s situation is atypical in that the Danish government owns a majority (50.1%) stake in the company and Equinor, which is 2/3 Norwegian govt owned, holds a 9.8% stake. How will government ownership factor into BOEM decisions regarding decommissioning assurance? Note that Norwegian govt lobbying may have been one of the factors influencing the decision to allow the resumption of construction on Equinor’s Empire Wind project.
Scientists have discovered a sugar compound from deep-sea bacteria that can destroy cancer cells in a dramatic way. This natural substance, produced by microbes living in the ocean, causes cancer cells to undergo a fiery form of cell death, essentially making them self-destruct. In lab tests and in mice with liver cancer, the compound not only stopped tumors from growing, but also activated the immune system to fight back. This finding could pave the way for entirely new cancer treatments based on sugars from marine organisms.
Deepwater production platforms would be excellent bases for further studying and recovering these microbes.
In addition to the Johnson filing, at least 7 other law firms (links below) have announced class action litigation alleging that Sable Offshore made false or misleading statements regarding the restart of Santa Ynez Unit production.
“This is a significant achievement for the Interior Department and aligns with the Administration’s Energy Dominance initiative, as it successfully resumed production in just five months.“
Will the Dept. of Justice intervene on behalf of Sable?
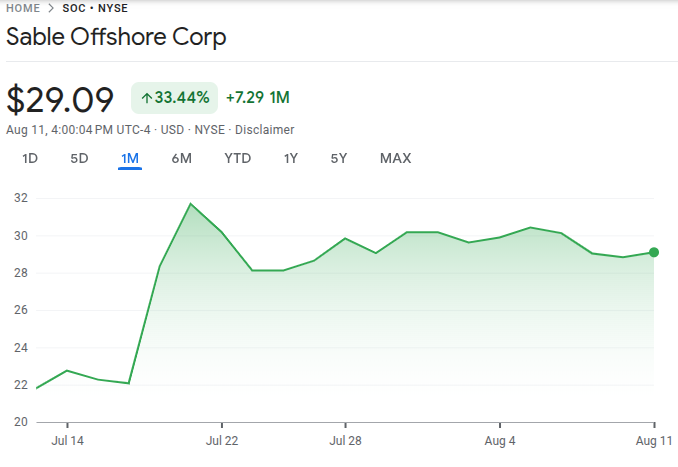
Meanwhile, Sable’s share price rebounded in mid-July and is holding up surprisingly well (see below). Perhaps investors don’t see the class action suits as a significant incremental threat given the risks associated with decisions by 8 California agencies, Santa Barbara County, and various judges, and the persistent challenges by well-organized opponents of offshore production.
BOEM’s streamlining rule codified the deferred financial assurance option. The rule authorizes the transfer of decommissioning risks from developers to taxpayers and consumers by (1) not requiring any additional supplemental financial assurance at the Construction and Operations Plan (COP) approval stage, (2) not requiring supplemental assurance at the installation stage, and (3) providing for incremental supplemental assurance post-installation (e.g. for Vineyard Wind, the full amount is not due until 15 years after installation). See the rule’s previous and current language in the table below (emphasis added).
30 CFR 585.516 – What are the financial assurance requirements for each stage of my commercial lease?
financial assurance required before BOEM will:
language prior to 4/24/2024 “modernization” rule
current language
Approve your COP
A supplemental bond or other financial assurance, in an amount determined by BOEM based on the complexity, number, and location of all facilities involved in your planned activities and commercial operation. The supplemental financial assurance requirement is in addition to your lease-specific bond and, if applicable, the previous supplement associated with SAP approval.
There is no supplemental bond requirement at the COP approval stage.
Allow you to install facilities approved in your COP
A decommissioning bond or other financial assurance, in an amount determined by BOEM based on anticipated decommissioning costs. BOEM will allow you to provide your financial assurance for decommissioning in accordance with the number of facilities installed or being installed. BOEM must approve the schedule for providing the appropriate financial assurance coverage.
A supplemental bond or other authorized financial assurance in an amount determined by BOEM based on anticipated decommissioning costs of the proposed facilities. If you propose to incrementally fund your financial assurance instrument, BOEM must approve the schedule for providing the appropriate financial assurance.
The current financial assurance language is fuzzy enough that BOEM could deny deferred funding requests and require full financial assurance at the time facilities are installed. However, revising the language to clearly require that assurance be fully demonstrated prior to installation would provide clarity and eliminate the deferral option going forward.
The more difficult challenge may be adjusting financial assurance requirements for the projects already under construction. It’s also important to ensure that parent corporations are not shielded from decommissioning and other liability risks.
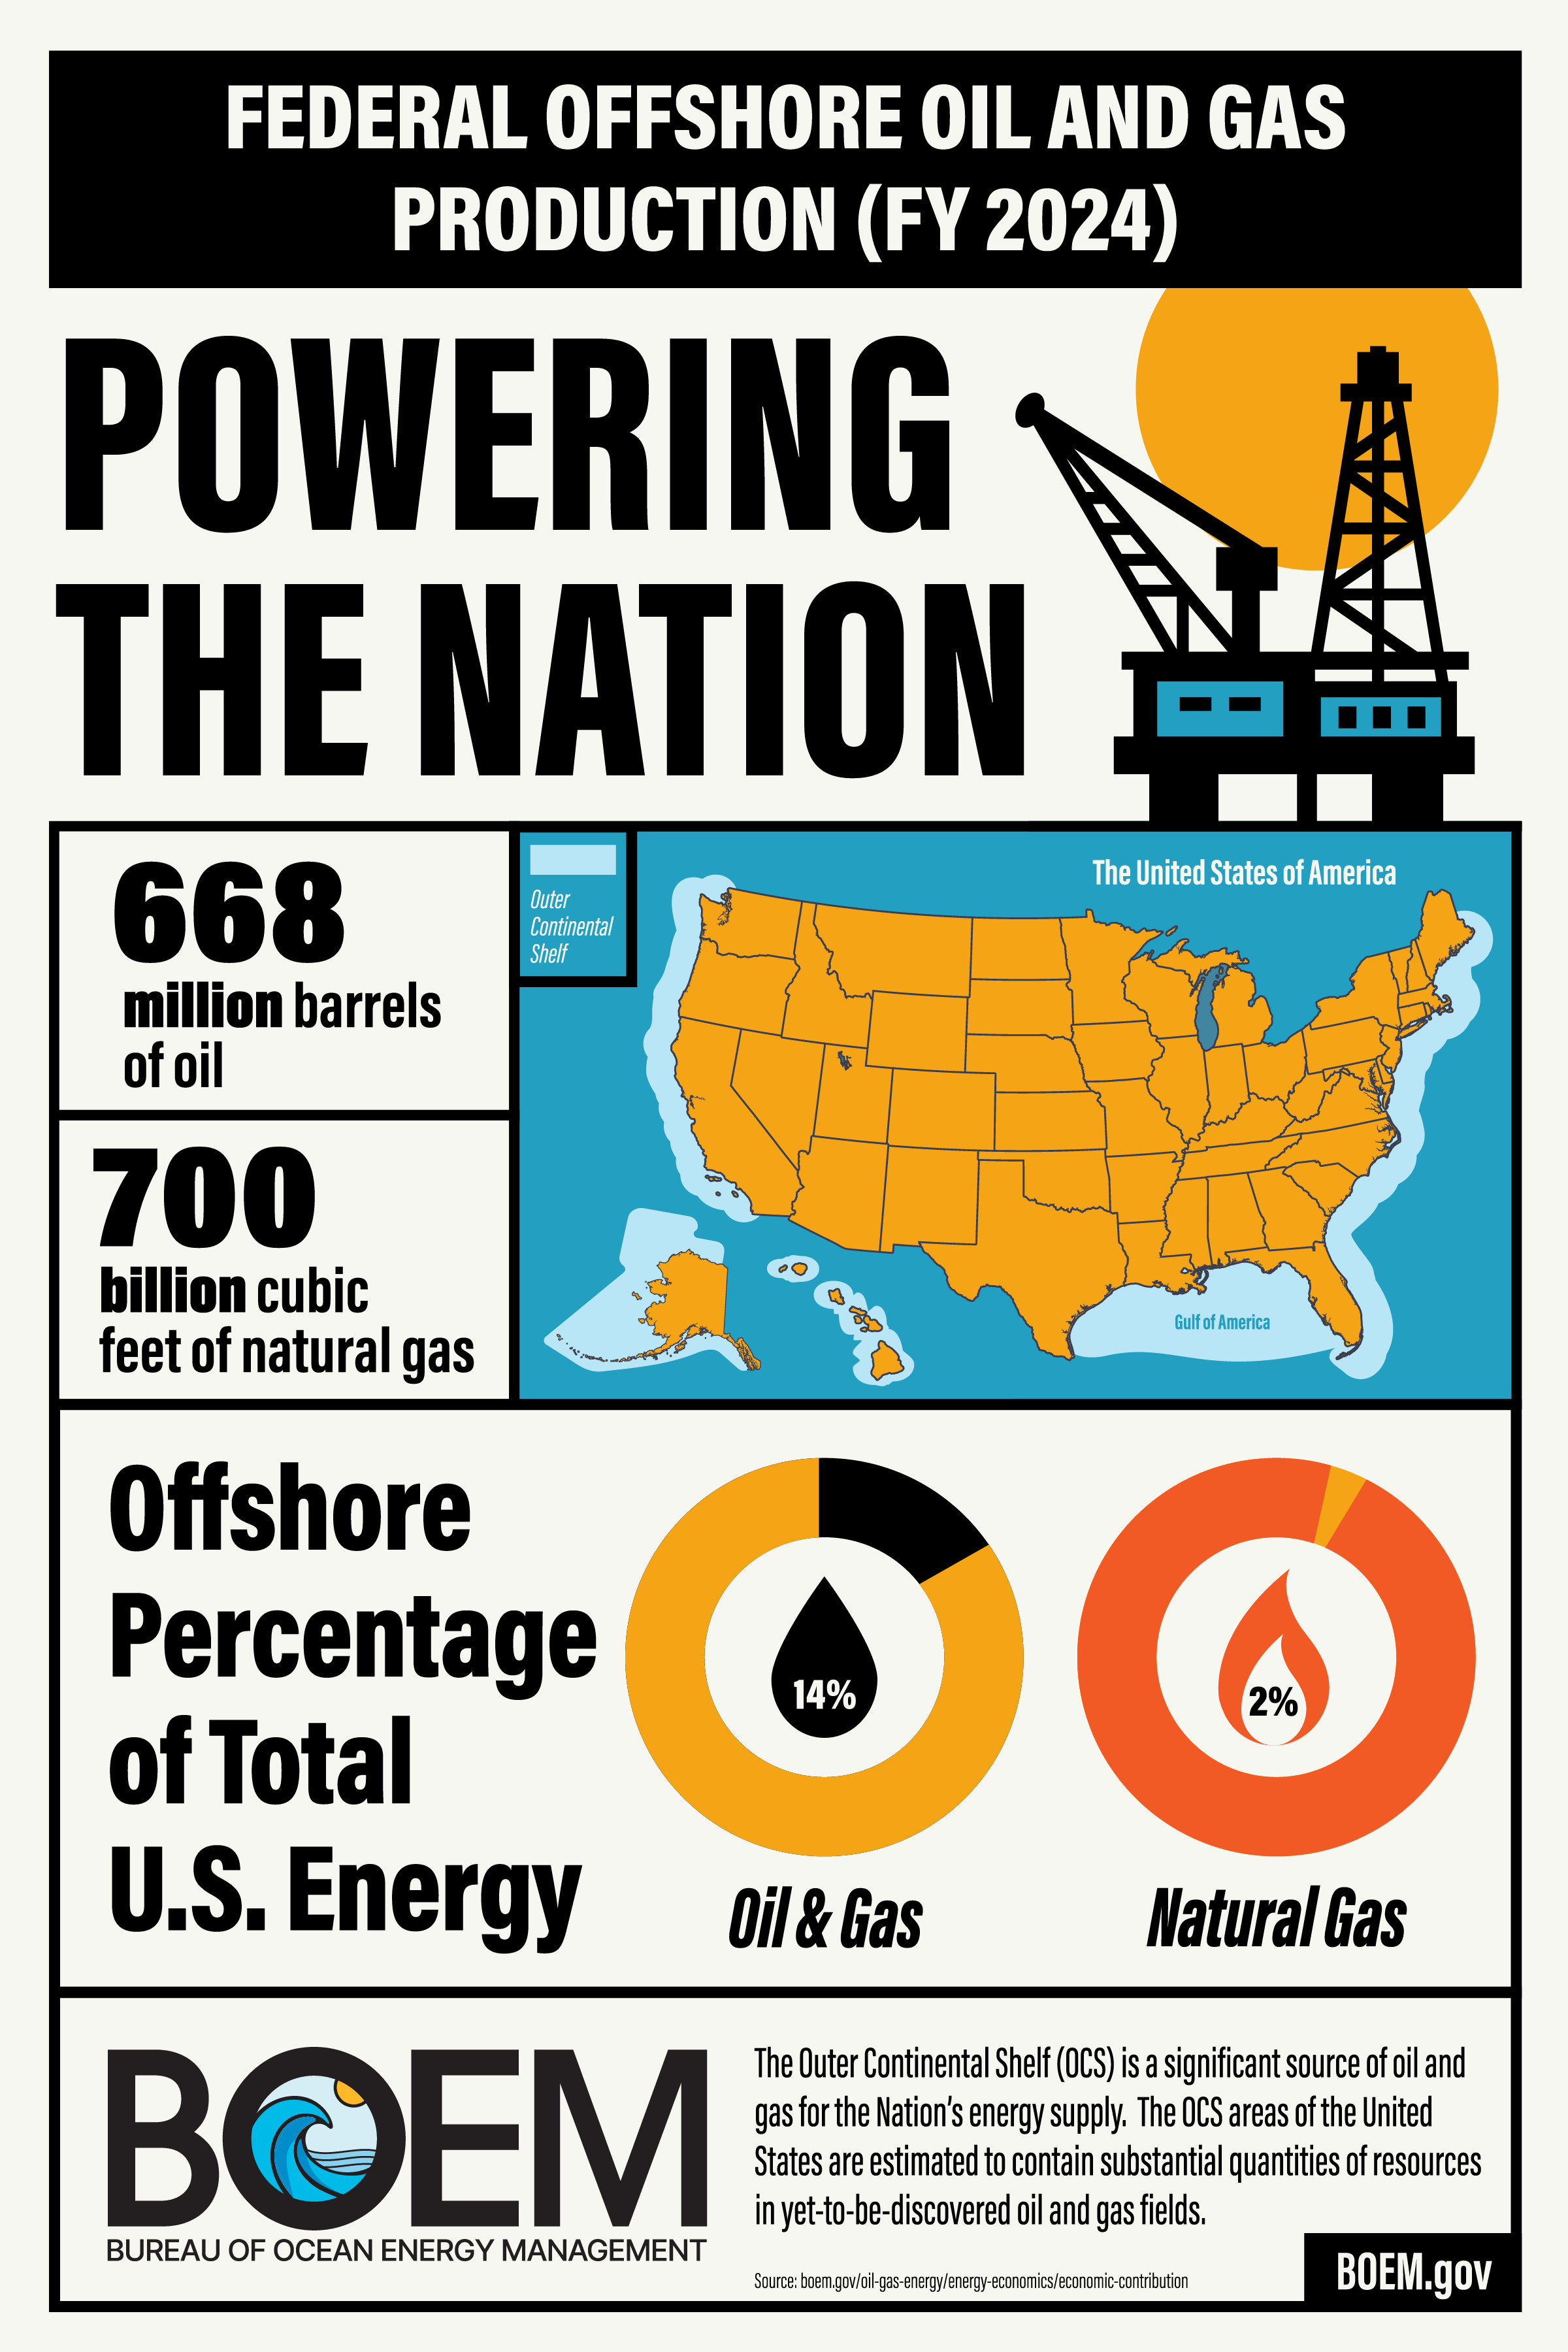
BOEM tweet (12/8/2023):Offshore wind is a once-in-a-generation opportunity to build a new clean energy industry, tackle the climate crisis, and create good-paying jobs, while ensuring economic opportunities for all communities.BOEM tweet (7/31/2025): America’s offshore energy resources are powering the nation. In FY2024 that looks like 668M barrels of oil, 700B cubic feet of natural gasBSEE 2023 logoBSEE 2025 logo
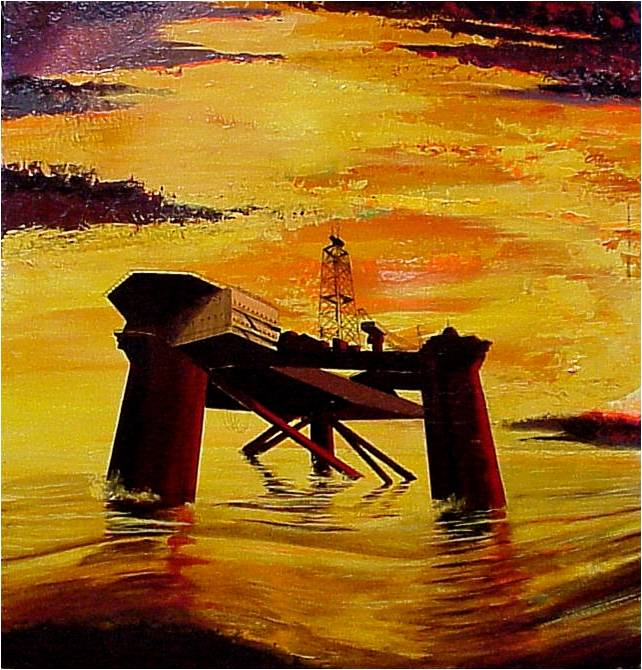
BTW, the new BSEE logo appears to have been influenced by the masterpiece Rig at Sunset 👍 😉
 Bud's Offshore Energy (BOE)
