Feeds:
Posts
Comments

Archive for the ‘Offshore Energy – General’ Category

The terms for congressionally mandated Gulf of Mexico Sale 261 have been proposed. As is also the case for Sale 259, the royalty for leases in <200 m or water is 50% higher than for prior sales. This is partly because of the royalty floor (16 2/3%) established in the Inflation Reduction Act, and partly because the Dept. of the Interior opted for the highest royalty allowed (18 3/4%). The royalty for shelf leases is thus the same as for deepwater leases with much greater production potential.

Rental terms for leases in <200 meters of water are higher and more punitive (for delayed development) than for previous sales and for deepwater leases.

Minimum bid requirements are unchanged from sales 256 and 257, and are higher for deepwater leases ($25/acre for <400m and $100/acre for >400m).

Bottom line: While the terms for deepwater leases are unchanged from Sales 256 and 257, that is far from the case for shelf leases where royalty rates were increased by 50% and rentals were increased by 43% for all lease years.

SaleDate% royalty
(<200m)
year 1-5/6/7/8+ rentals
($/acre, <200m)
year 8+ rentals for
leases in 400m+ ($/acre)
25611/18/202012.57/14/21/2816
25711/17/202112.57/14/21/2816
2593/29/202318.7510/20/30/4022
2619/27/202318.7510/20/30/4022

Read Full Post »

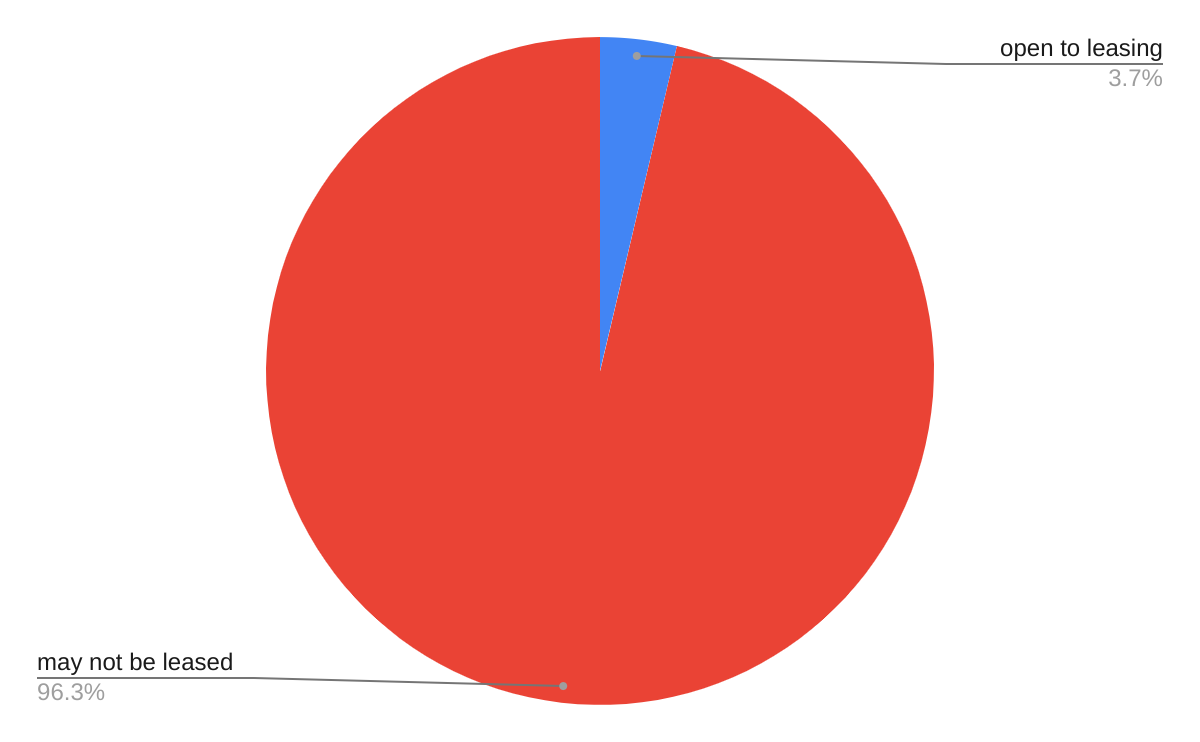
Of the 1.7 billion acres of Federal land on the US Outer Continental Shelf, only about 73 million acres in the Gulf of Mexico and 1 million acres in the Cook Inlet may be offered for oil and gas leasing. Official or de facto exclusions prohibit leasing in the entire US Atlantic, the entire US Pacific, all Alaska areas except the Cook Inlet, and most of the Eastern Gulf of Mexico. No other coastal nation has restricted access to oil and gas resources to this extent.

As demonstrated in recent sales, many of the tracts being offered have little or no production potential. Only 308 tracts (1.7 million acres) received bids in GoM Sale 257. 94 of the high bids were for sequestration purposes and were arguably invalid. Sale 258 in the Cook Inlet only received a single bid.

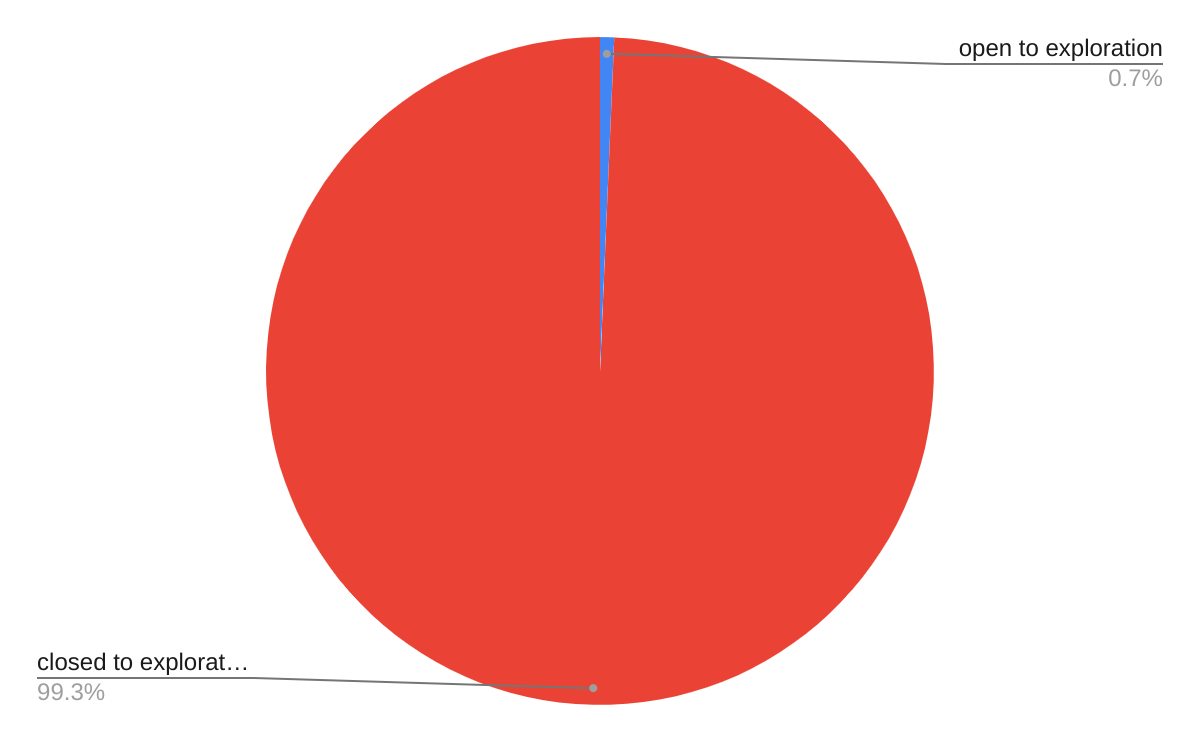
The number of active leases, currently 2153, has been at a historically low level for the past 2 years. Only 0.7% of our OCS is leased and thus open to exploration. 26% (552) of these leases are already producing, leaving a historically low number of nonproducing leases.

Oil is where you find it, not where you wish it was or want it to be. Denying access to all but a small portion of the OCS limits exploration strategies and prevents publicly owned resources from supporting our economy in the manner intended by the OCS Lands Act.

Read Full Post »

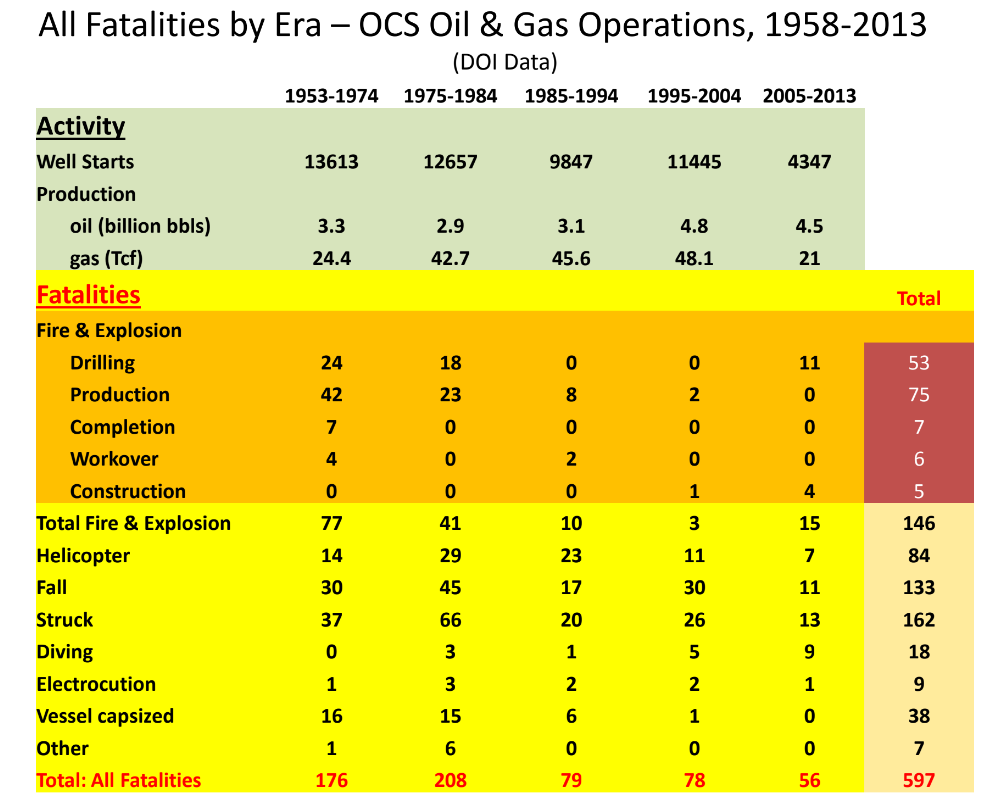
Per yesterday’s post, below are US OCS fatality data from a 2014 presentation. Ten year intervals were selected for 1975-2004. The longer 1953-1974 era was selected so the activity indicators (well starts and production) would be comparable with the next 3 intervals. The last interval (2005-2013) was limited because the presentation was prepared in 2014.

Fire/explosion fatalities exceeded fall/struck fatalities only in the first interval (1953-1974). As one would expect, the fire/explosion deaths were associated with a limited number of better known incidents (e.g. Main Pass 41, Bay Marchand, Macondo). While the overall trend is favorable, fall/struck incidents and helicopter fatalities at offshore platforms have proven to be more chronic.

I hope to update these data in the not too distant future.


Read Full Post »

The most common causes of offshore fatalities and serious injuries, falls and being struck by equipment, receive little media attention because there is no blowout, oil spill, or fire. However, these are often the most difficult types of incidents to understand and prevent. Human and organizational factors predominate, and prevention is dependent on a strong culture that emphasizes worker engagement, awareness, teamwork and mutual support, effective training and employee development, risk assessment at the job, facility, company, and industry levels, stop-work authority, innovation, and continuous improvement.

This new BSEE Safety Alert addresses such a fatal incident on the Pacific Khamsin drilling rig, and makes recommendations that have widespread applicability.

Incident summary:

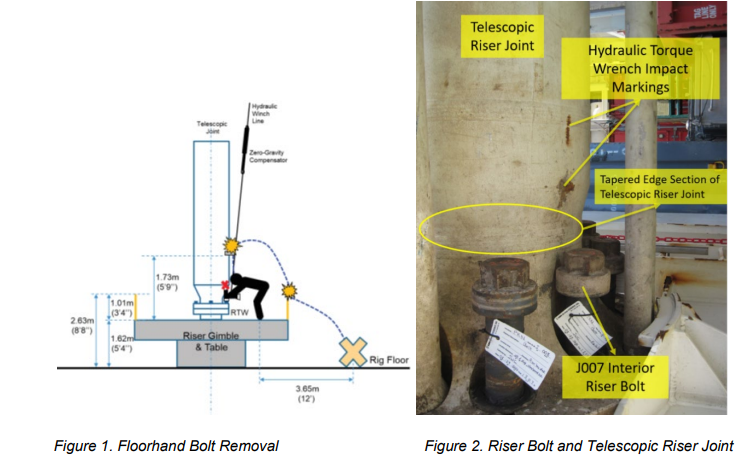
While unlatching the lower Marine Riser Package from the Blowout Preventor in preparation for ship relocation, a crewmember was lifted into the air after being struck by a hydraulic torque wrench (HTW), hitting a riser clamp approximately six feet above the elevated work deck before falling to the rig floor. The crew member was given first aid and transported to the drillship’s hospital, where he was later pronounced deceased.

In an upcoming post, BOE will provide historical fatality data by cause and operations category.

Read Full Post »

HOUSTON — Oil and gas industry leaders say they’ve seen a big shift in tone from the Biden administration over the past year, helping to smooth over one of the president’s rockiest relationships.

Washington Post

Perhaps the Washington Post reporter is correct, but the “big shift in tone” is not apparent in the offshore sector. The only lease sales have been mandated by Congress, the 5 year plan is still 9 months from completion, the lease sale terms have been less than favorable, and language in the draft 5 year plan does in fact express the intent to phase out oil and gas.

Read Full Post »

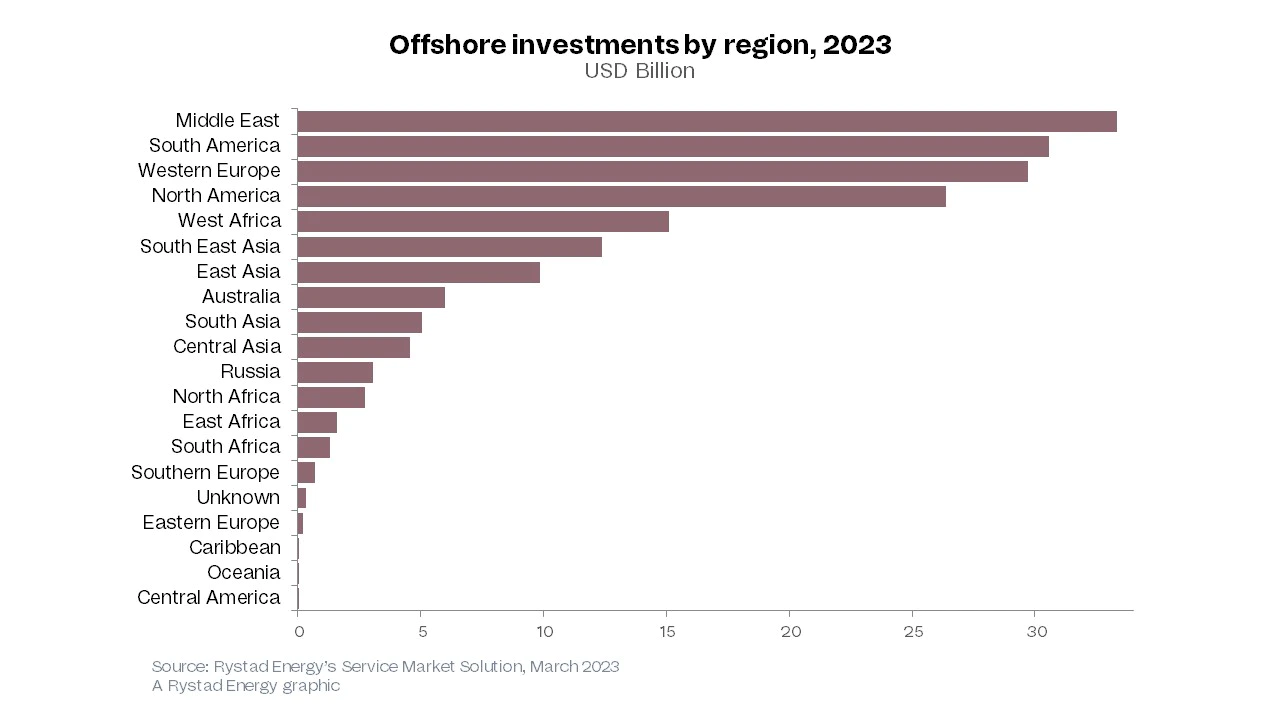
The offshore oil and gas (O&G) sector is set for the highest growth in a decade in the next two years, with $214 billion of new project investments lined up. Rystad Energy research shows that annual greenfield capital expenditure (capex) broke the $100 billion threshold in 2022 and will break it again in 2023 – the first breach for two straight years since 2012 and 2013.

Offshore activity is expected to account for 68% of all sanctioned conventional hydrocarbons in 2023 and 2024, up from 40% between 2015-2018.

Rystad

Comments:

  • Middle East investment continues to be strong
  • Good for South America thanks to Brazil (16 new FPSOs by the end of the decade) and the Guyana success story.
  • Strong forecast for Norway and the UK boosts Europe.
  • North America could do far better with less obstructive access policies.

Read Full Post »

Washington, DC — Today, U.S. Senator Joe Manchin (D-WV), Chairman of the Senate Energy and Natural Resources Committee, released the following statement on the Department of the Interior’s (DOI) unprecedented delay in releasing a five-year leasing plan. 

“Monday night, the Department of the Interior made it painfully clear – again – that they are putting their radical climate agenda ahead of our nation’s energy security, and they are willing to go to great lengths to do it. The earliest that Interior will release a legally required program for 2023-2028 offshore oil and gas leasing will be the end of this year. That’s 18 months late. This is the first time in our nation’s history that we haven’t had a 5-year leasing program released before the old plan expired. Every other Administration, Democrat and Republican, has managed to follow the law in a timely fashion.

“Let me be clear – this is not optional. The Outer Continental Shelf Lands Act mandates that the Secretary of the Interior “shall prepare” this program to “best meet national energy needs.”

“What is even more terrifying is that on top of this disturbing timeline, Interior refuses to confirm if they intend to actually include any lease sales in the final plan, which is an issue I sounded the alarm about when Secretary Haaland appeared before the Senate Energy and Natural Resource Committee on May 19, 2022. I will remind the Administration that the Inflation Reduction Act also prevents them from issuing any leases for renewables, like offshore wind or onshore solar unless there are first reasonable lease sales for oil and gas that actually result in leases being awarded. And I will hold their feet to the fire on this.” 

Senator Manchin

Plain English; no need for interpretation 😉

Read Full Post »

Senator Manchin and the Alaska delegation criticized the DOI decision memo for Sale 258. The memo implied that the highest allowable royalty rate was chosen to minimize bidder interest and limit future production. Unfortunately, the “Inflation Reduction Act,” which mandated these lease sales, was not particularly helpful in creating interest in the less attractive OCS tracts like those in the Cook Inlet and the shallower waters of the Gulf of Mexico.

Sec. 50261 of the IRA raised the minimum allowable royalty rate from 12 1/2% to 16 2/3%, while capping the maximum rate at 18 3/4%. This provision favors deepwater operators, typically majors and large independents, whose royalty rates were capped at 18 3/4%, the same rate as for previous OCS sales.

Conversely, the IRA royalty provisions penalize the smaller companies and gleaners who are critical to sustaining shallow water (shelf) operations, including environmentally favorable nonassociated (gas-well) natural gas production, by raising the minimum royalty rate to 16 2/3%. DOI exacerbated IRA’s impact by electing to charge the highest allowable royalty rate for Cook Inlet and GoM shelf leases. The net result was a 50% royalty rate increase from prior sales (12.5 to 18.75%).

The table below illustrates the royalty rate implications of the IRA language and the DOI decisions.

AreaSaleDate% royalty: <200m water depth% royalty: >200m water depth
Cook Inlet2446/21/201712.512.5
GoM25611/18/202012.518.75
GoM25711/17/202112.518.75
Cook Inlet25812/30/202218.7518.75
GoM2593/29/202318.7518.75

Notes:

  • The base primary term for GoM shelf leases is only 5 years vs. 10 years for leases in .>800 m of water.
  • In lease year 8 and beyond the rental rates are nearly double for shelf leases vs. deepwater leases ($40/ac vs. $22/ac).
  • While deepwater development typically requires more time, the higher rental penalty for delayed shelf production (which must be approved by BSEE) is not warranted. $40/acre or $240,000 per year (plus inspection and permitting fees) is a high cost for a marginal shelf lease.
  • Cook Inlet Sale 244 drew 14 high bids totaling more than $3 million. Sale 258 drew only 1 bid of $64,000. While many factors influence lease sale participation, the 50% increase in royalty rate certainly made the Cook Inlet leases less attractive.
  • Other than the increased royalty rate, the terms for both Cook Inlet sales were essentially the same. The primary lease term was 10 years and the minimum bonus bid was $25/hectare for both sales. The rental rate was increased by only $3/hectare ($13 to $16).

Read Full Post »

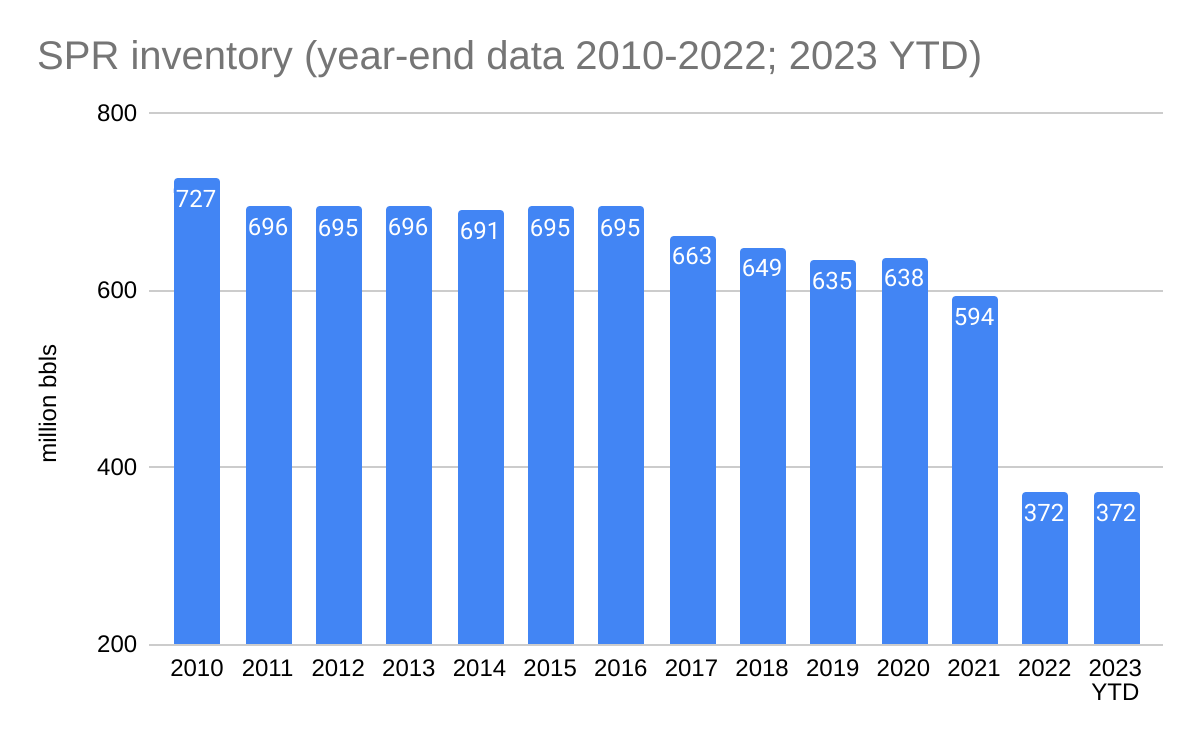
That is the amount of oil the US government has “borrowed” from the Strategic Petroleum Reserve without replacing. At $80/bbl, that’s ~$28 billion worth of oil. Not refilling the SPR exposes the US to much greater costs, in terms of economic and national security risks. Those who were around during the 1970’s certainly remember the embargoes and the resulting disruptions that led to the establishment of the SPR.

The SPR has a fill rate of only 685,000 bopd, so a complete refill would require 518 days, which would have to be spread over years because of supply, operational, maintenance, and price considerations. The promised purchase of 3 million bbls in February never occurred, and we are now told that DOE “would like to start buying within the next year, depending on the window of opportunity.” This is not particularly encouraging, especially given that the mandatory sale of another 26 million bbls is upcoming this spring. So it looks like the SPR may be down another 20+ million barrels heading into 2024, an election year. Good luck making significant purchases then.

This is the hole we are in as a result of non-emergency SPR sales for price moderation purposes. Meanwhile, Congress has proposed the following legislation:

The last bill is interesting, but has little chance of passing and would be difficult to implement given other legislative, judicial, and administrative constraints on leasing and production. Having a plan is one thing; implementing it is quite something else.

Read Full Post »

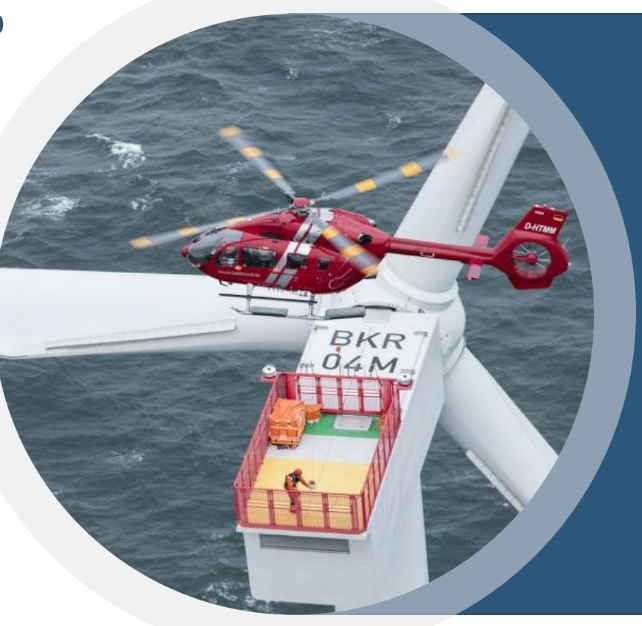
Presentations from the January 2023 HSAC meeting have now been posted. None of the presentations addresses the tragic crash in the Gulf of Mexico on 29 December. This is understandable given the ongoing investigation.

Attached is an update from the Helideck Committee which also addresses wind farm issues.

Read Full Post »

« Newer Posts - Older Posts »