Feeds:
Posts
Comments

Archive for the ‘Offshore Energy – General’ Category

In the past the thought was that we would be importing LNG, i.e. “Rigs-to-Regasification.” Now that we are exporting LNG, we are adding “Rigs-to-Refrigeration” to the alternative use list.

Per our previous post on this topic, New Fortress Energy is moving forward with fast-track LNG projects in the Gulf. Three converted jack-up rigs purchased from Maersk will make up the first “Fast LNG” liquefaction train.
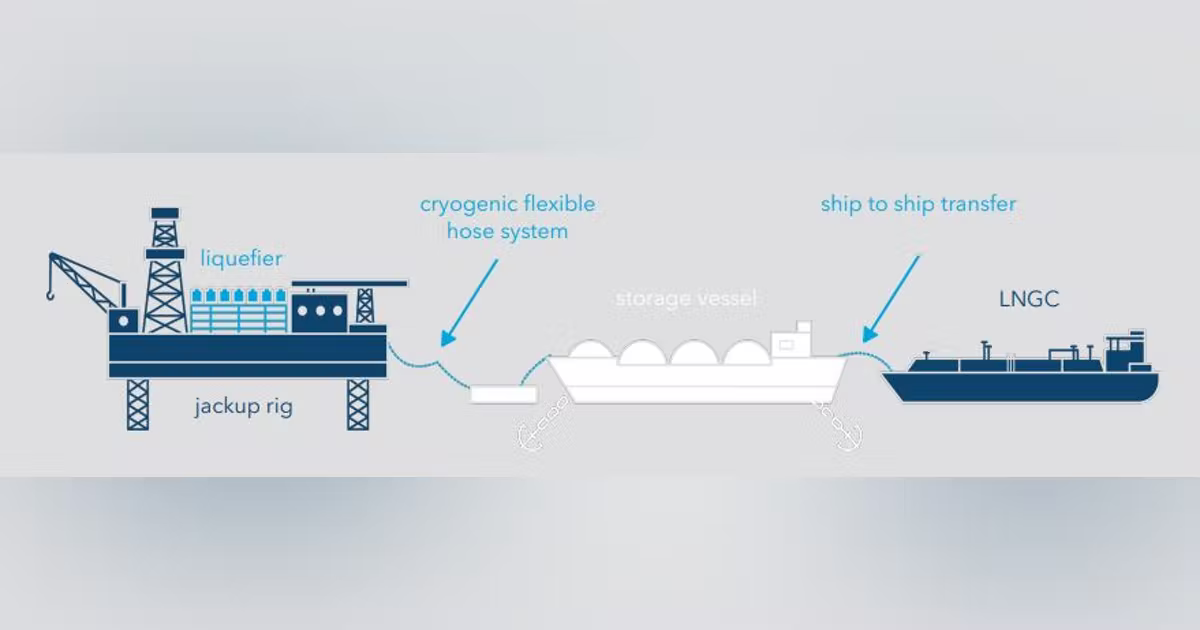
New Fortress is planning to install its first two “Fast LNG” units in West Delta Lease Block 38, located about 16 nm off Grand Isle, Louisiana. The two independent liquefaction trains at this deepwater “port” would export about 1.4 million tonnes per annum (mtpa) of LNG each. Though small by shoreside standards, the plant design would offer a number of advantages, like low cost and speed to market – a critical factor at a time of high demand for LNG. The company says that it should be able to produce each facility on an 18-20 month timescale, from engineering through construction and commissioning. 

Maritime Executive

Given the challenges posed by tropical storms, particularly for jackup units, the design criteria for these “permanent” jack-up liquefaction facilities and the role of classification societies are of particular interest.
Read Full Post »

Newfoundland is only 30 to 90 minutes ahead of the other Atlantic provinces and states, but the offshore energy gap is much greater. Newfoundland continues to be the only Atlantic producer, and the future is looking brighter with another positive step by industry and the provincial government.

Calgary, Alberta (May 31, 2022) – Cenovus Energy Inc. and its partners have agreed to restart the West White Rose Project offshore Newfoundland and Labrador. First oil from the platform is anticipated in the first half of 2026, with peak production anticipated to reach approximately 80,000 barrels per day (bbls/d), 45,000 bbls/d net to Cenovus, by year-end 2029.

Construction includes the completion of the concrete gravity structure and topsides, which will serve as the drilling platform for the project. Once installed, the platform will be tied into existing infrastructure.

Cenovus
West White Rose Extension Project

Read Full Post »

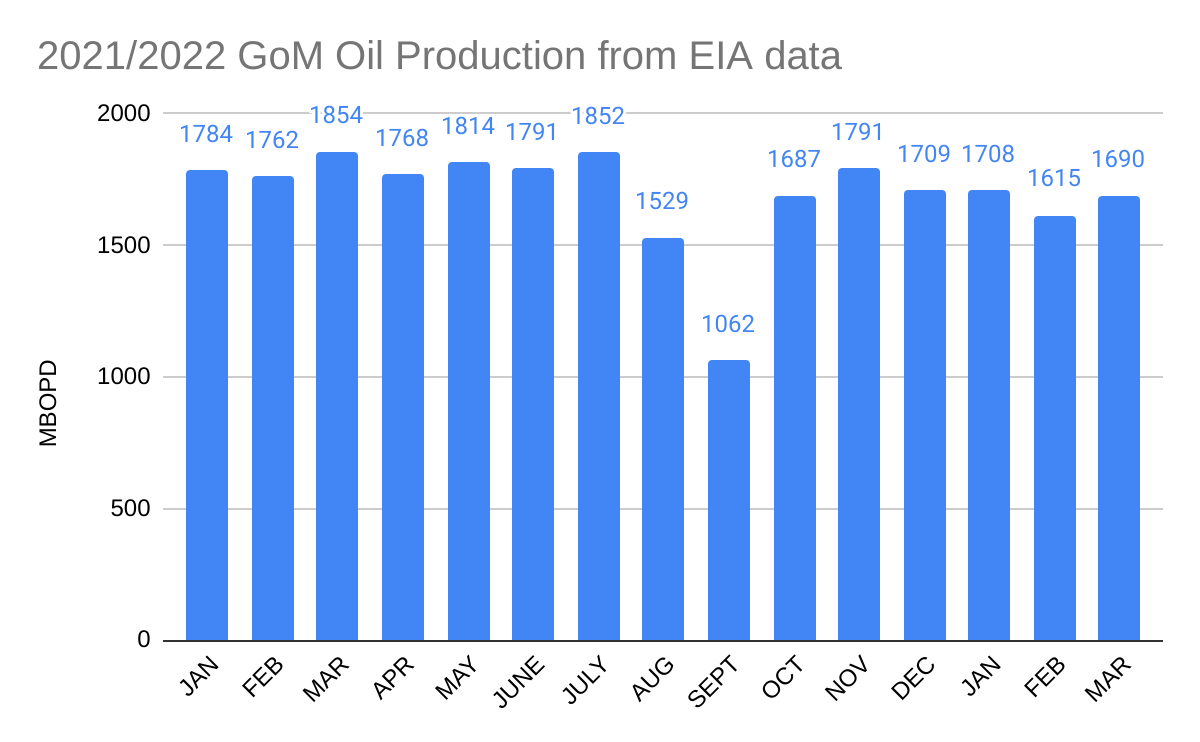
Waiting for a boost from the deepwater startups. The first of that group, King’s Quay did not begin producing until April.

Read Full Post »

Read Full Post »

There won’t be a deal without significant energy production provisions and Manchin is on the record regarding the need for action on offshore oil and gas leasing. We’ll see what happens.

Read Full Post »

Federal Oil & Bas Corp. (FOGCO)

Guyana’s pending decision regarding the formation of a national oil company brings back memories of unsuccessful attempts to do the same in the US in the 1970s.

The most serious attempt at forming a national oil company in the US was a 1975 Senate bill to establish the Federal Oil and Gas Corporation or FOGCO. (Oddly, the bill’s sponsors weren’t troubled by that acronym.) FOGCO was proposed at a time when natural gas supplies didn’t satisfy demand, and that was the primary impetus behind the legislation. (Supply issues went away when price controls were lifted.)

Concerns about a FOGCO then and now:

  • The political pressures under which a national oil company operates are not conducive to sound, expeditious decisionmaking. (Unfortunately, some current industry execs seem overly responsive to pressure from governments and activist organizations, which is not always in the best interest of the company and its shareholders).
  • Would limit competition and private investment.
  • Would delay or prevent innovation:
    • The shale revolution was driven by nimble private companies operating on private land in supportive states. Why is there Marcellus shale development in PA, WV, and OH, and none in NY? (Hint: It’s not the absence of resources.) Why could the US shale experience not be replicated in Europe?
    • Innovative deepwater development projects were driven by private companies and the supportive public policies of the 1990s.
  • A national oil company could be the first step in the process of nationalizing the petroleum industry.

Guyana is far different from the US and should do what is perceived to be in their best interest. Best wishes to the people of Guyana as they weight their options.

Read Full Post »

Transocean Deepwater Atlas

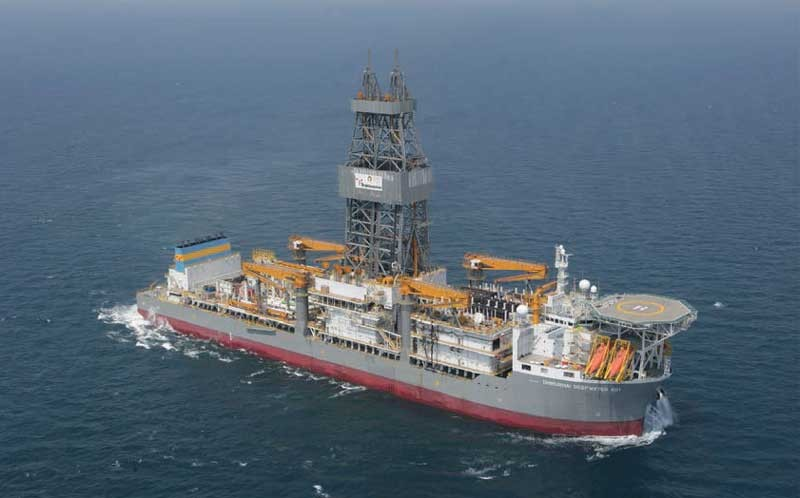
The drilling business, particularly the deepwater sector, has never been for the faint of heart, and the past few years have included the added stresses of COVID, negative oil prices, anemic exploration activity, and offshore leasing “pauses.” Transocean nonetheless managed to build two 8th generation drillships, the Deepwater Atlas and Titan, both of which are slated to operate in the Gulf of Mexico.

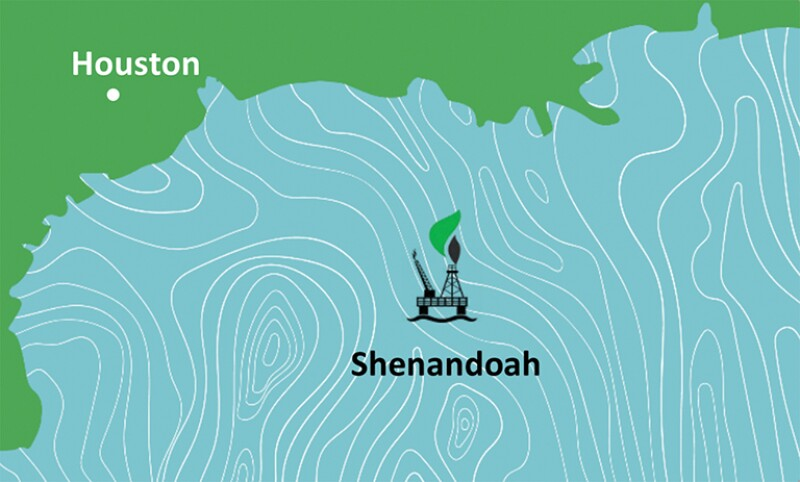
The Atlas will begin drilling for Beacon Offshore Energy (unrelated to the BOE blog 😀) in the Shenandoah field (almost heaven?😀) later this year. The Titan is expected to begin drilling for Chevron next year. The rigs will be outfitted with 20,000 psi blowout prevention equipment and will be well-equipped for the growing number of high pressure prospects in the Gulf. Here is Transocean’s promotional video for the two rigs.

Both Beacon and Chevron fared well on our Gulf of Mexico scorecard. A bit of information about Beacon (BOE):

  1. Wholly owned by funds managed by Blackstone Energy Partners.
  2. CEO Scott Gutterman was previously the CEO of LLOG.
  3. There are a number of related investment partnerships under the Beacon umbrella and they are often joint lease owners.
  4. Per BOEM data, BOE has interest in 11 Gulf of Mexico leases.
  5. The company has an excellent compliance record: 12 facility inspections (presumably all were drilling units) resulted in only 1 INC (violation).
  6. Per BSEE, Beacon had 22 well starts since 2008. (Mystery: While the Blackstone and Beacon websites indicate that the company was formed in 2016, BSEE’s online borehole file shows 10 well starts prior to that year with the exact same company name. Presumably, the borehole file data are in error because BOEM data do not show any Beacon lease interest prior to 2018.)
  7. Beacon bid on one tract in Lease Sale 257 (Nov. 2021) and was the sole bidder (sale was voided by DC Federal Court).
  8. Beacon bid on 3 tracts in Sale 256 (Nov. 2020) and was the high bidder on one.
  9. Beacon acquired interest in 2 leases in Sale 254 (March 2020), 7 in Sale 252 (March 2019), and 2 in Sale 251 (Aug. 2018)
  10. In February 2022, Blackstone reportedly advised clients that they would no longer invest in oil and gas projects. Presumably, that doesn’t affect the Beacon operations (or perhaps the folks at Blackstone have come to their senses 😀).

Read Full Post »

Not really, but current economic and energy security realities doomed a bill to prohibit drilling and production in State waters. Strong quotes from bill opponents:

“SB 953 was held because it didn’t work — it was going to cost the state billions of dollars for a symbolic victory,” Andrew Meredith, president of the State Building and Construction Trades Council of California, said in a statement. “The California Senate is rightfully more concerned with actually improving the plight of workers and our environment than chasing headlines.”

Politico

“I think most legislators understand that every barrel of oil we don’t produce here under our strict environmental rules must be imported by foreign tankers floating offshore in our crowded ports from Iraq, Saudi Arabia, or the Ecuadorian rainforest,” California Independent Petroleum Association CEO Rock Zierman said in a text message.

Politico

Read Full Post »

WASHINGTON — During testimony before the U.S Senate Committee on Energy and Natural Resources today, Secretary of the Interior Deb Haaland confirmed that, despite delays in implementation from the previous Administration, the Interior Department will release the Proposed Program – the next step in the five-year offshore energy planning process – by June 30, 2022, which is the expiration of the current program. A Proposed Program is not a decision to issue specific leases or to authorize any drilling or development.

DOI

Here is the timeline for the 5 Year Leasing Program (light blue).

A sale this year under the new program is thus highly unlikely. The process will no doubt be delayed even further by litigation. As we have said previously, the only hopes for a sale this year are a successful appeal of Judge Contreras’s Sale 257 ruling or successful congressional action (unlikely but possible under the circumstances).

Read Full Post »

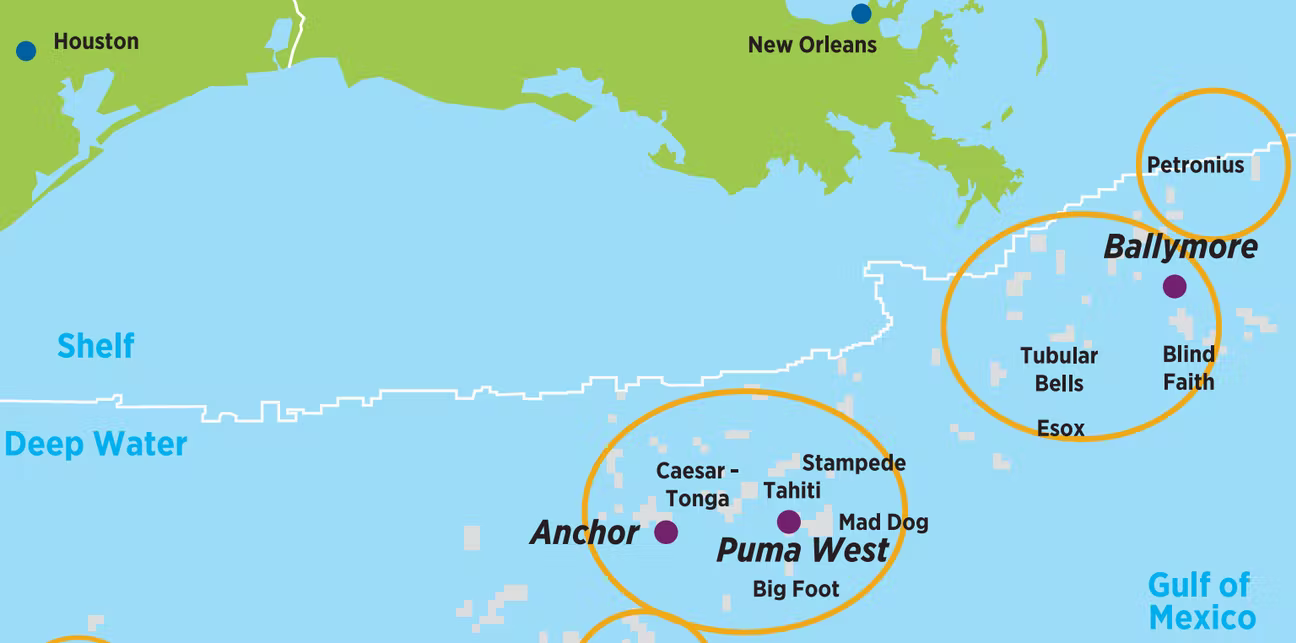
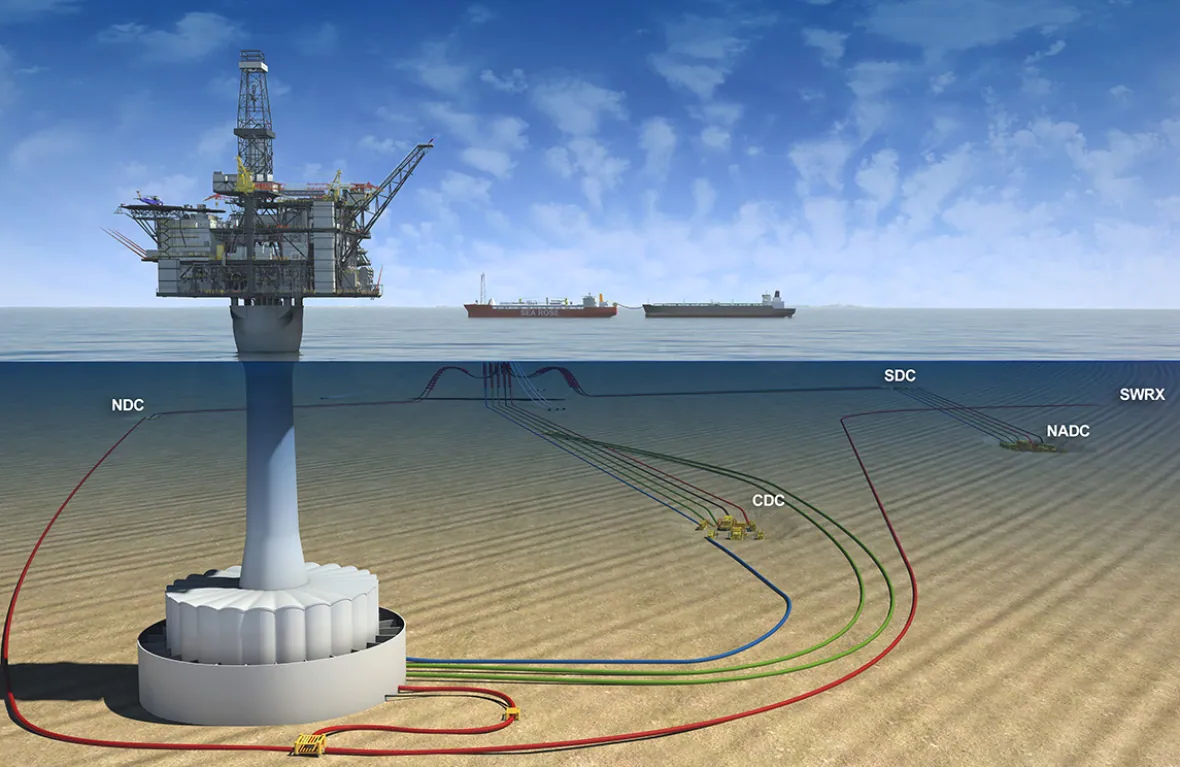
Ballymore will be produced with 3 seafloor wells (6540′ water depth) that are expected to transport 75,000 bopd via a three-mile subsea tieback to Chevron’s Blind Faith floating production unit. Per BOEM, the Ballymore field was discovered in December, 2017. First production is expected to be in 2025.

Pre-production inspection, Shell Vito
Vito

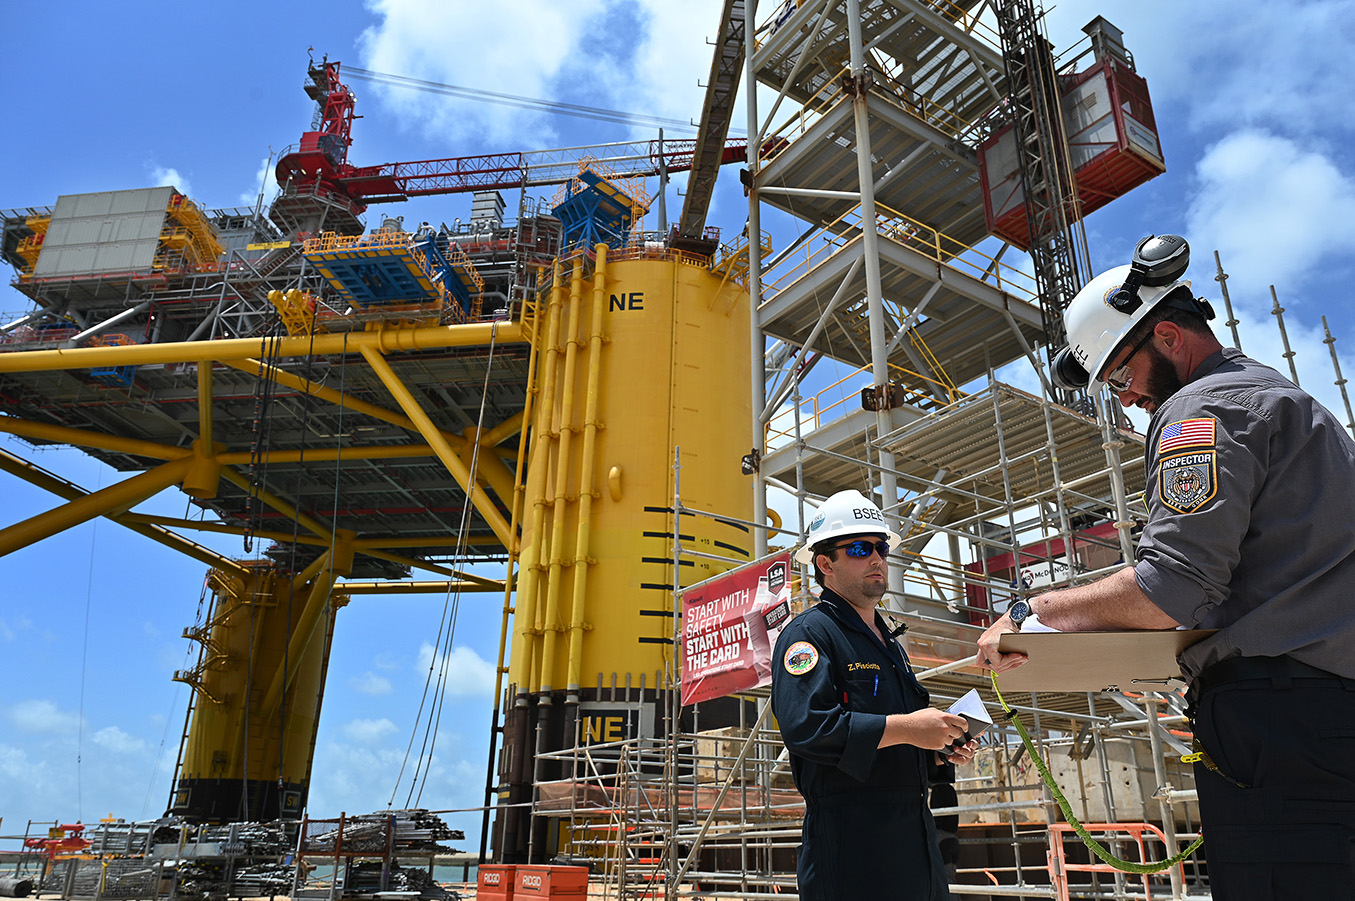
Shell’s Vito floating production unit was inspected last week by BSEE personnel. Vito is expected to begin production later this year or early next year and produce up to 100,000 bopd. Per BOEM data, the Vito field was discovered in 2010.

As these projects demonstrate, deepwater development takes time and is often dependent on related projects on other leases. This is why future production is dependent on regular, predictable lease sales.

Read Full Post »

« Newer Posts - Older Posts »