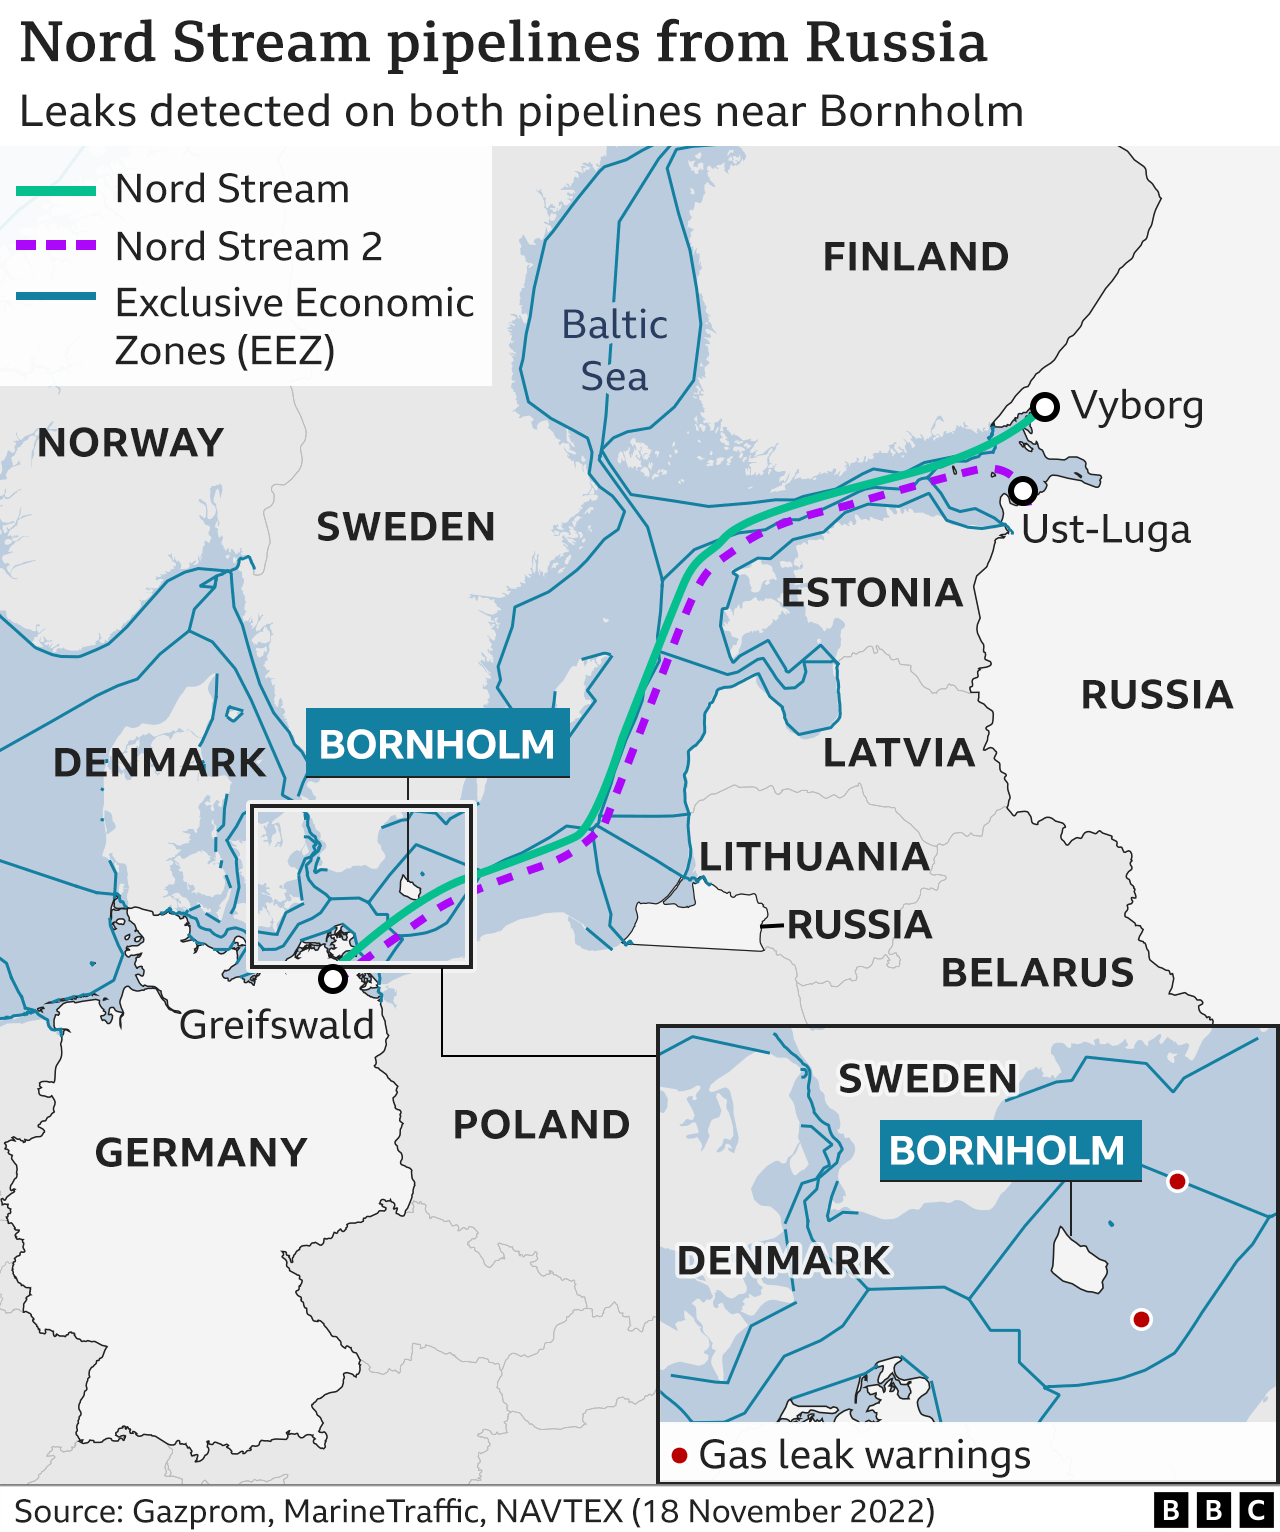
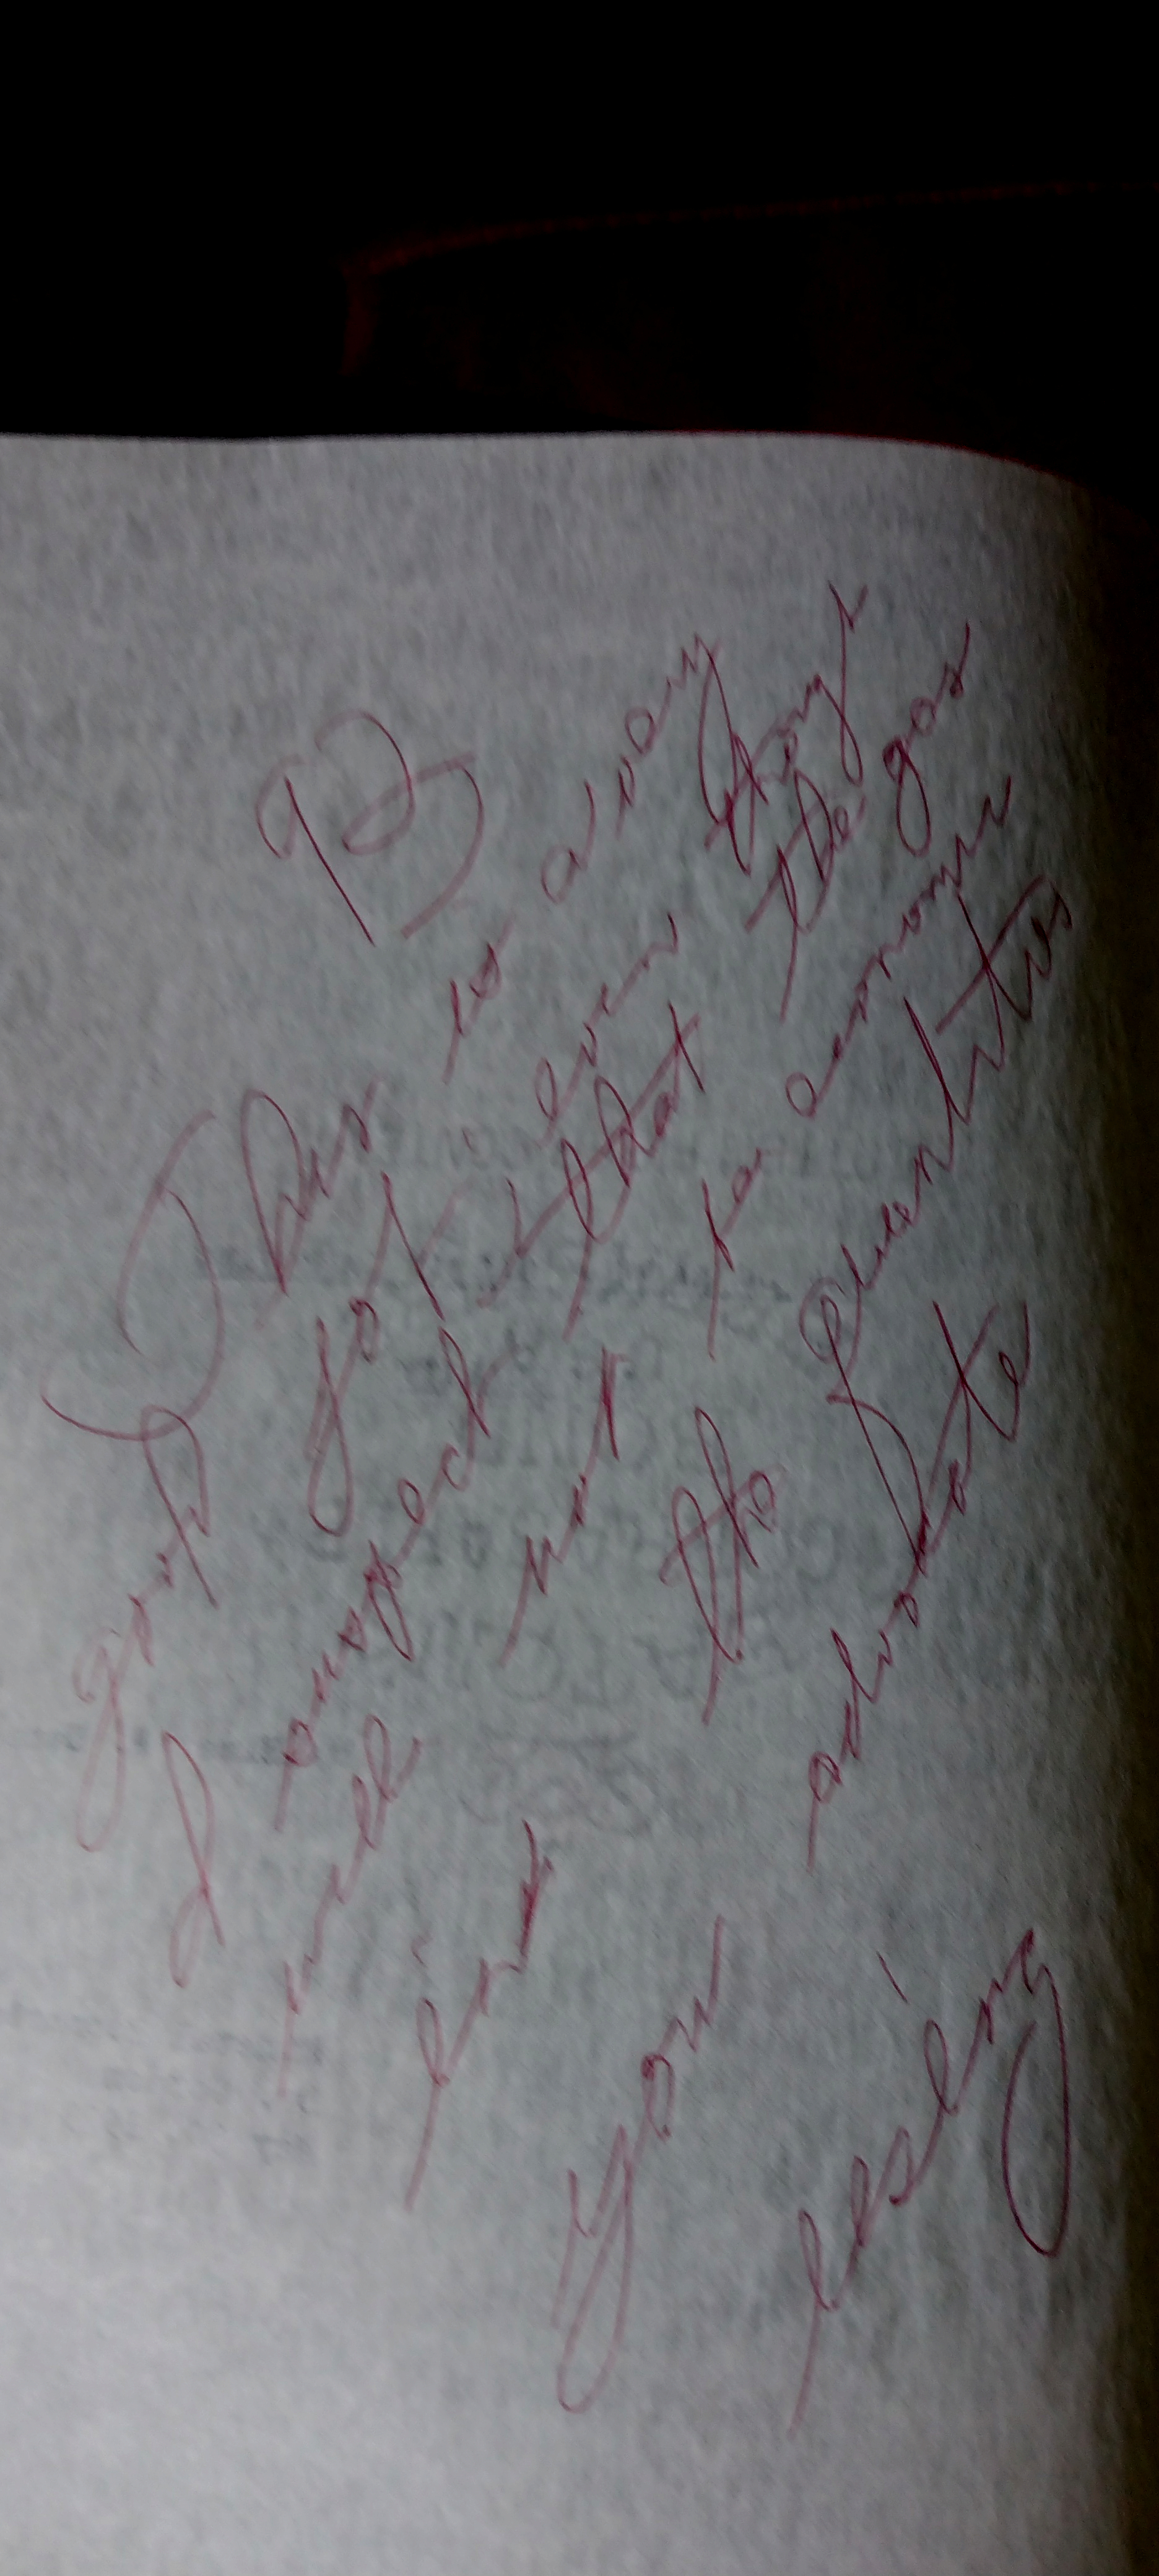Yesterday, the trial of a Ukrainian officer began in a Hamburg courtroom. See the X post and video below.
The big issue, of course, is the extent of Ukrainian govt involvement in the sabotage.
🇩🇪🇺🇦Germany puts a Ukrainian officer on trial for blowing up Nord Stream as a WAR CRIME ordered by Kyiv
Serhii K. will walk into a Hamburg courtroom today as the first person ever tried for the 2022 blasts that cut Germany off from the pipeline that once carried half its gas… pic.twitter.com/nBWPKWAPzj
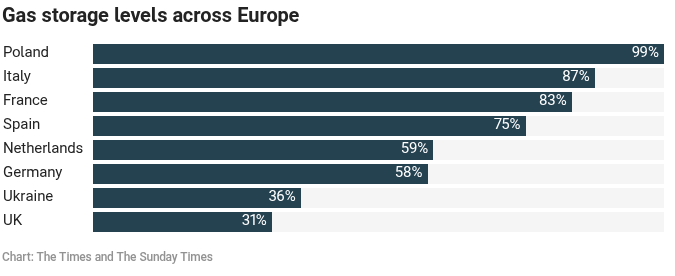
This interesting Sunday Times (UK) piece was shared by JL Daeschler. A key point in the quote below is that you can’t neglect the gas (dispatchable energy) network when you increase the contribution of intermittent renewables.
When wind and solar generation are low, the nation switches on the gas — and in a big way. Take January 5 this year, when gas-fired generation jumped from 2.3GW to 26.1GW in the space of a day — enough to power 19 million homes. The upshot is that “less gas use doesn’t mean less gas network,” as one industry source puts it.
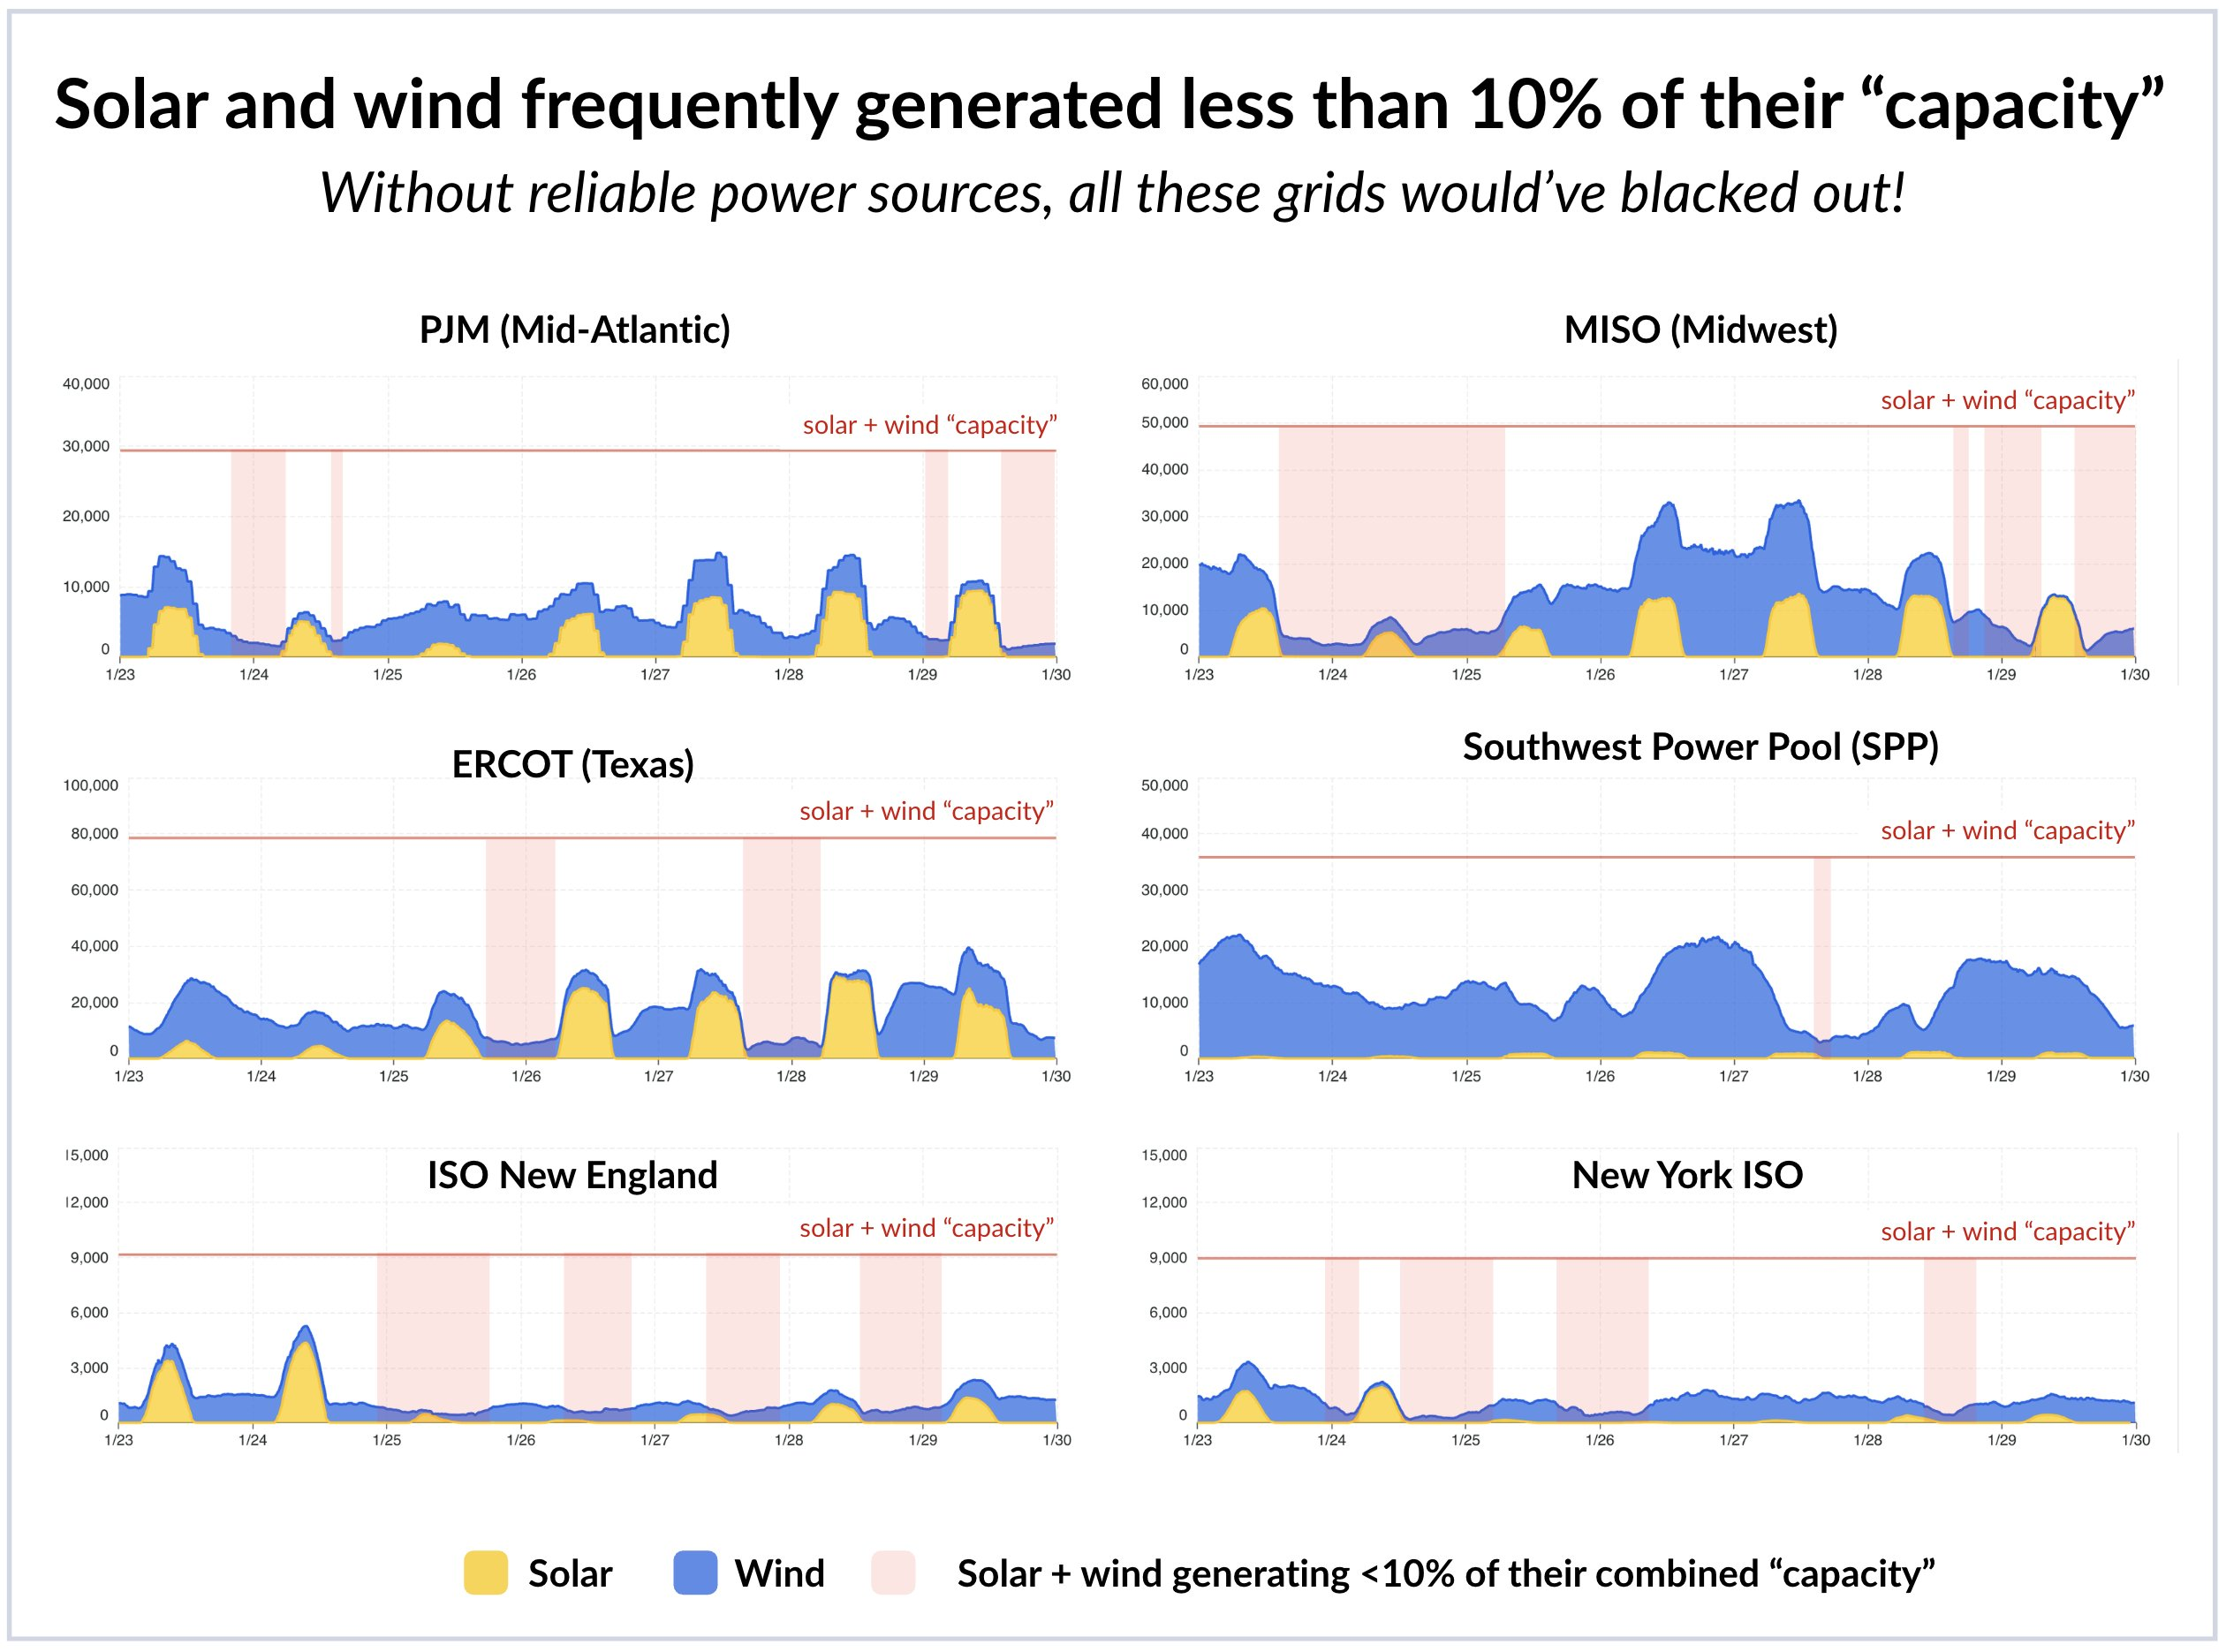
As Alex Epstein has frequently asserted “solar and wind aren’t real power sources, they’re intermittent fuel-savers.”
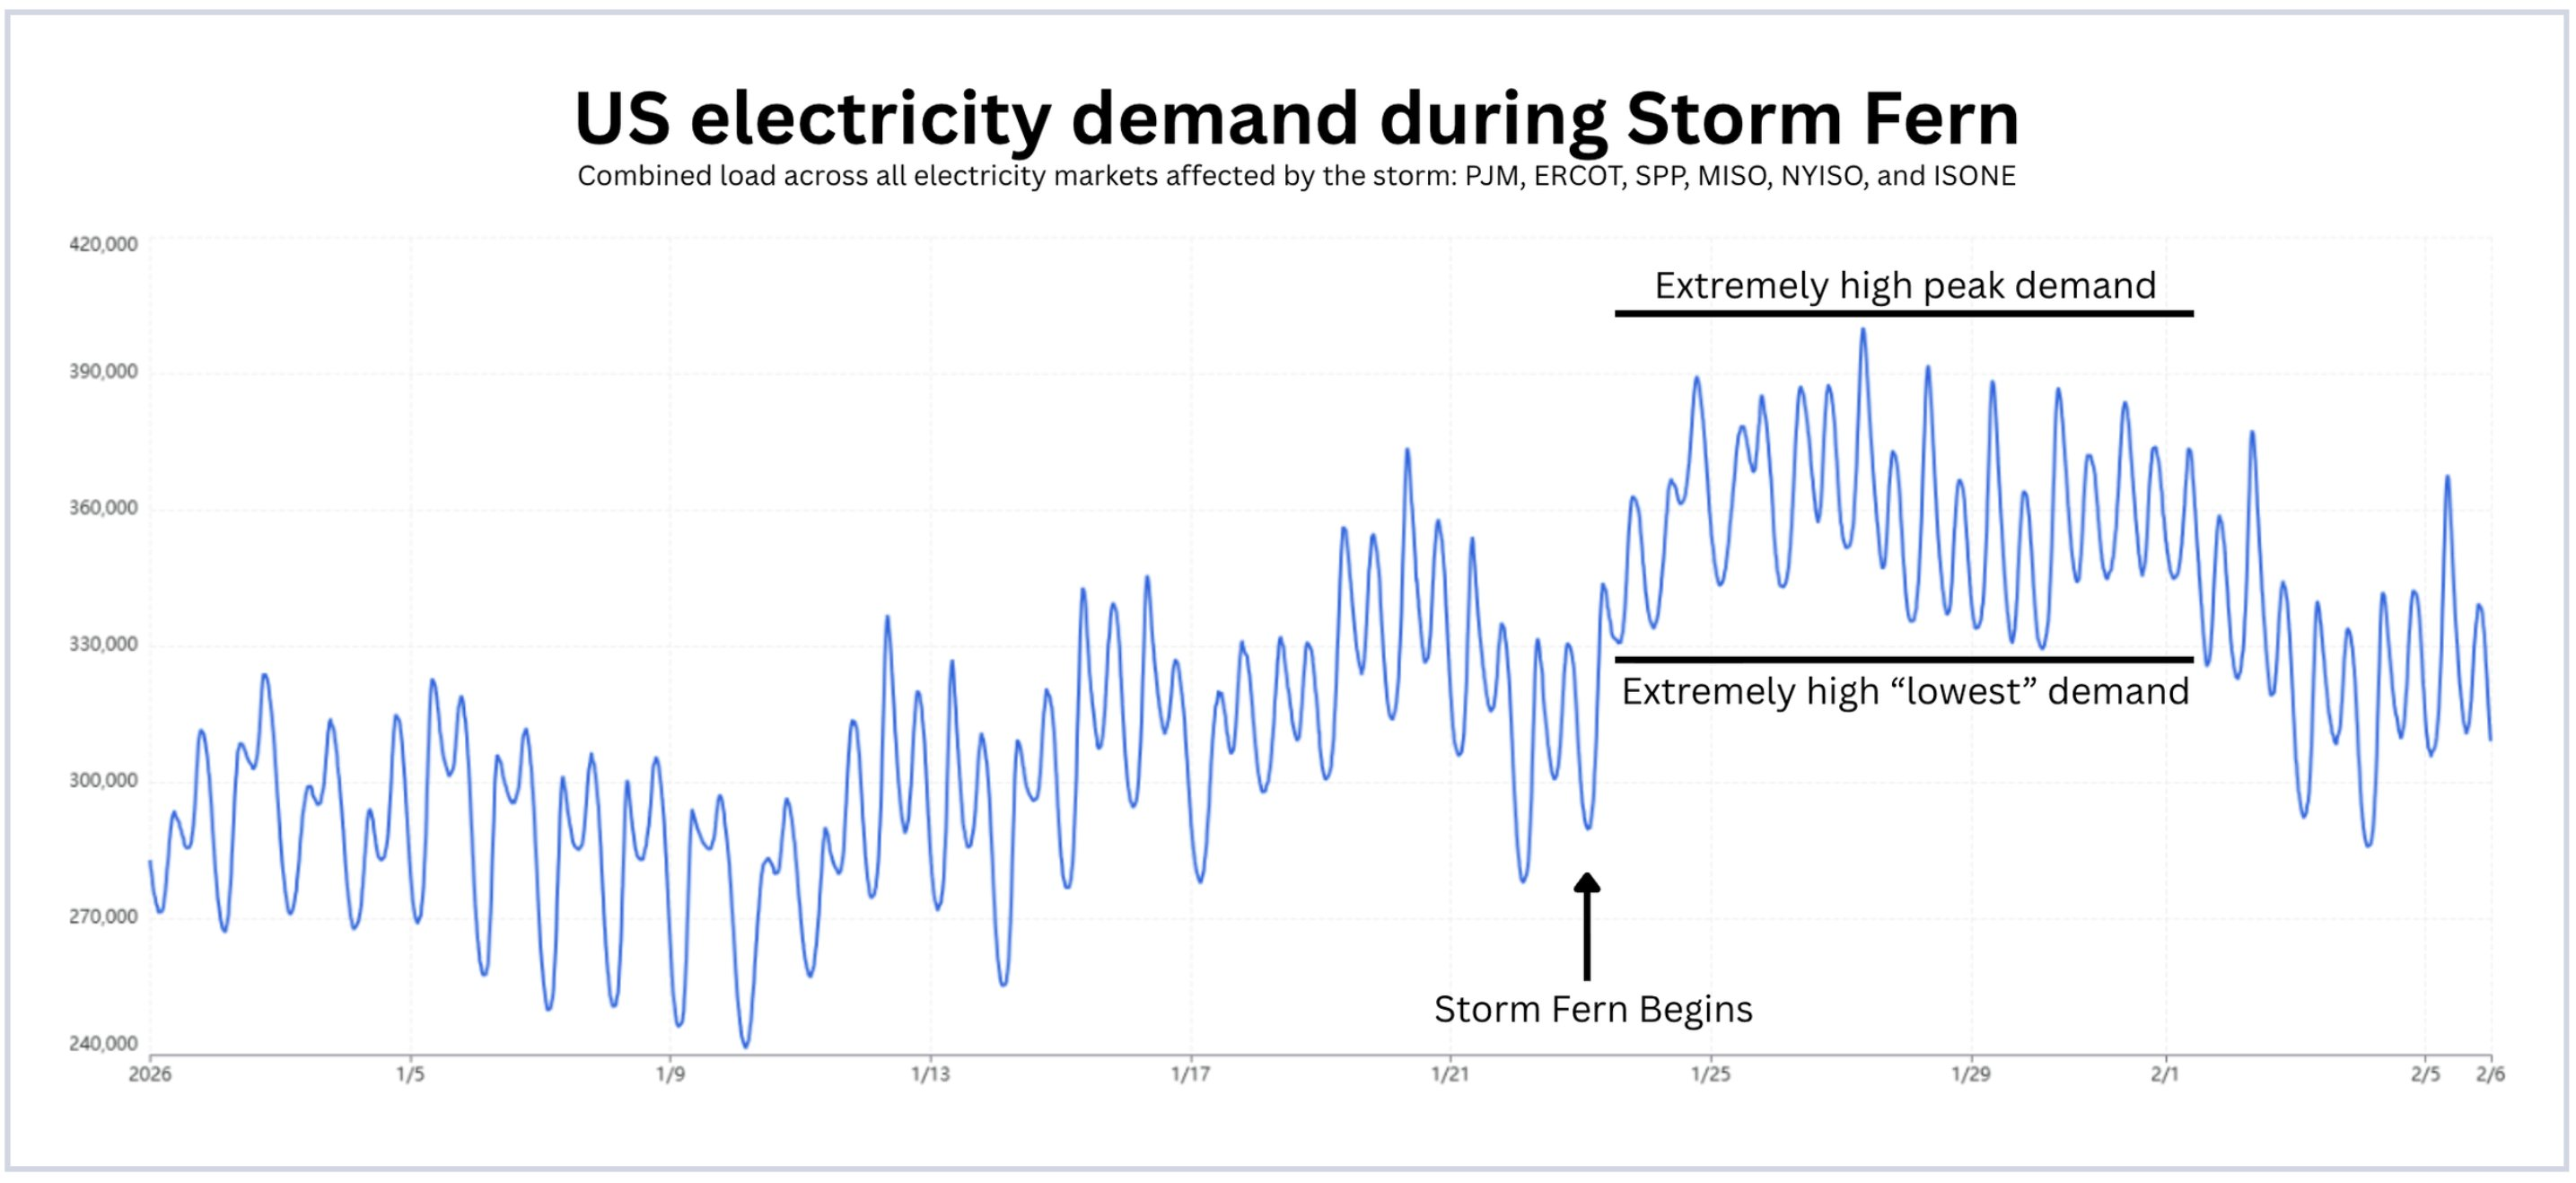
Winter Storm Fern (1/23-31/2026) affected much of the US stretching from the Southern Plains and the Gulf Coast through the Midwest, Mid-Atlantic, and New England. Power demand surged, and solar and wind power generation were minimal. (Alex Epstein charts below)
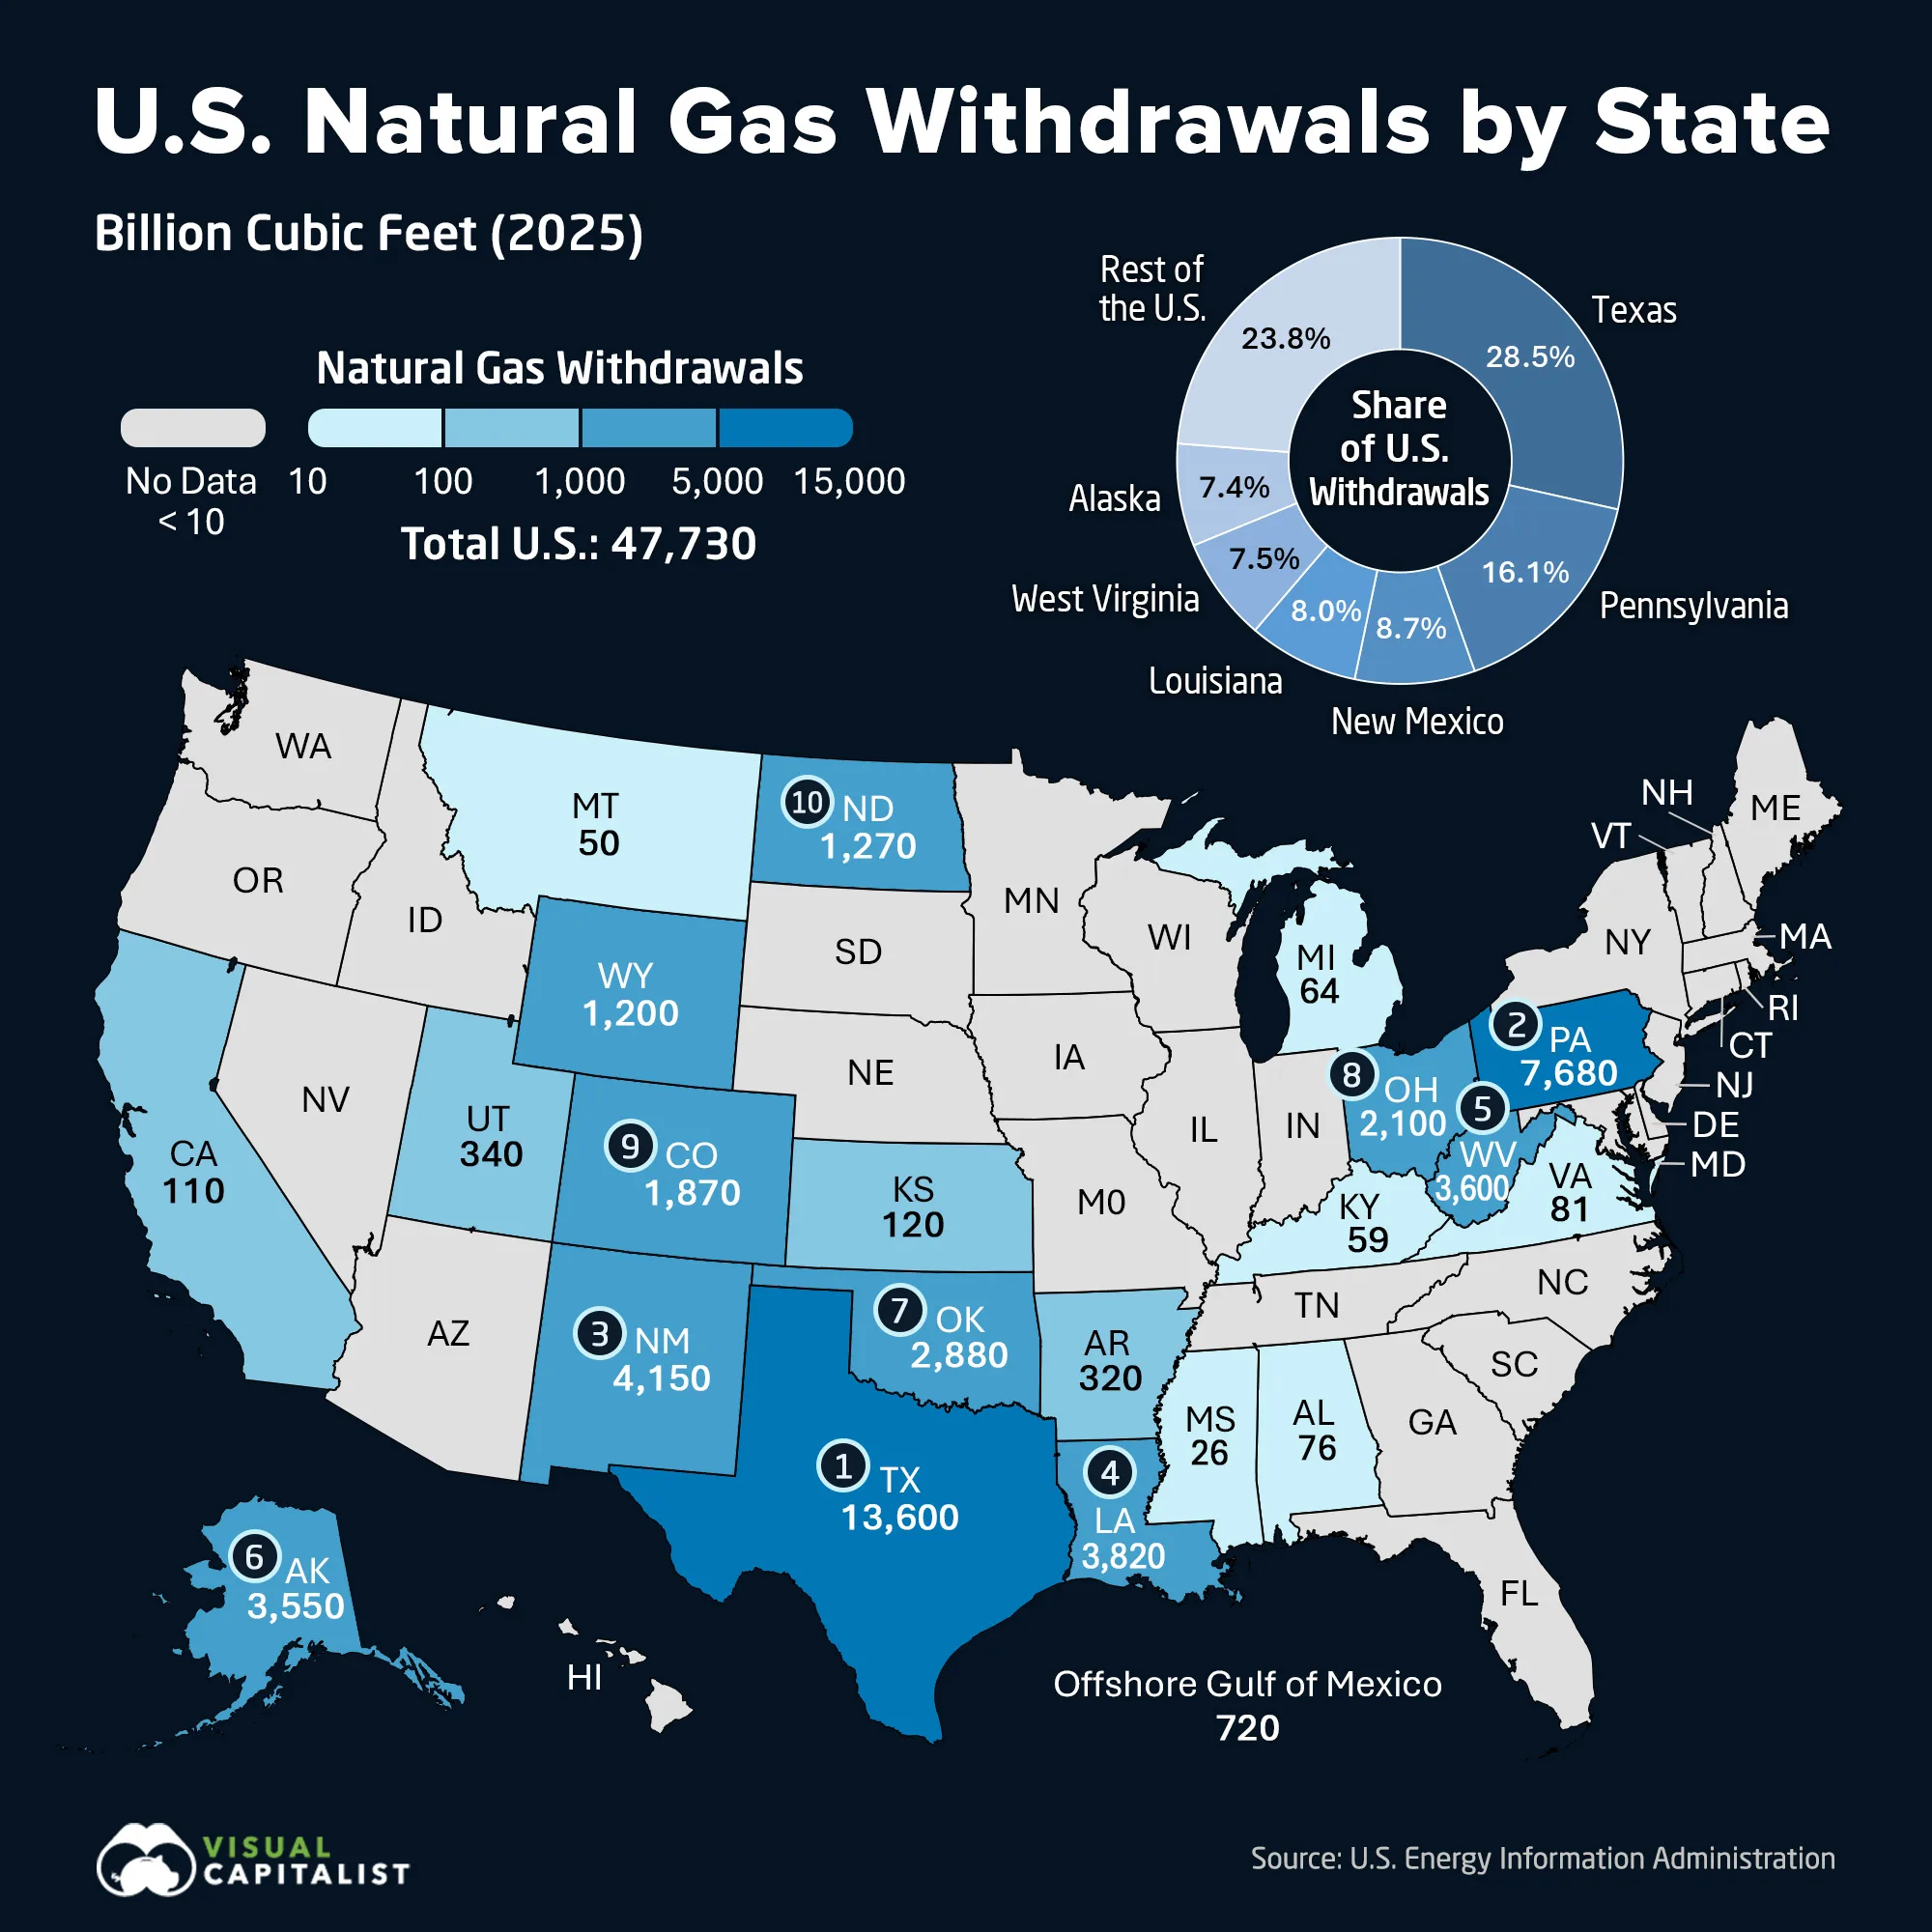
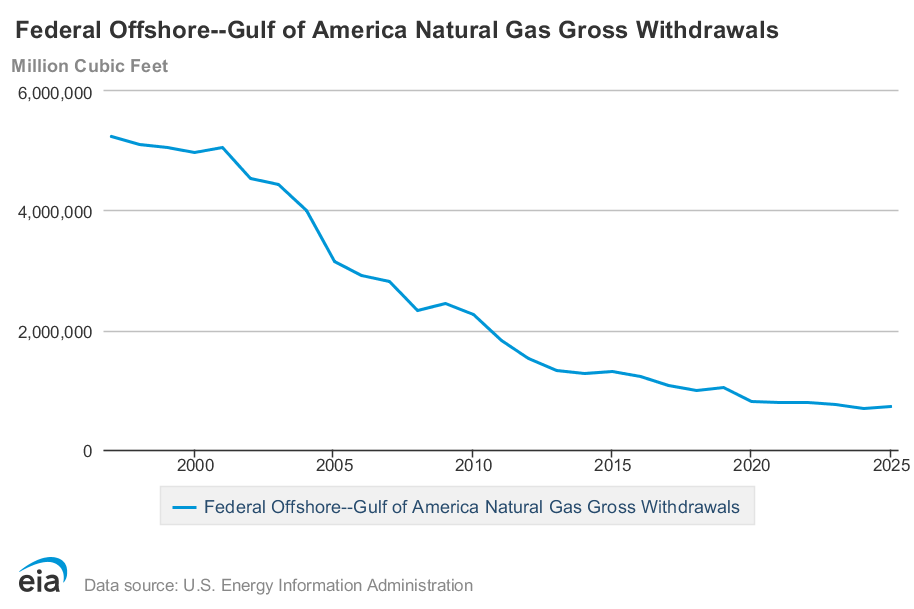
Total US gas withdrawals have doubled from 30 years ago when the Gulf accounted for >20% of the US total. Gulf production declined by 87% in that timeframe.
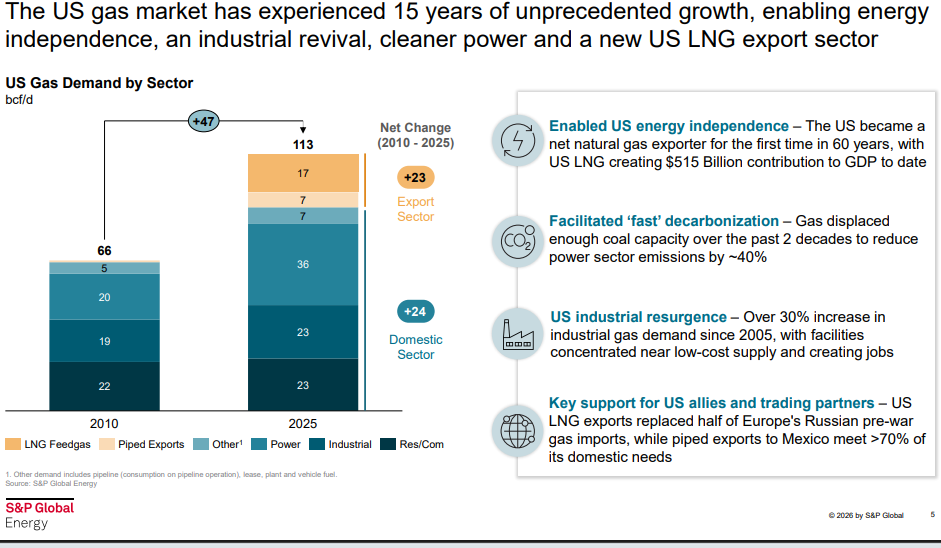
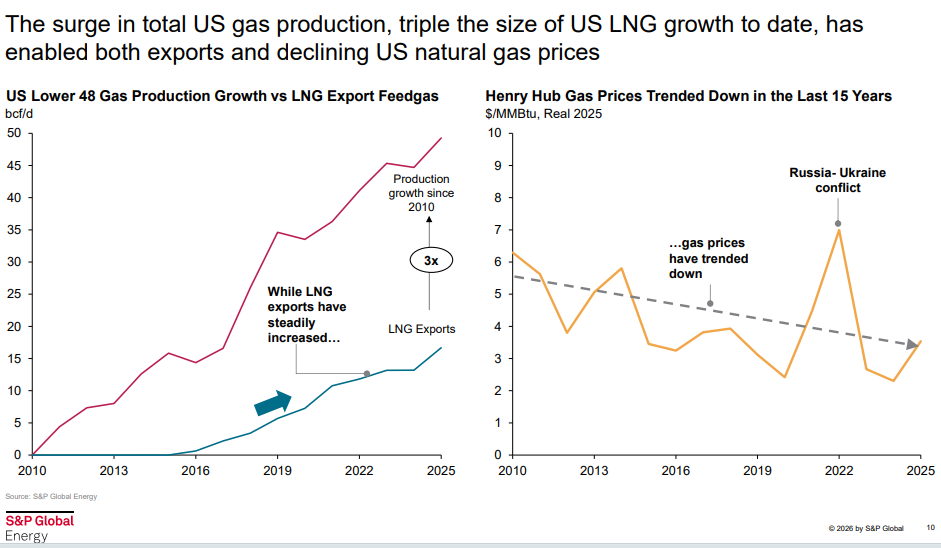
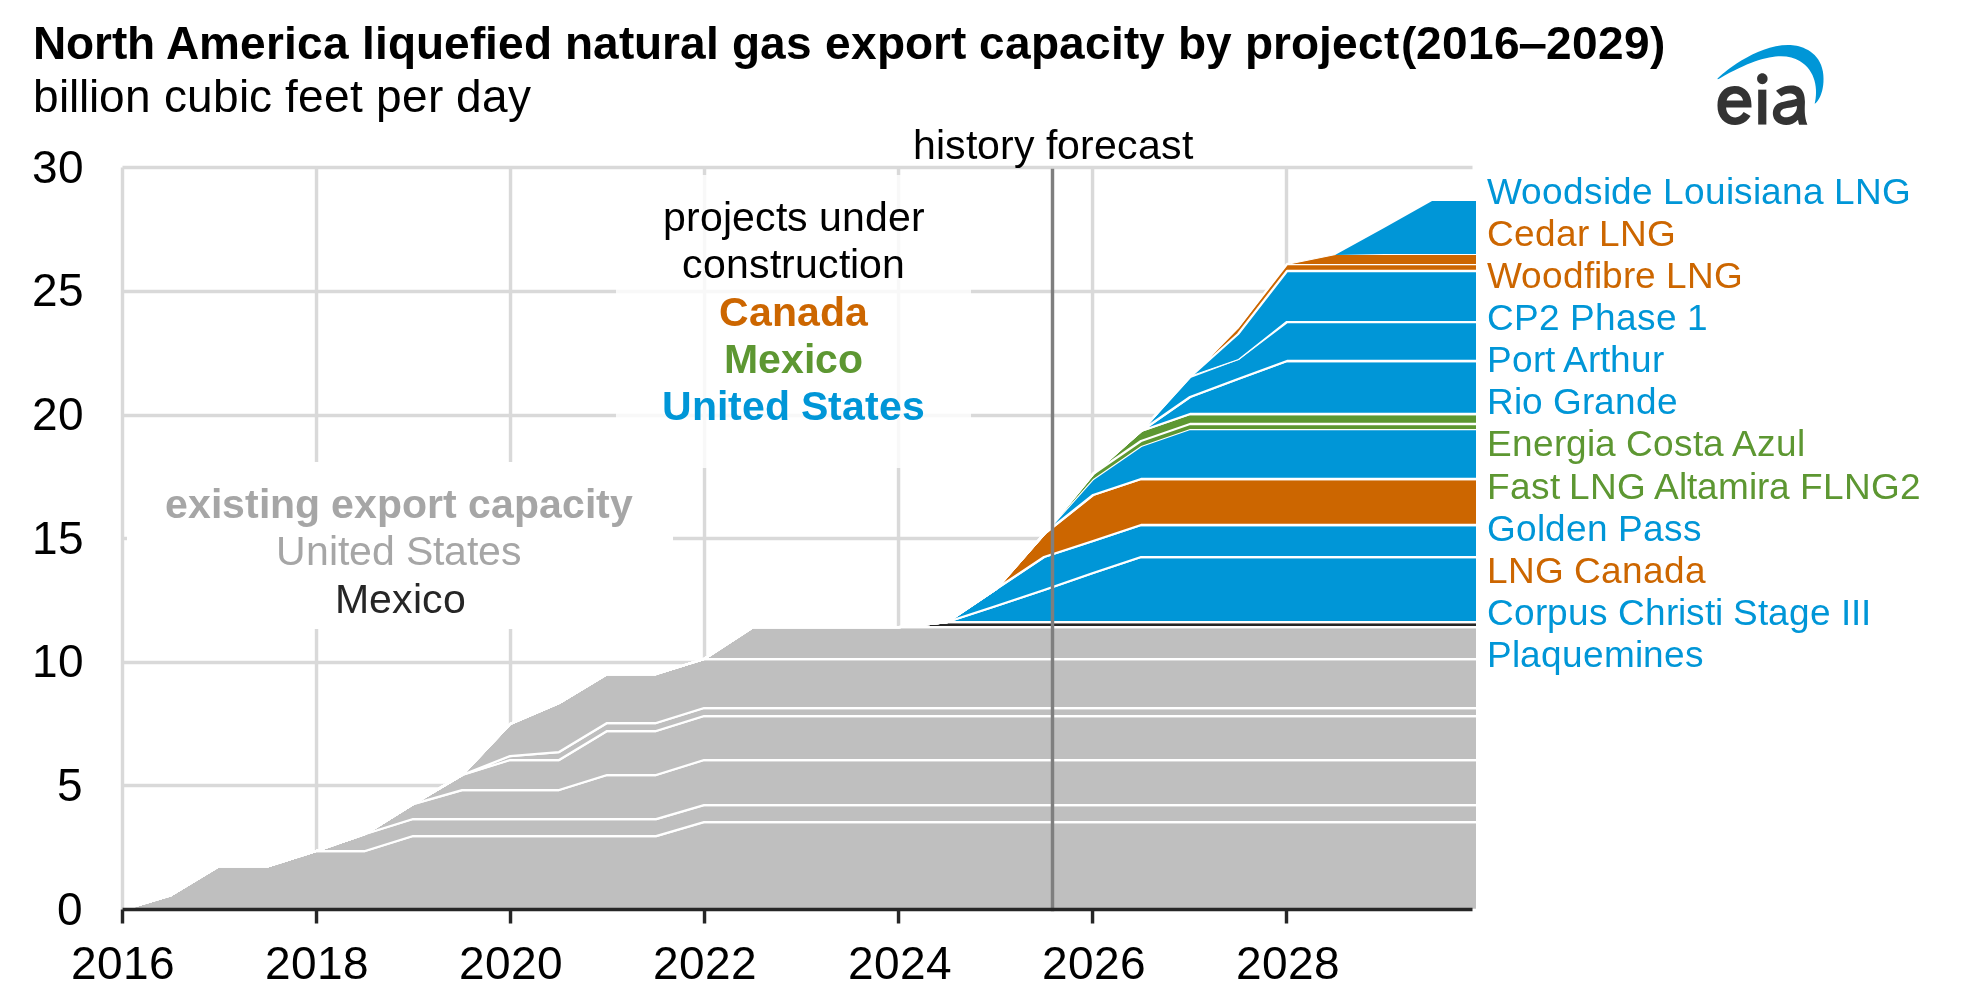
“Profound growth of LNG is exceeding all expectations,” said Daniel Yergin. “Economic gains in terms of jobs, GDP and labor income are on track to surpass all prior expectations, while the abundance of U.S. gas means that domestic prices remain among the lowest in the world.”
“More than 45 years of identified commercial gas resource in the United States at today’s production levels and the world’s most interconnected pipeline network are what enable both exports and low domestic prices,” said Eric Eyberg, Vice President, Gas and LNG, S&P Global Energy. “Since 2010, domestic prices have trended downward even as demand for U.S. gas has grown 70 percent. The recent Iran conflict has proven the U.S. domestic gas market resilient to external shocks relative to global gas and other commodities. U.S. Henry Hub gas prices declined during the conflict.”
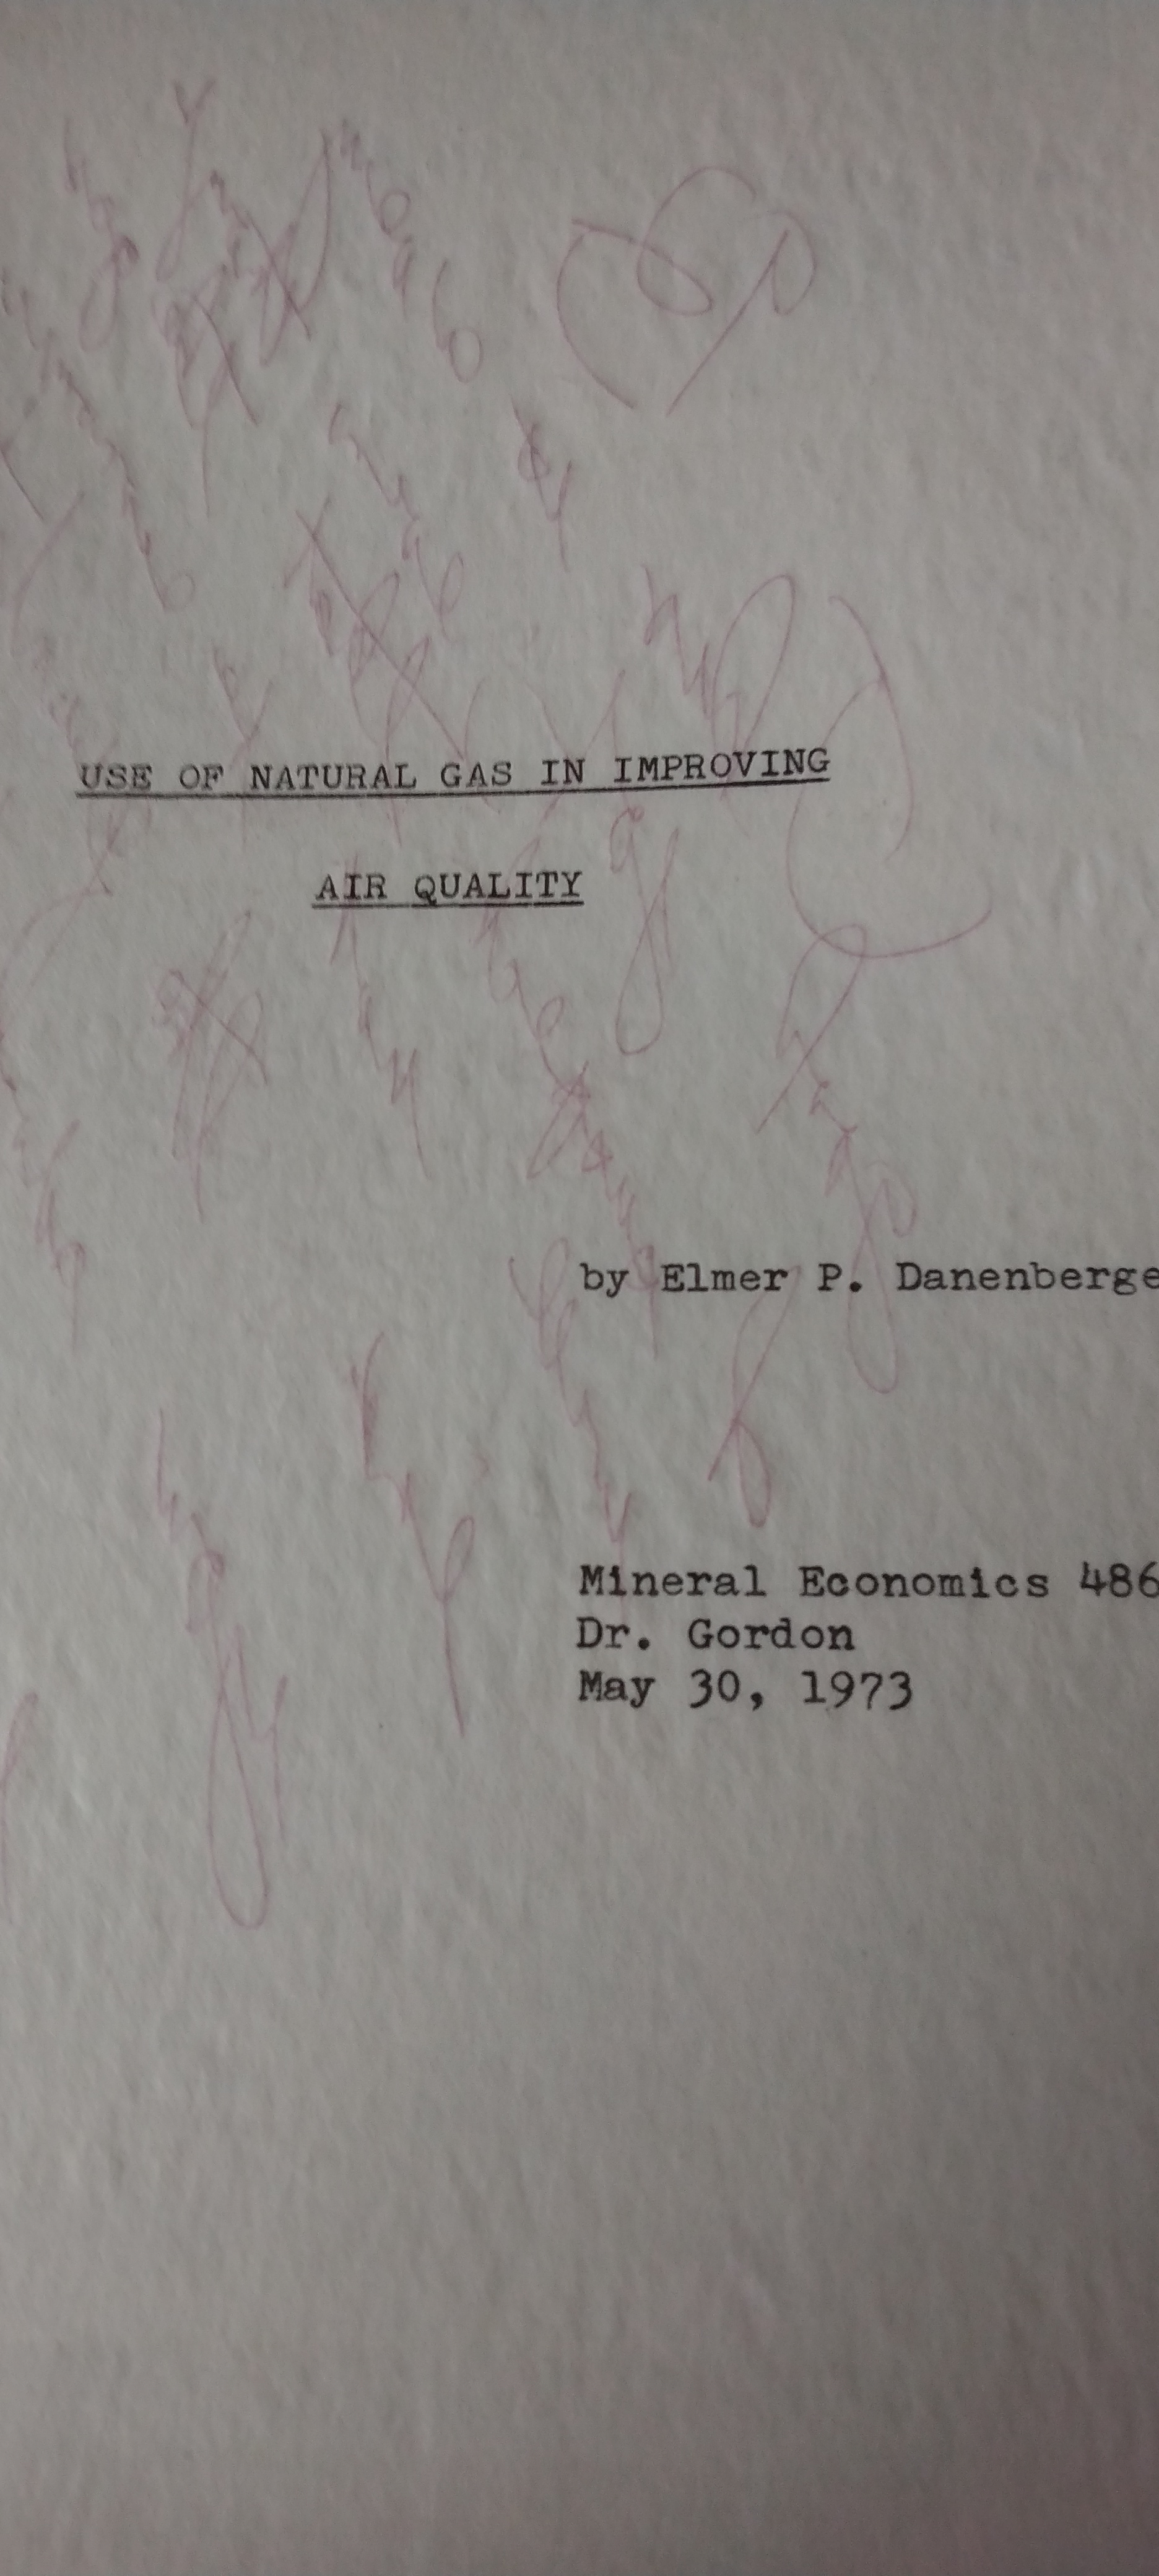
More than 50 years ago as a graduate student, I wrote a paper entitled “The Use of Natural Gas in Improving Air Quality.” My professor, Dr. Richard Gordon, a brilliant economist who greatly influenced my thinking about energy, liked the paper (grade of 93), but thought I was too optimistic about the availability of natural gas (the title page and his comment are captured below). The sense at the time was that natural gas was a premium energy source in short supply, but technical innovation unlocked massive shale gas resources and justified my optimism.
BOE has been celebrating the natural gas revolution since the blog began in 2010. Methane (CH4) is essentially a hydrogen transporter that emits far less CO2 than other fossil fuels when burned. Natural gas’s other important air quality advantages – low NOx, SO2, and particulate emissions – have far greater significance from a human health standpoint. (Many in the US and Canada learned a lot about particulates last weekend!)
The environmental case for offshore natural gas is particularly strong. However, Gulf of America gas production has struggled to compete with the onshore shale sector. Total Gulf production fell to 757 bcf in 2025. 91% of that gas production was from oil wells, primarily high rate deepwater wells.
WASHINGTON –Today, the Department of the Interior announced a settlement agreement with affiliates of Invenergy, North America’s largest privately held developer, owner, and operator of independent power infrastructure, aimed at strengthening American security and lowering costs, advancing goals central to President Donald Trump’s Energy Dominance Agenda.
As part of the settlement agreement, Invenergy will voluntarily terminate its affiliates’ four offshore wind leases located in the New York Bight, Central Coast of California and the Gulf of Maine totaling $765 million, and redirect that amount towards other domestic energy sources with the demonstrated capability to deliver reliable, affordable power, including the development of natural gas-fired power plants in Indiana, Wisconsin, Iowa, Kansas, and Missouri and geothermal power generation projects in the Western U.S.
The natural gas revolution is cause for celebration! How about a parade down Constitution Ave?😉
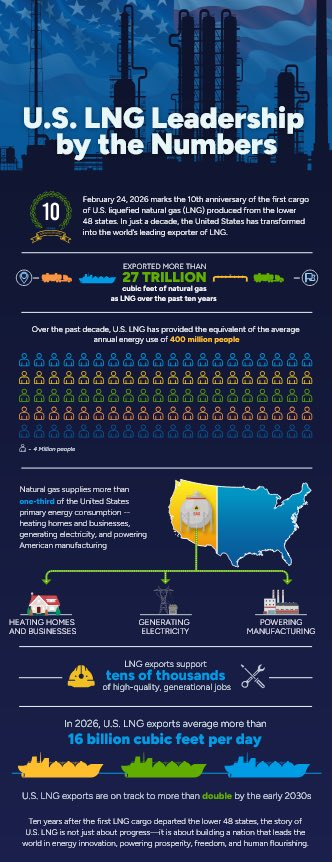
In light of the Dept. of Energy’s announcement commemorating the 10th anniversary of the first export cargo of U.S. liquefied natural gas (LNG), I’m linking a 16 year old BOE post asking why we weren’t celebrating the emerging natural gas bonanza. Keep in mind that 20 years ago we were planning for LNG import facilities in the Gulf!
Quote from DOE about the transformation of the US into the world’s leading LNG exporter:
“This transformation was made possible by the Shale Revolution, an era of breakthrough technologies including horizontal drilling and hydraulic fracturing that unlocked vast domestic oil and natural gas resources.”
The “Natural Gas Revolution” (Yergin) is an important part of our history that deserves national attention.
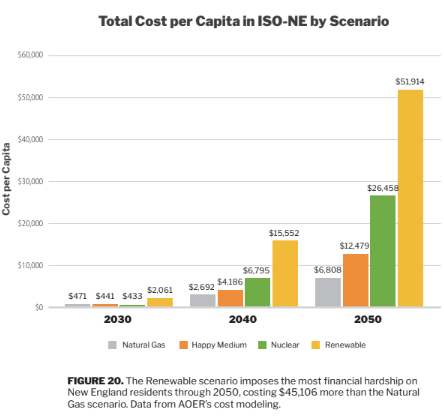
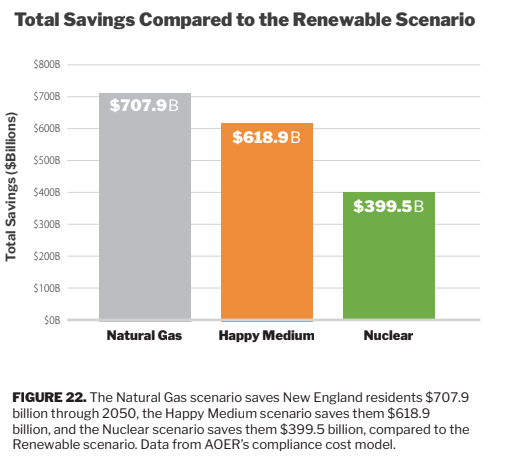
The Always On Energy Research report is attached. Conclusion:
“In other words, dispatchable generation saves New England hundreds of billions of dollars and avoids blackouts. In the end, the idea that New England can run its electric grid on wind turbines, solar panels, and batteries is a dangerous and unserious proposition.“
“Natural gas and LNG are fast becoming the gravitational center of the global energy system, but some energy experts said the world is only beginning to grasp the scale of what’s to come.” ~Natural Gas Intelligence
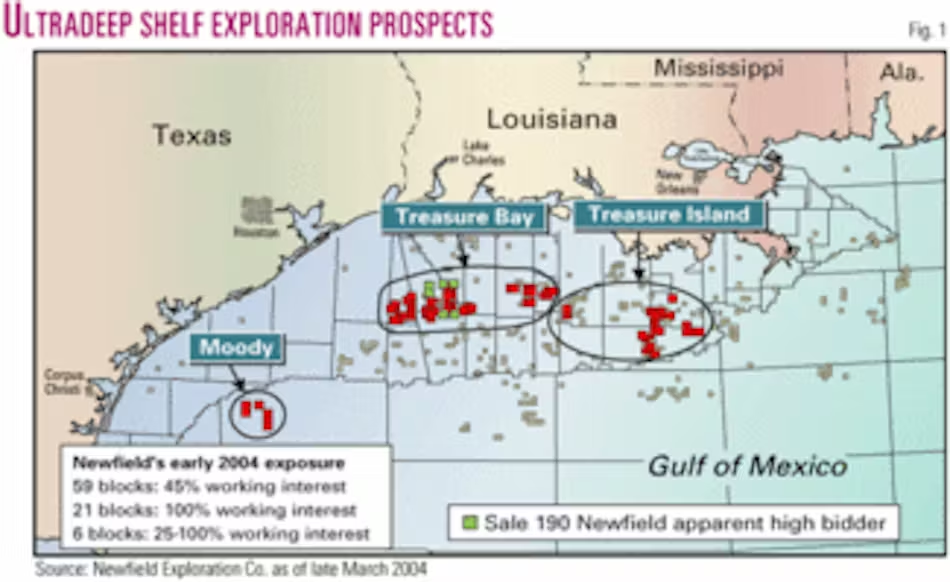
Demand and high well producibility are stimulating exploration in the high pressure, high temperature Western Haynesville (Texas) and other ultradeep onshore gas prospects. Is it time to revisit ultradeep gas on the Gulf of America shelf? See the above targets map from 2004.
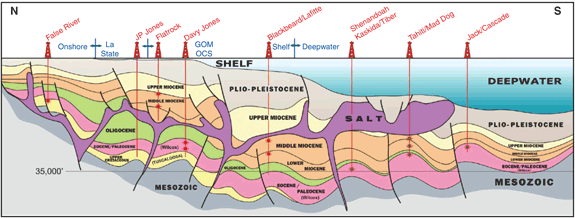
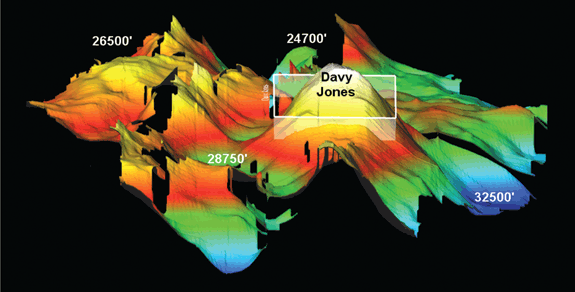
20 years ago Newfield, Exxon, and McMoRan drilled pioneering ultradeep wells targeting gas-prone reservoirs below salt welds in Miocene and older formations (diagrams below). The water depths were <100 feet but well depths exceeding 30,000 feet, and high temperatures and pressures, pushed the limits of drilling technology at the time. Noteworthy wells:
Blackbeard West (Exxon): Spudded in early 2005 in 70 feet of water in South Timbalier Block 168. The target was gas in Miocene sands at 27,000-32,000 feet total depth. Drilling reached 30,067 feet by 2006, but was prudently suspended due to extreme pressures, temperatures (up to 600°F), and technical challenges with equipment.
Blackbeard West, part 2: In 2008, McMoRan re-entered the well with upgraded equipment and drilled to a record 32,997 feet below the mudline. They encountered hydrocarbon shows in multiple zones, including potential gas pay in Middle and Deep Miocene sands below 30,000 feet, validating the ultradeep concept.
Followup McMorRan wells:
Blackbeard East (2010-2011): Drilled to 33,400 feet in South Timbalier Block 144, logged potential hydrocarbons in Sparta and Vicksburg sands.
Davy Jones (2009-2010): South Marsh Island Block 230 in 20 feet of water; reached 29,122 feet; discovered gas in Wilcox sands, but faced flow-testing challenges.
Lafitte (2011): Eugene Island Block 223, found additional pay in ultradeep Miocene zones. These wells targeted gas reservoirs but encountered operational hurdles.
Also, note that a company targeting hydrocarbons below 25,000 feet (true vertical depth subsurface) may earn an additional 3 years on their lease. (See the Notice for next week’s lease sale.) Will improved technology and demand expectations finally open the ultradeep gas frontier?
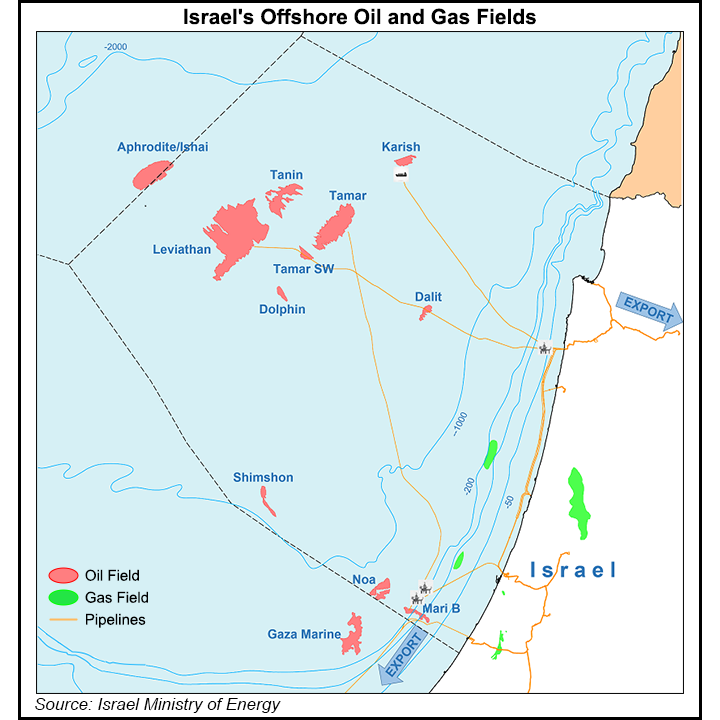
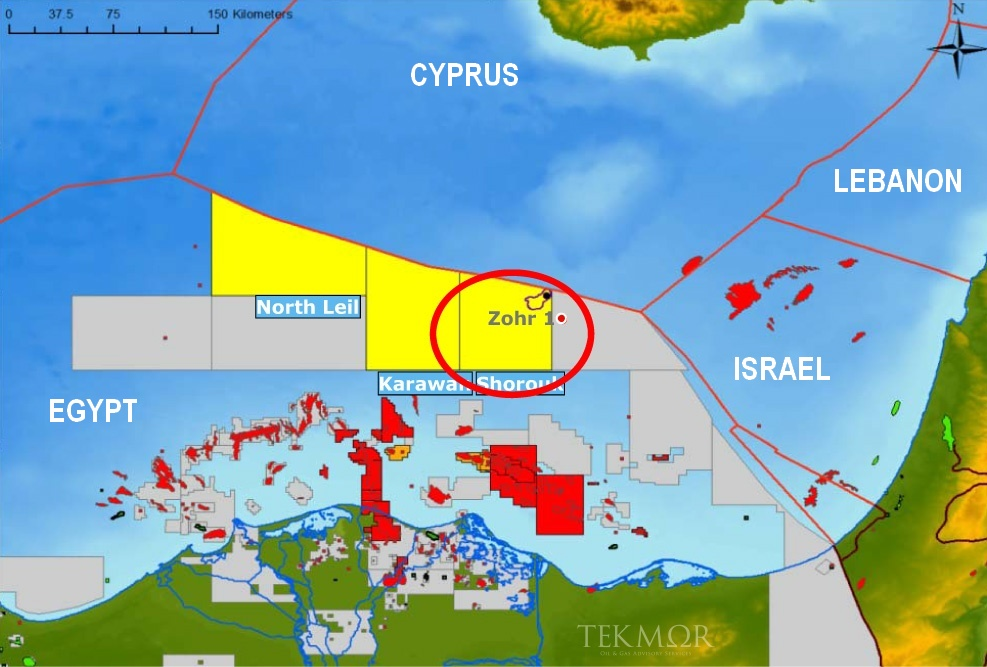
In light of the fantastic Middle East news, planning for the redevelopment of Gaza is underway. The Gaza Marine Gas Field should be a high priority given the power generation and revenue potential.
The field, which was discovered in 1999 by British Gas (now part of Shell), is located approximately 30-36 km off the coast of Gaza in the eastern Mediterranean and has estimated natural gas reserves of ~ 1 Tcf.
Who should be licensed to develop the field? In June 2023, there was a proposed agreement between the Palestinian Authority and an Egyptian consortium led by state-owned Egyptian Natural Gas Holding Company (EGAS). A resurrection of this arrangement may align with Palestinian interests. EGAS has experience in Mediterranean gas projects including the giant Zohr field (see map below).
Other candidates for developing the Gaza Marine field (pure speculation):
Chevron would be a logical choice given their extensive eastern Mediterranean experience as a result of their acquisition of Noble Energy. However, there might be concerns about undue US and Israeli control of this important resource.
Regional giants like Saudi Aramco, Qatar Energy, and Abu Dhabi National Oil Company (ADNOC) would be good candidates.
Another interesting possibility might be Equinor, which is 2/3 owned by the Norwegian govt. Equinor seems to sometimes make socially desirable investments that are less profitable.
Some combination of the above companies might also be a possibility. In any event, it’s critical to manage this resource in a manner that best benefits the recovery effort.
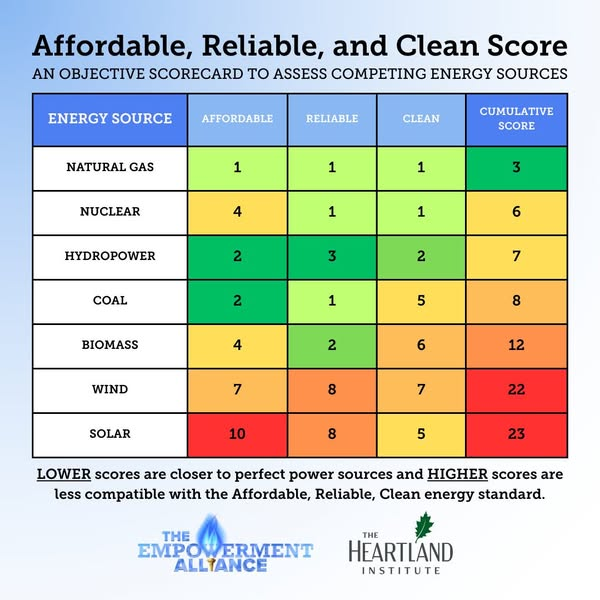
Although combustion of natural gas emits 30% and 45% less CO2 than oil and coal respectively, the CO2 emissions are still significant. As a result, those who focus solely on greenhouse gases and ignore all other impacts (e.g. other air pollutants like NOx, SO2, and particulates, land use and space preemption, visual effects, and wildlife risks), want to limit the production and use of gas. However, whether or not fossil fuel consumption is significantly affecting the climate, the use for natural gas will be economically and environmentally imperative for the foreseeable future.
Not all natural gas production is equal from an environmental standpoint. Because this is an offshore energy blog, I draw your attention to the unique advantages of offshore gas production: minimal visual impact, bird friendly (rigs-to-roosts!), no risks to freshwater aquifers, and few land use issues.
Currently, most offshore gas production is in the form of oil-well gas (AKA associated or casing head gas). Offshore gas production is thus being primarily driven by oil demand, and is an added benefit from deepwater oil development.
Offshore gas-well or non-associated gas is largely the domain of independent operators producing in the shallower waters of the continental shelf. Non-associated gas has an added benefit in that there is little or no spill risk (depending on how dry the gas is). Shelf gas platforms also provide ecosystem benefits through their reef effect (rigs-to-reefs). Sustaining this non-associated gas production is therefore desirable from both energy and environmental standpoints.