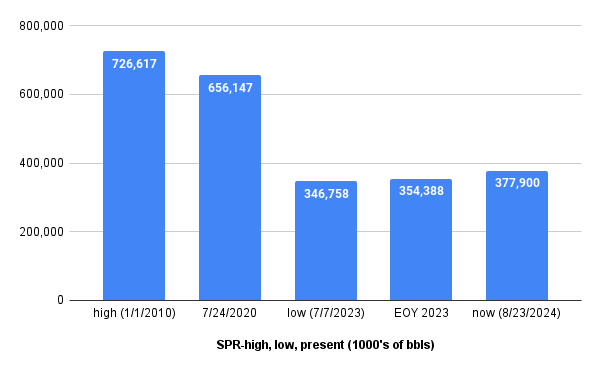
Given the relatively moderate oil prices during much of 2024, DOE has made some progress in adding to the Strategic Petroleum Reserve. However, the 31 million bbls added since July 2023 only amount to about 10% of the reserves withdrawn during the 3 years prior (July 2020 to July 2023) and about 4% of the SPR’s capacity.
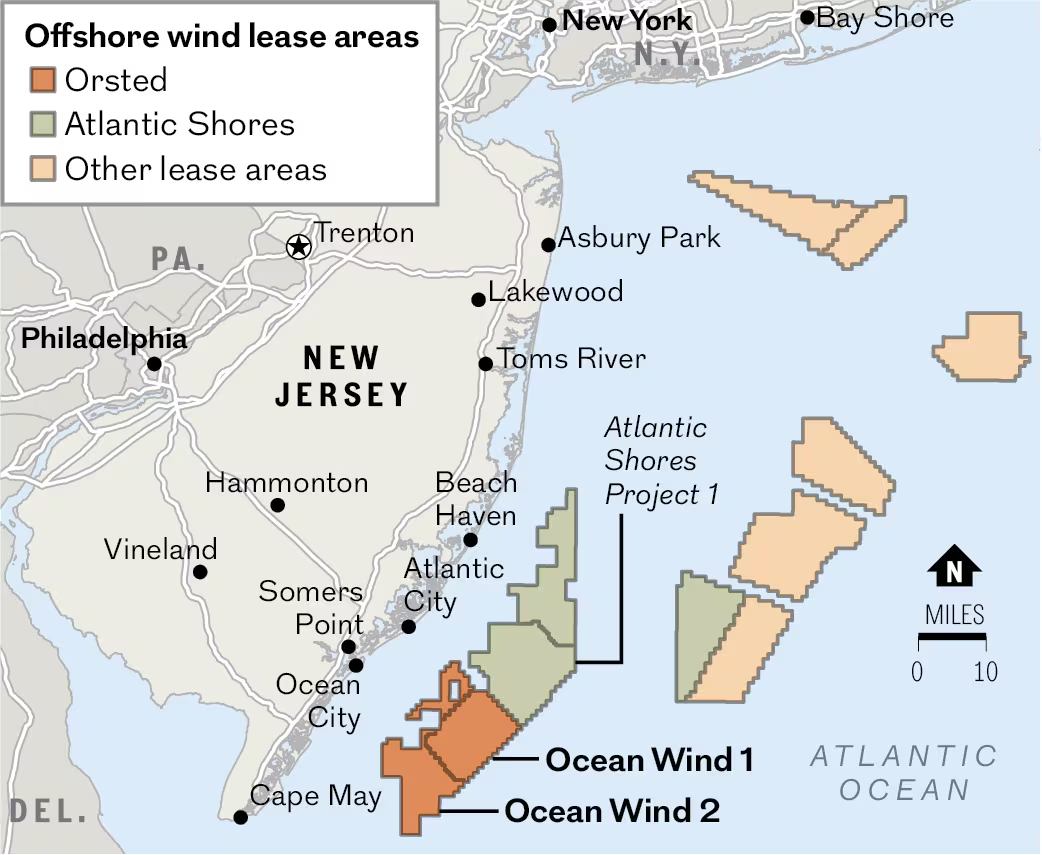
10/31/2023: Citing economic factors, Orsted announces they “will cease development of the Ocean Wind 1 and Ocean Wind 2 projects.” (This should have resulted in termination of the leases.)
1/19/2024: Orsted requests a 2 year “suspension of operations” to extend the leases they had ceased developing. (Presumably, this was a hedge with hopes of marketing the leases or getting better terms.)
2/29/2024: True to form, BOEM approves the questionable 2 year suspension request. The approval letter was dated one day before the leases’ 8th anniversary when they would have presumably expired. (This is unconfirmed because the lease document and BOEM’s wind regulations lack clarity regarding lease expiration.)
BOEM’s approval letter (attached) curiously asserts that “suspension of the operations term is necessary for the Lessee’s full enjoyment of the lease in this circumstance to ensure sufficient time for project operations in support of the Project’s economic viability.” (Interesting wording that expresses the accommodative and promotional philosophy of the Federal wind program.)
8/14/2024: Cape May County comments that they are likely to amend their Federal Court filings “since the actions of the NJBPU would appear to have nullified Orsted’s federal permits.”
8/27/2024: Despite the fact that Orsted has ceased development and New Jersey has vacated its approvals, the Federal leases are still active.
Good luck keeping an oil and gas lease if you cease development and request a suspension of operations. BSEE will rightfully deny your request.
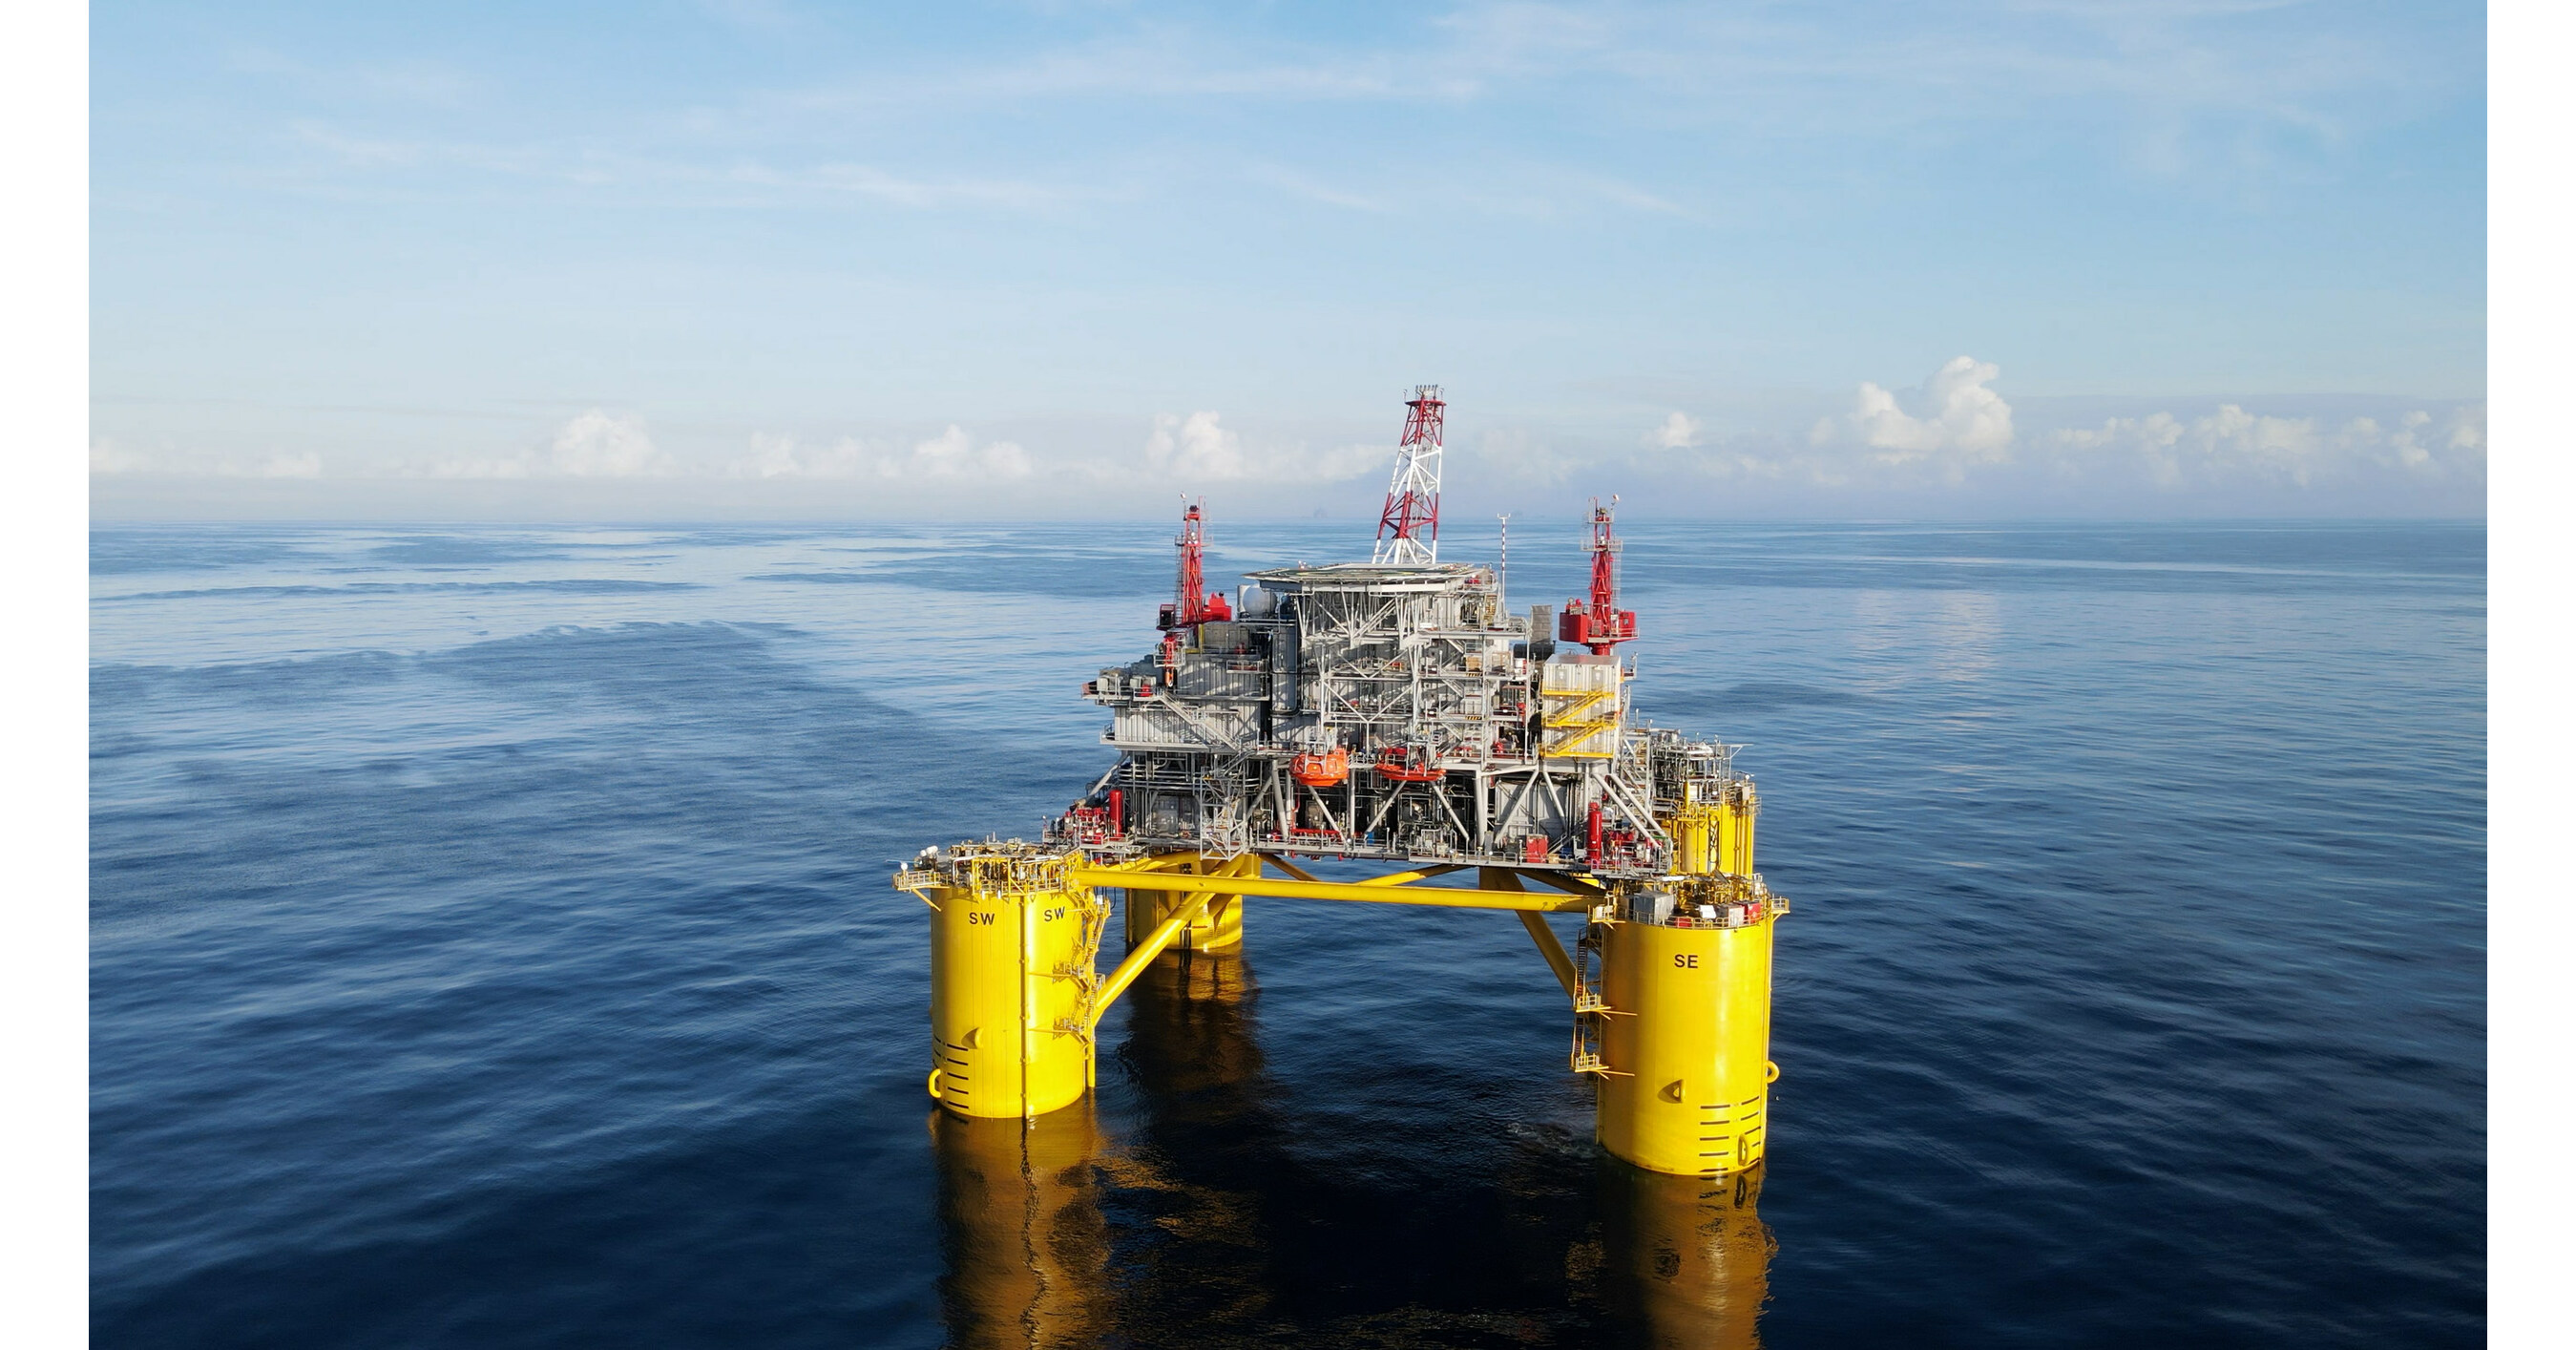
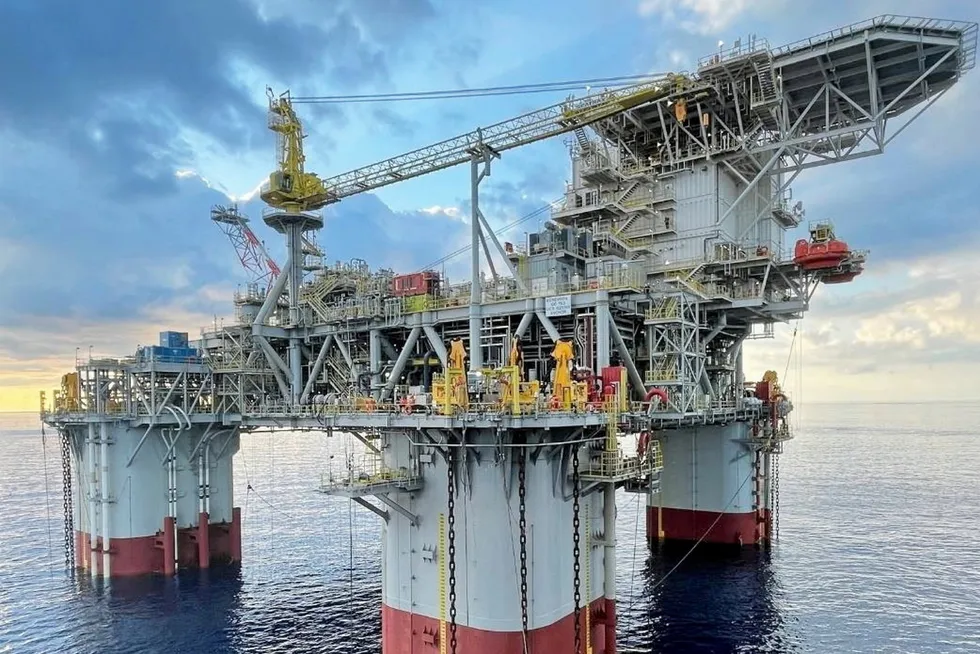
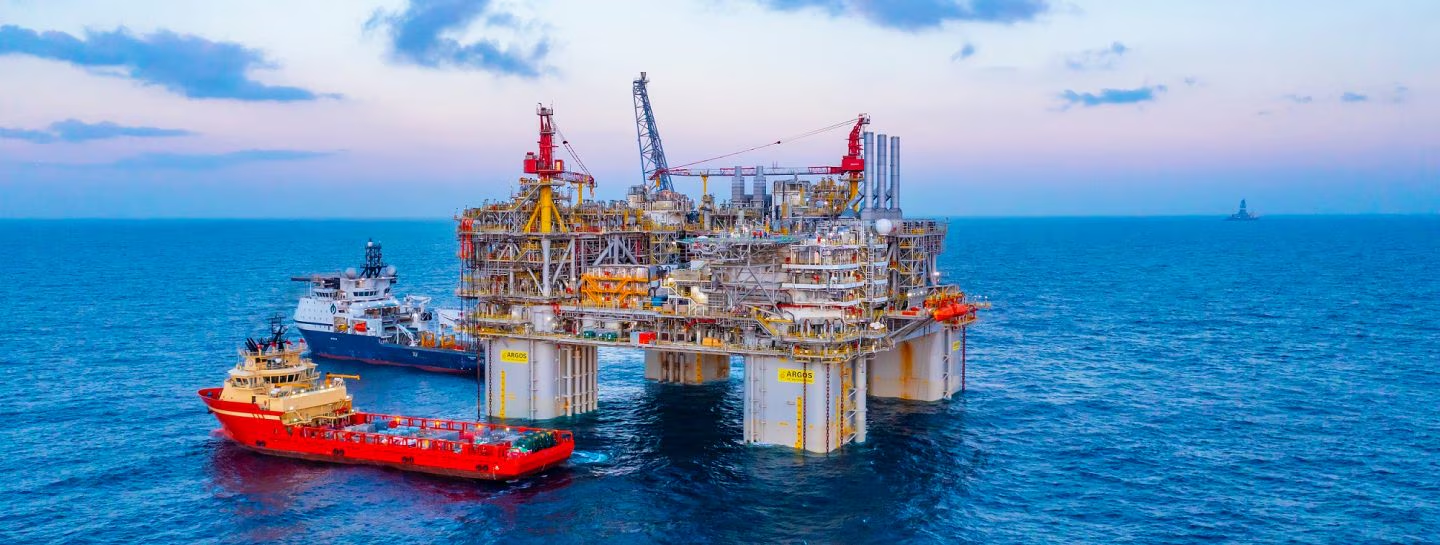
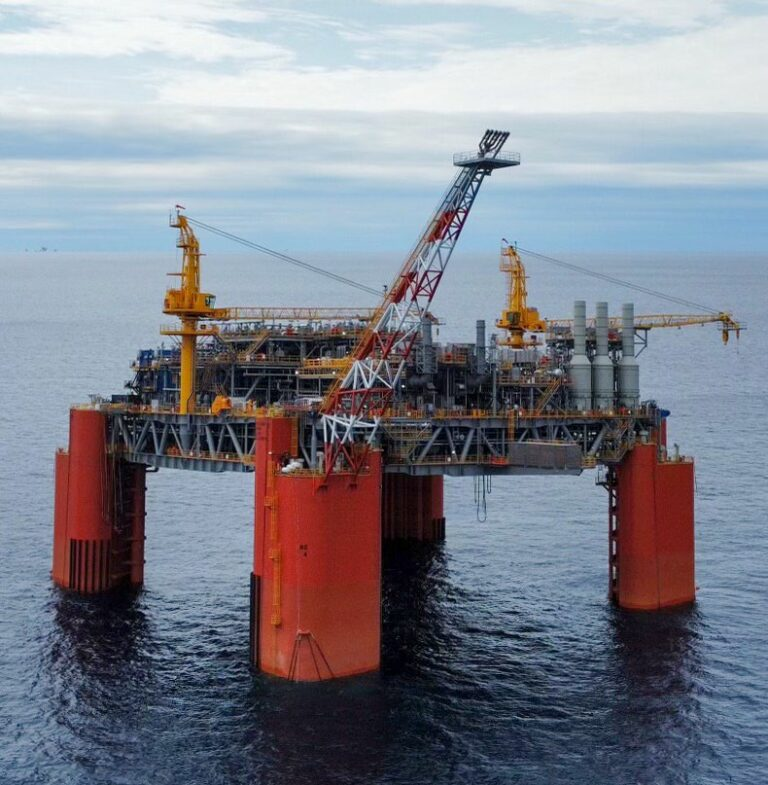
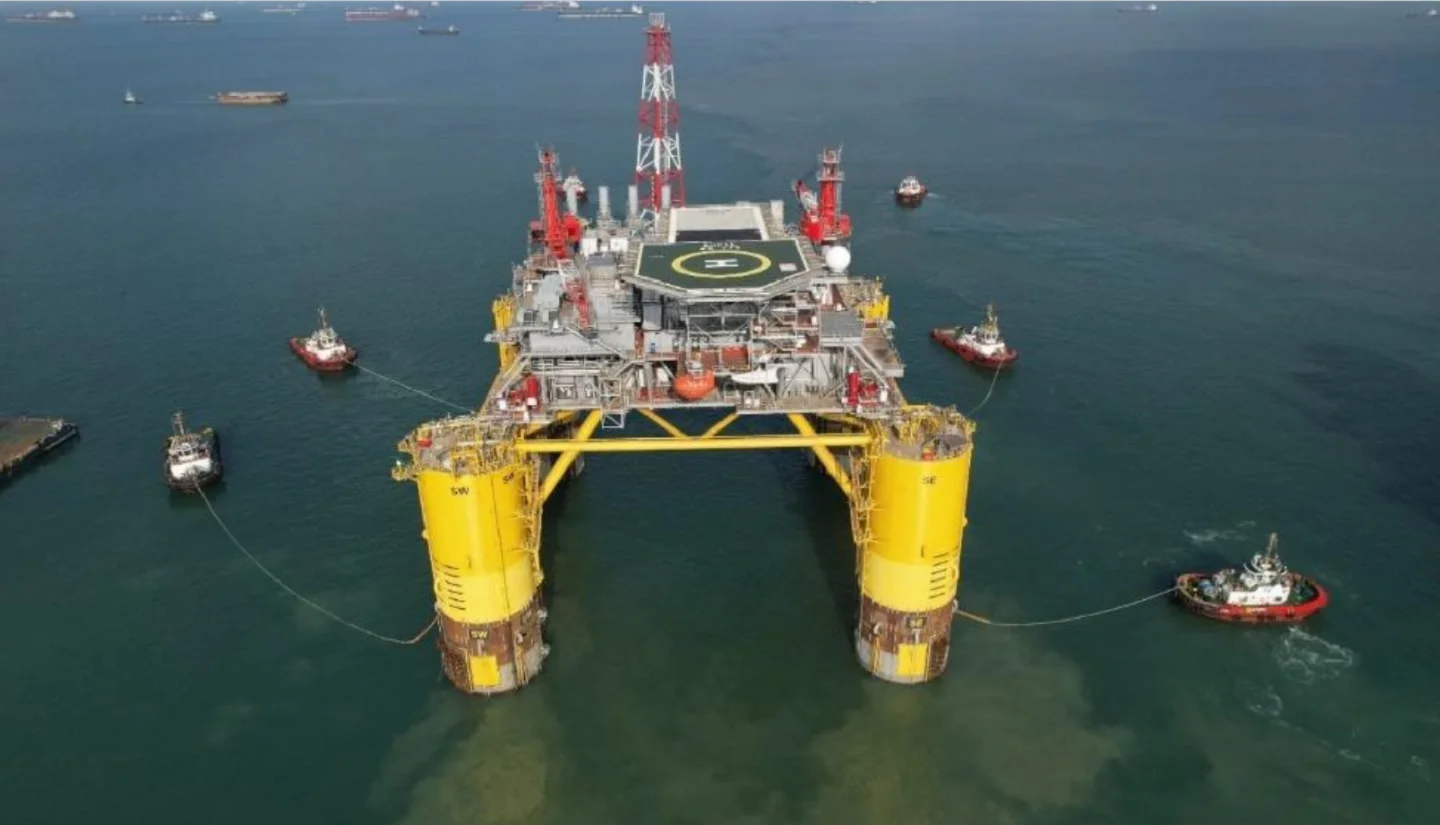
Four of the five simpler, safer, greener deepwater platforms featured on this blog are now producing. The 5th platform (Whale) is on location and scheduled to begin production later this year.
platform
operator
first production
King’s Quay
Murphy
April 2022
Vito
Shell
Feb 2023
Argos
bp
April 2023
Anchor
Chevron
Aug 2024
Whale
Shell
late 2024
These platforms are in 4000 to 8600′ of water, are expected to reach peak production rates of 100-150,000 boe/day, and have favorable emissions characteristics on a per barrel basis.
This is all good, but what is next? Will technological advances once again sustain GoM production? The short answer appears to be yes!
The efficiencies achieved with the simpler platform designs combined with the high pressure (>15,000 psi) technology developed over the past 2 decades will facilitate production from the highly prospective Paleogene (Wilcox) deepwater fans. (For those interested in learning more about the geology, see the excellent presentation by Dr. Mike Sweet, Univ. of Texas, that is embedded below.)
Chevron’s Anchor is the first deepwater, high-pressure development. Three similar deepwater hub platforms (table below) will begin production over the next 5 years. These host platforms will also facilitate additional production from nearby fields. Each will have production capacities of approximately 100,000 boe/day. Note the long lead times in achieving first production given the technological issues that had to be evaluated and addressed.
platform
operator
discovery date
first production
Kaskida
bp
2006
2029
Sparta
Shell
2012
2028
Shenandoah
Beacon
2009
2025
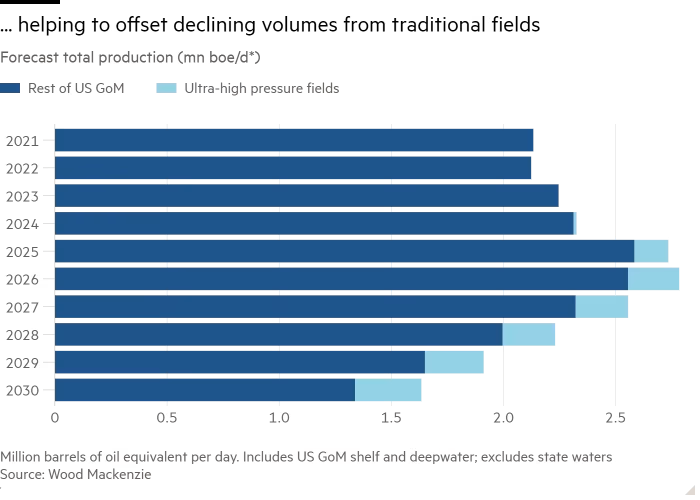
Wood Mackenzie sees these high pressure projects as the key to sustaining GoM production rates. Their projections for 2024 and 2025 seem optimistic based on 2024 YTD data, which adds to the importance of the projected new production.
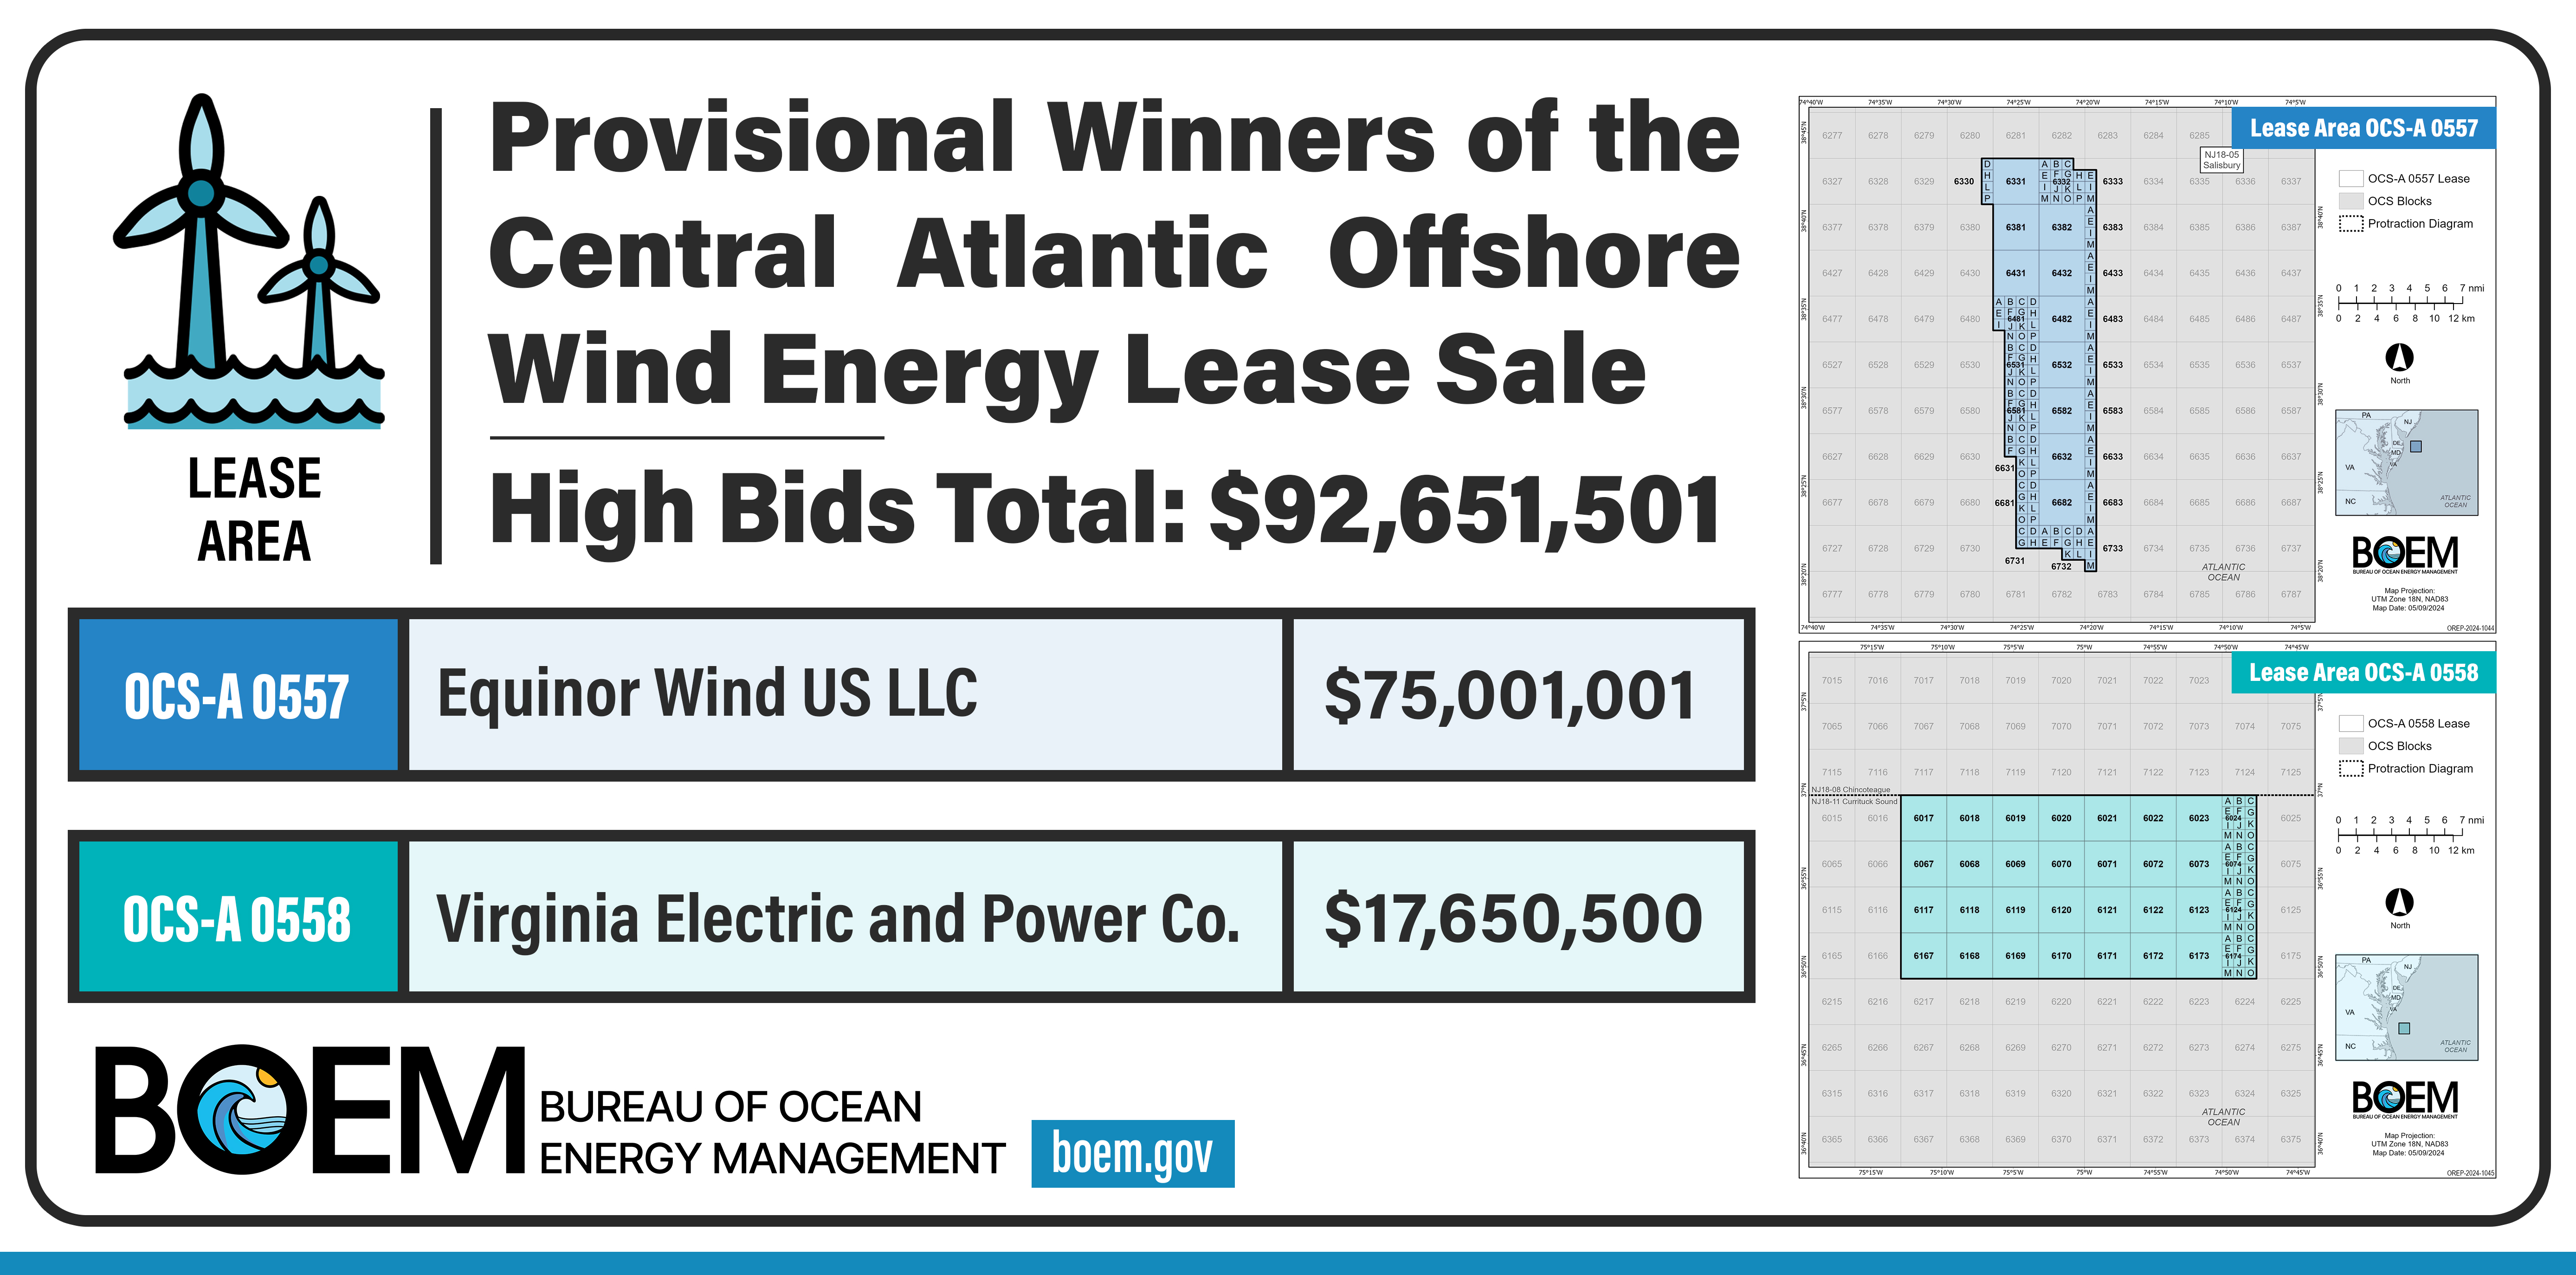
In the wake of last week’s lackluster Atlantic wind lease auction (summarized above), an excellent Renewable Energy World article documents the sharp decline in participation and bidding since the massive February 2022 sale of 6 leases offshore NY and NJ. That sale garnered bids ranging from $285 million to an astounding $1.1 billion, with total high bids of $4.37 billion! The sale was touted as the “nation’s highest grossing competitive energy lease sale in history.” The extravagant bidding, which made little sense then, seems downright irrational now.
Even the December 2022 California offshore lease sale, where development will be dependent on more expensive floating turbines, attracted substantially higher bids for leases (5) smaller than those auctioned last week.
The highly promoted Gulf of Mexico wind auctions were busts with the first sale receiving only one bid for $6.5 million and the second being cancelled due to lack of interest.
Major oil companies like bp and Shell seem to have exited the market for new US offshore wind leases. That leaves Equinor (2/3 Norwegian govt ownership) as the only major oil company pursuing US offshore wind leases.
“Today’s lease sale reflects the forward momentum we are seeing to power millions of American homes with clean energy and create good-paying, climate jobs,” said White House National Climate Advisor Ali Zaidi. “With nine commercial-scale projects approved in the last three years and more to go, we are using every available tool to grow the American offshore wind industry as we strengthen the nation’s power grid and tackle the climate crisis.”
Rystad Energy projects a 10% annual compound growth rate for the subsea market from 2024 to 2027, with total spending anticipated to exceed $42 billion by the end of this period.
Brazil dominates the subsea umbilical risers and flowlines (SURF) market. Unsurprisingly, the US is lagging given the absence of a robust offshore leasing program and the dearth of deepwater discoveries in recent years.
Additionally, ultimate authority over the wind farm remained unclear, with various federal agencies claiming responsibility over different portions of the permitting, licensing, review, and operation of the wind farm.
“Sometimes I have a hard time figuring out, who do we talk to? Who is going to keep us safe? Who is the responsible boss here? Who is going to make the hard decision?” Select Board member Matt Fee asked.
Separate legislation granting redundant or overlapping authority to different departments or agencies.
Legislation that is non-specific, assigning broad authority to the President or cabinet level level officials, leaving it up to the bureaus to resolve.
Bi- and multi-lateral agreements like MOA’s and MOU’s, which are intended to “coordinate the redundancy,” often cause more confusion than they prevent, creating gaps in the process.
“Fixing” problems by adding redundancy.
The Dept. of the Interior’s division of responsibilities for offshore wind, which was finalized in January 2023, inexplicably assigns review and approval of Construction and Operations Plans to the Bureau of Ocean Energy Management (i.e. the land manager, lessor, and wind energy promoter) rather than the Bureau of Safety and Environmental Enforcement (i.e. the principal regulator of the activities described in those plans).
More significantly, the offshore wind responsibilities of the 2 bureaus are so intertwined (as is also the case for offshore oil and gas), that attempts to separate the functions have, at a minimum, created inefficiencies and increased regulatory and operational costs.
FTR, the idea that having the BOEM and BSEE functions combined in a single bureau, as was the case with the predecessor bureau (MMS), had anything to do with the Macondo blowout is a complete fallacy. Regarding the accusations that were made toward MMS, the Chief Counsel for the national commission that investigated the tragic incident found no evidence that ethical lapses on the part of MMS employees played any role in causing the blowout.
There were important regulatory changes made after the Macondo blowout. These included capping stack requirements, mandatory safety management systems, and updated rules and standards for cementing/zonal isolation and blowout preventer systems. None of these improvements were precipitated by or dependent on the division of MMS into two bureaus.
API is challenging the Dept. of the Interior’s 5 year oil and gas leasing plan, which includes the fewest lease sales in program history. That challenge was filed on 12 February, 60 days after Secretary Haaland approved the 5 plan and the first day appeals could be filed pursuant to 43 U.S. Code § 1349.
18 weeks after the API suit was filed, the Supreme Court overturned the Chevron Doctrine. That doctrine (described above) instructed judges to defer to agency interpretations when the language in a law was unclear.
Extending the Secretary’s general safety and environmental authority for OCS operations to include global climate considerations is a stretch and the type of interpretive administrative decision that the Supreme Court struck down.
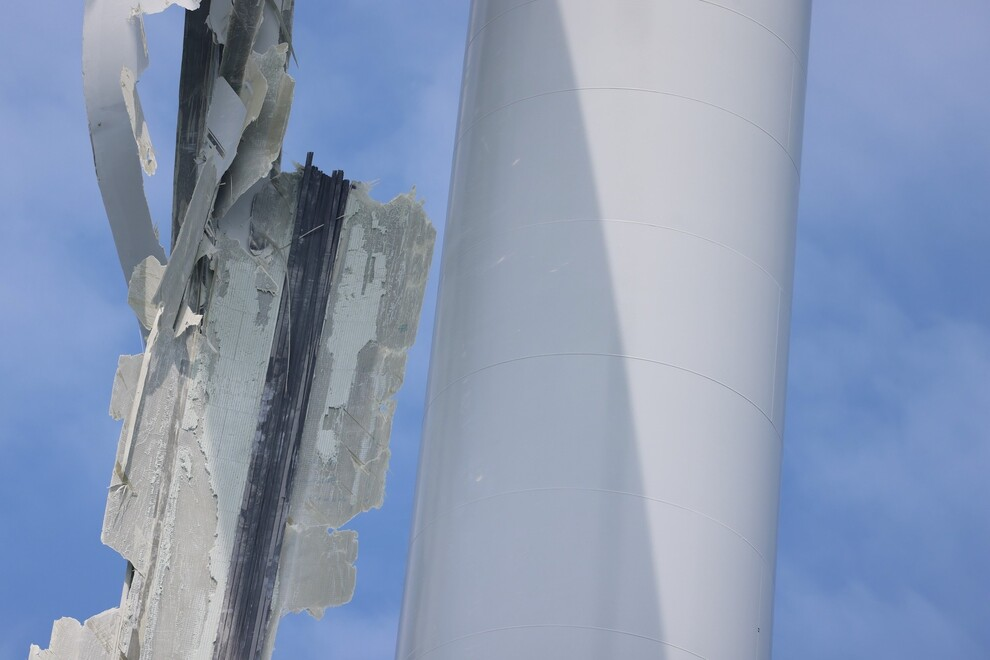
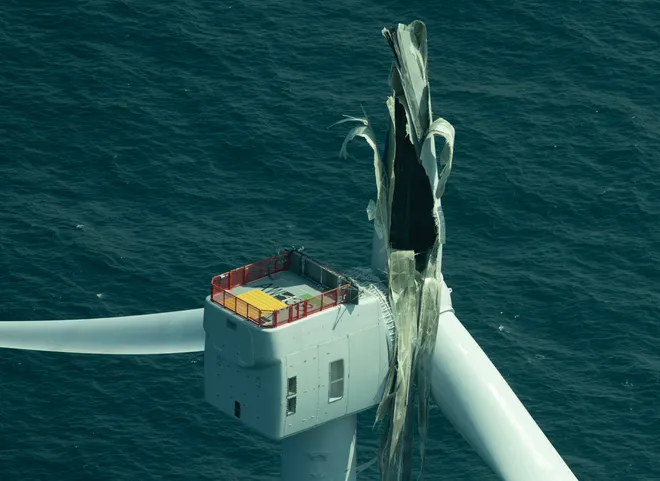
As the above examples illustrate, turbine blade failures, like the Vineyard Wind incident near Nantucket, are not unique to GE Vernova. GE’s rivals, Siemens Gamesa and Vestas, have also experienced serious quality control issues.
Per ReviewEconomy (2023), “Unexpected and increasing wind turbine failure rates, largely in newer and bigger models, are savaging the profits of some of the world’s biggest manufacturers, as Siemens Gamesa, GE and Vestas report heavy repair and maintenance losses.”
In light of the manufacturing challenges, all 3 companies report increased emphasis on quality control. Why has quality control to date been inadequate and how will the past problems be corrected?
Has the wind industry’s sense of entitlement, as evidenced in their tax credit, rate increase, and departure expectations, affected their safety and quality culture? Has industry and governmental wind energy promotion rushed development and compromised design and fabrication decisions? It’s time for wind developers, manufacturers, and regulators to make sure their priorities are in order.
Contrary to the regulations, Vineyard Wind was authorized to begin the fabrication of facilities beforeBOEM “received and offered no objections to the their Facility Design Report (FDR) and Fabrication and Installation Report (FIR).” The approval letter is attached, and excerpts (emphasis added) are pasted below. [Note: The requirement that was then at §585.700(b) is found at §585.632 in the current regulations.]
“Vineyard Wind requests a regulatory departure from §585.700(b) requiring that fabrication of approved facilities not begin until BOEM provides notification that it has received and has no objections to the submitted Facility Design Report (FDR) and Fabrication and Installation Report (FIR). Vineyard Wind proposes to fabricate, but not install the following project elements: 1) Monopile foundations; 2) Electrical service platform; 3) Export cable; 4) Inter-array cables; and 5) Wind turbine generator facilities.
….allowing these fabrication activities to take place earlier in time would allow Vineyard Wind to adhere to its construction schedule, maintain its qualification for the Federal Investment Tax Credit, and meet its contractual obligations under the Power Purchase Agreements with Massachusetts distribution companies.
30 cfr 585.103 requires that a departure provide safety and environmental protection equal to or greater than the provision in the regulations that is waived. BOEM’s letter fails to explain how allowing fabrication to begin before fundamental design and fabrication reports are submitted and reviewed meets this test.
Perhaps even more troubling is BOEM’s response to subsequent requests by other companies to waive the FDR and FIR requirement (example). In these responses, BOEM asserts that their “current interpretation” is that no departure is needed because “the regulation prohibits only fabrication and installation activities on the Outer Continental Shelf (OCS) itself.” How does that make sense given the important activities, including the fabrication of turbine blades and other turbine components, that take place onshore?
In their letters approving the Vineyard Wind and other departures, BOEM implies that their review of these reports is unnecessary because “the design and fabrication of these components would occur under the supervision of the approved CVA” (Certified Verification Agent). That assertion misconstrues the role of the CVA. These agents, nominated and funded by the operator, provide third party oversight that is complementary to, not a substitute for, BOEM/BSEE project reviews.
According to this memo, DNV was the CVA for Vineyard Wind. Their insights on the turbine blade failure will presumably be included in BSEE’s investigation report.