Feeds:
Posts
Comments

Archive for the ‘energy policy’ Category

“Exxon Mobil has led a persistent and apparently successful lobbying campaign behind the scenes to push the US federal government to adopt rules that would allow the conversion of existing oil and gas leases in the Gulf of Mexico into offshore carbon capture and storage (CCS) acreage, according to documents seen by Energy Intelligence and numerous interviews with industry players.” Energy Intelligence

The Energy Intelligence article documents the ongoing carbon disposal lobbying by Exxon and others. Those meetings are okay prior to publishing a Notice of Proposed Rulemaking (NPRM) for public comment. However, the article implies that the next step is a final rule: “Whether or not Exxon succeeds will become fully clear when the US issues final rules guiding CCS leasing, expected sometime this year.”

A final rule this year is unlikely, because an NPRM has to be published first for public comment. The only exception would be if BOEM was able to establish “good cause” criteria for a direct final or interim final rule in accordance with the Administrative Procedures Act. Such an attempt at corner cutting seems unlikely, especially in an election year when all regulatory actions are subject to additional scrutiny.

Exxon must have thought they had a clear path forward after 11th hour additions to the “Infrastructure Bill” authorized carbon disposal on the OCS, exempted such disposal from the Ocean Dumping Act, and provided $billions for CCS projects. Keep in mind that the Infrastructure Bill was signed just two days before OCS Oil and Gas Lease Sale 257, at which Exxon acquired 94 leases for carbon disposal purposes.

What the Infrastructure Bill did not provide is authority to acquire carbon disposal leases at an oil and gas lease sale. Now the lobbyists are apparently scrambling to overcome that obstacle administratively.

BOEM, which arguably made a mistake in accepting irregular carbon disposal bids at the last 3 oil and gas sales, should not amplify Exxon’s unfair advantage (also Repsol at Sale 261) by allowing the conversion of these leases (map below). This is not a small matter given that Exxon has publicly projected that carbon disposal is a $4 trillion market opportunity.

A single company or small group of companies should not be dictating the path forward for the Gulf of Mexico. Super-major Exxon is a relative minnow in the Gulf of Mexico OCS. They have not drilled an exploratory well since 2018, not drilled a development well since 2019, operate only one platform (Hoover, installed in 2000), ranked 11th in 2023 oil production, and ranked 29th in 2023 gas production.

Lastly, and most importantly, public comment on the myriad of technical, financial, and policy issues associated with GoM carbon disposal is imperative. That input is essential before final regulations are promulgated.
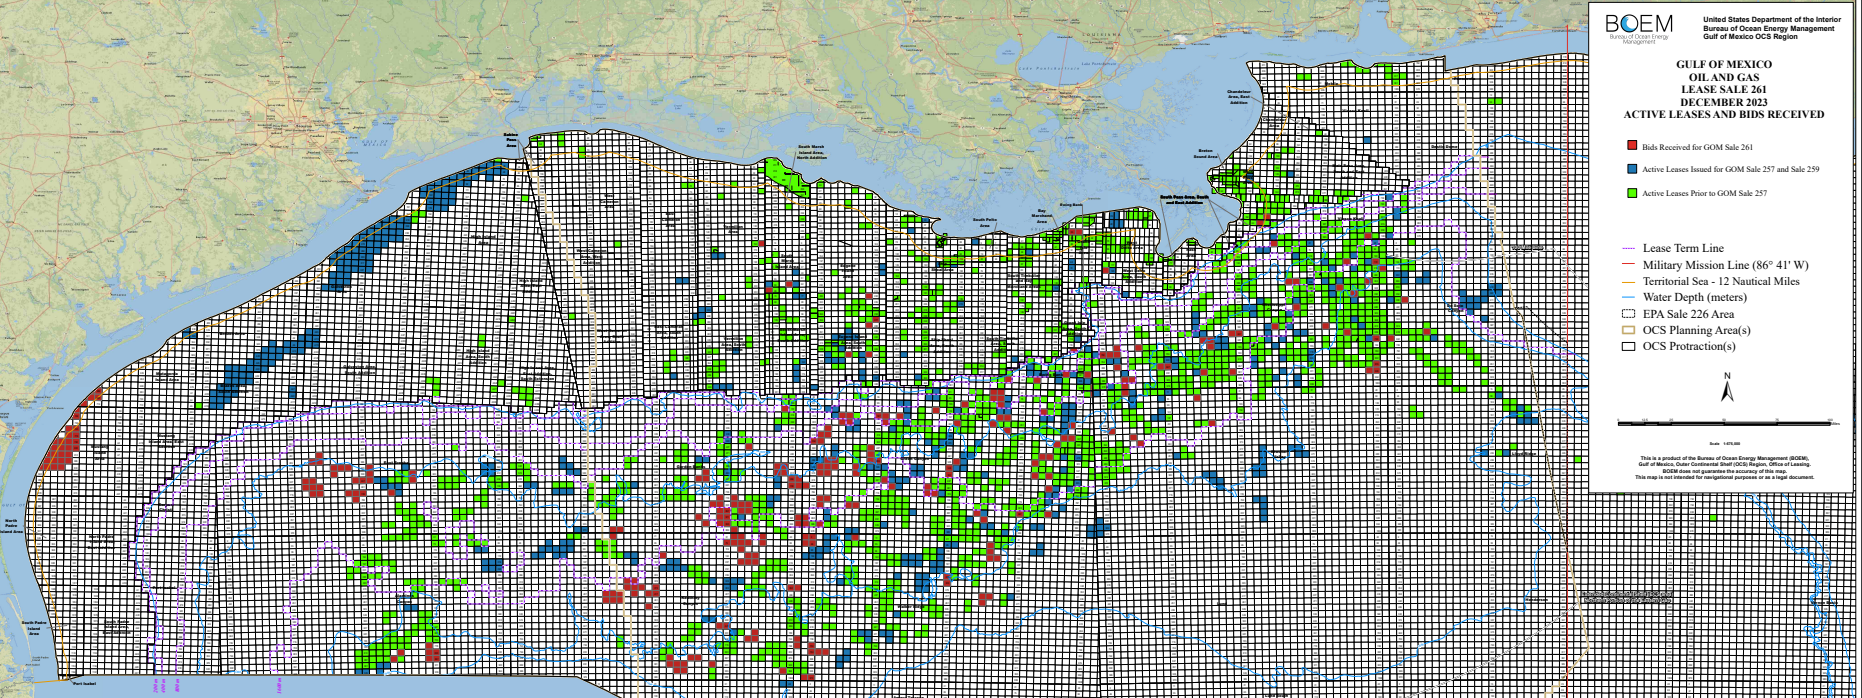
At Sale 261, Repsol was the sole bidder for 36 nearshore Texas tracts in the Mustang Island and Matagorda Island areas (red blocks at the western end of the map above). Exxon acquired 163 nearshore Texas tracts (blue in map above) at Sales 257 and 259.

Read Full Post »

It’s OTC week and optimism abounds. We are so back!”

Preachin’ to the choir:

  • Deepwater is back in vogue.” (Pablo Medina, Welligence)
  • “Newer deepwater projects have the attributes oil and gas companies are looking for: longer-term production, lower breakeven costs, big resource potentials and lower carbon emissions.” (Medina)
  • Capital spending on all-new deepwater drilling is poised to hit a 12-year high next year (Rystad)
  • Investment in all-new and existing deepwater fields could hit $130.7 billion in 2027, a 30% jump over 2023 (Rystad)
  • Deepwater resources offer lower carbon emissions intensity than shale and other tight oils, averaging 2kg of carbon dioxide per barrel less than shale. (Rystad)
  • “The return of offshore and deepwater operations is going to be a big topic at OTC, and Namibia is going to be talk of the show.” (James West, Evercore)
  • Enthusiasm for offshore has climbed with discoveries and technology breakthroughs. Namibia’s Mopane is forecast to hold as much as 10 billion barrels of oil. (Portuguese oil company Galp Energia)
  • Rates for some rigs have surpassed $500,000 a day and contract durations are lengthening as supply dwindles.
  • Deepwater development: simpler, safer, greener!
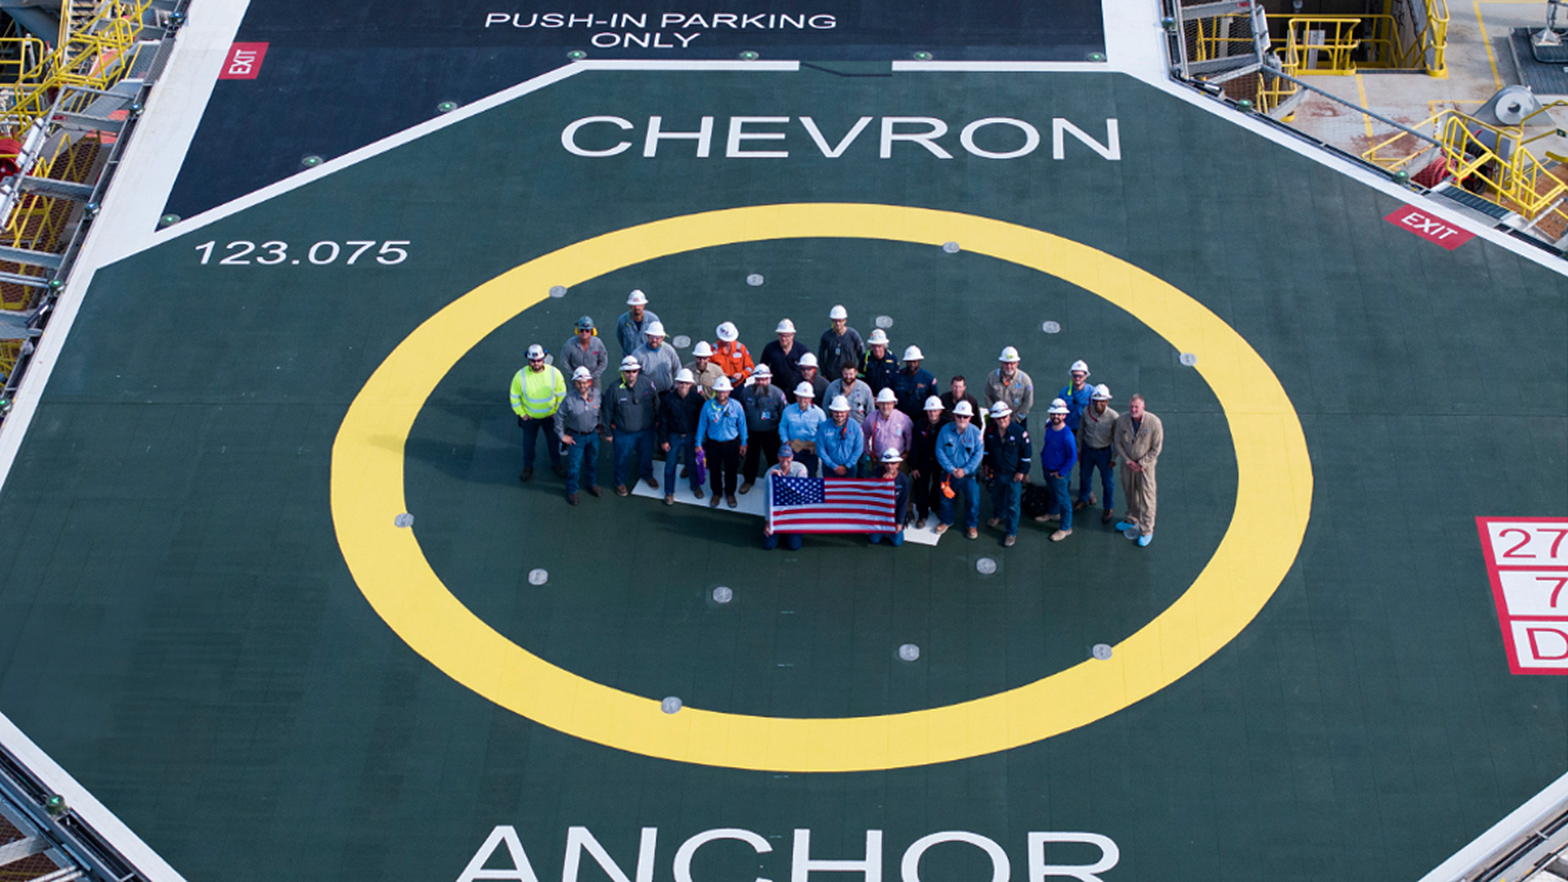
  • Chevron is preparing to start ultra-high pressure production at their Anchor platform.

So as not to kill the buzz, I won’t mention the 5 Year (no)Leasing Plan and other troubling US matters, at least for one day.

Read Full Post »

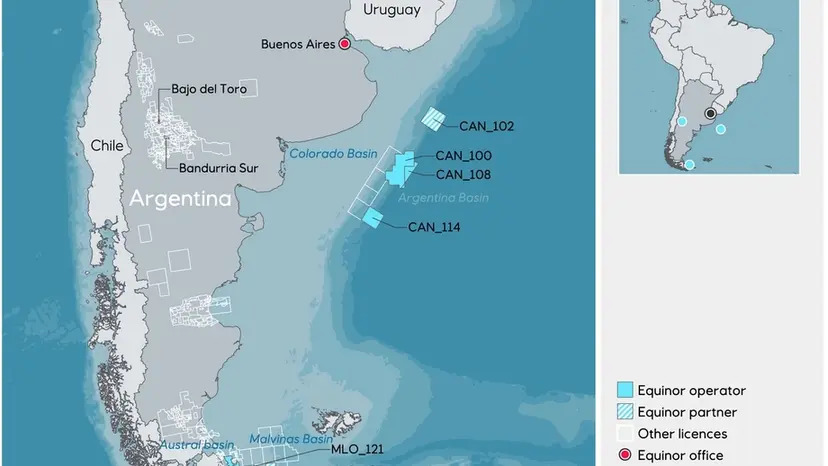
The Valaris DS-17 drillship is now on location to drill the Algerich-1 well for Equinor 315 km from Mar del Plata in 1527 m of water at Block CAN 100.

Concurrently, at the opposite end of the Pan American continents, the Stena DrillMAX is closing in on Exxon’s Orphan Basin location offshore Newfoundland to drill another high potential well.

Meanwhile, the US Atlantic is “wind-only,” despite high deepwater oil and gas potential. The late Paul Post, an esteemed colleague and the leading expert on the petroleum geology of the US Atlantic, believed the deepwater US Atlantic could contain >20 billion BOE. No other Pan American nation has completely closed its Atlantic margin to oil and gas exploration.

Can a nation with a debt of $35 trillion afford to ignore oil and gas resources that will remain in high demand for decades?

Read Full Post »

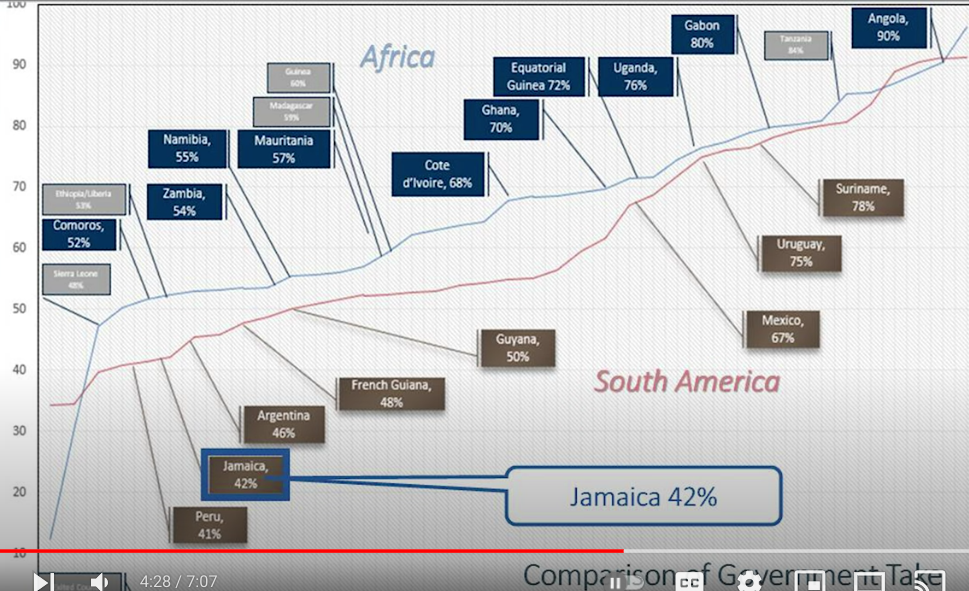
As reported in January, United Oil and Gas received a 2 year extension from the Government of Jamaica on their Walker Morant License. Below is a United video produced for prospective partners.

While the investment risk is undeniable, the reward potential is high.

Below is an interesting slide from the United presentation that compares the government’s take of production revenues for various African and S. American nations.

Read Full Post »

After the announcement of further restrictions on resource development in the National Petroleum Reserve of Alaska (NPR-A), Senator Sullivan (AK) called on the administration to stop sanctioning Alaska and to instead restore sanctions on Iran

The US OCS is being similarly sanctioned by its own government. The 5 year OCS “leasing plan” not only excludes all areas except the Gulf of Mexico, but authorizes a maximum of only 3 sales, the fewest ever for a 5 year program. The number of sales may well have been zero were it not for the requirement to hold an oil and gas sale during the year prior to the issuance of a lease for wind development.

2024–2029 Proposed Final Program Lease Sale Schedule
CountSale NumberSale YearOCS Region and Program Area
12622025Gulf of Mexico:  GOM Program Area
22632027Gulf of Mexico:  GOM Program Area
32642029Gulf of Mexico:  GOM Program Area
Most limited 5 year leasing program in history

Read Full Post »

Given the current guidance for implementing the OCS Lands Act’s “fair market value” mandate, all 12 of BOEM’s Sale 261 bid rejections (table below) were warranted:

  • All but one of the rejections was on a single bid tract.
  • BOEM’s Mean of the Range-of-Value (MROV) estimates were 2.6 to 18.7 times the rejected bonus bids.
  • The Adjusted Delayed Value (ADV), which takes into account the effects of delaying bonuses and future royalty payments, ranged from 1.3 to 9.2 times the high bids.
  • Perhaps the closest calls were Chevron’s two Walker Ridge bids which had ADV to bid ratios of only 1.3 to 1.4.

The main concern going forward is the absence of a consistent, predictable leasing schedule for the 3.7% of the OCS that may be considered for leasing. BOEM’s new methodology, which will be applied at the next lease sale (whenever that might be), does not require the bureau to estimate the delay period between the sale being evaluated and the projected next lease sale. Given that the new 5 year plan calls for a maximum of 3 lease sales, the gap between sales has become a much more significant factor just as the new guidance is being implemented.

The new 5 year “leasing plan” is intended to restrain OCS production in deference to “net zero” pathways. This strategy discourages interest from exploration and production companies. US offshore leases, which are by far the world’s smallest, are even less attractive when you don’t know if and when you will be able to acquire the nearby tracts that may be needed for economical deepwater development. This is not the way to obtain fair market value for public resources.

BlockNo. of bidsHigh Bid ($)MROV($)
ADV($)
High BidderMROV/bid
ADV/bid
MC 7111584,7006,600,000
2,400,000
bp11.3
4.1
MC 8961641,6286,100,000
1,600,000
Shell9.5
2.5
GC 1821800,0853,900,000
2,600,000
Anadarko4.9
3.2
GC 1831800,0859,100,000
6,000,000
Anadarko11.4
7.5
GC 2261800,0852,100,000
1,600,000
Anadarko2.6
2.0
GC 2272974,62813,000,000
9,000,000
Shell13.3
9.2
GC 34511,095,61513,000,000
5,300,000
Murphy11.9
4.8
GC 3461845,8155,100,000
2,000,000
Murphy6.4
2.4
GC 5491800,08515,000,000
6,900,000
Anadarko18.7
8.6
AT 2371909,8998,300,000
3,000,000
Equinor9.1
3.3
WR 2851859,8376,200,000
1,200,000
Chevron7.2
1.4
WR 3291595,8374,400,000
770,000
Chevron5.7
1.3
MROV=Mean of the Range-of-Value
ADV=Adjusted Delayed Value, which takes into account delaying bonuses and royalties

Read Full Post »

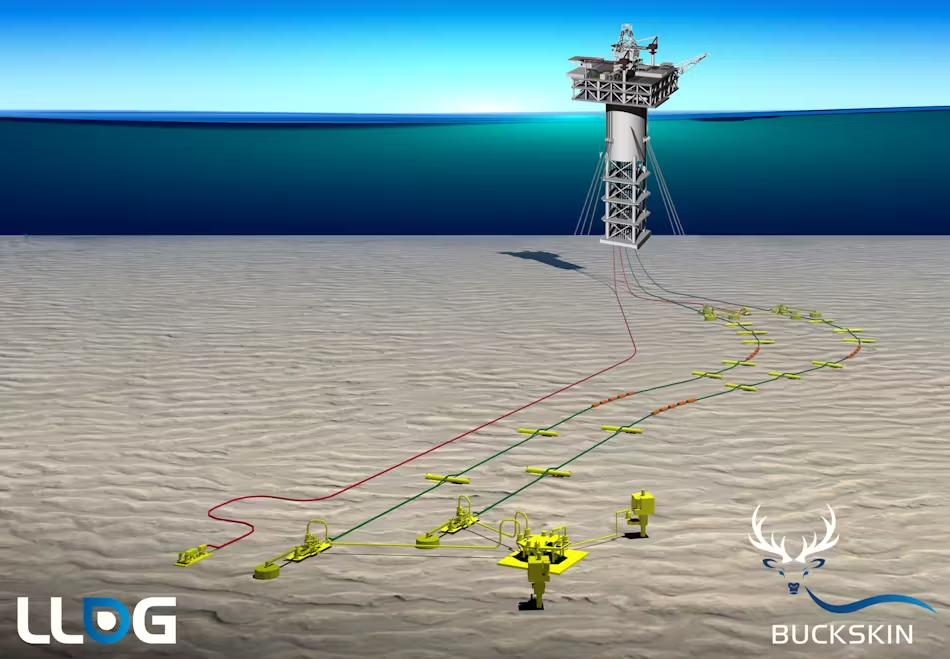
Houston, TX, March 29, 2024. Beacon Offshore Energy LLC (“Beacon”) announced today the completion of the divestment of its non-operated interests in certain fields in the deepwater Gulf of Mexico in accordance with a previously executed definitive agreement with GOM 1 Holdings Inc., an affiliate of O.G. Oil & Gas Limited. The divestment includes Beacon’s 18.7% interest in the Buckskin producing field, 17% interest in the Leon development, 16.15% interest in the Castile development, 0.5% interest in the Salamanca FPS/lateral infrastructure, and 32.83% interest in the Sicily discovery.

Beacon

According to BOEM records, GOM 1 HOLDINGS INC, a Delaware company, registered with BOEM effective 3/15/2024. The parent entity, O.G. Oil & Gas Limited, is a privately held E&P company incorporated in 2017 and based in Singapore.

O.G. Oil & Gas Ltd is part of the Ofer Global Group, “a private portfolio of international businesses active in maritime shipping, real estate and hotels, technology, banking, energy and large public investments.”

After a partial takeover by O.G Oil & Gas Limited in 2018, New Zealand Oil and Gas is now 70% owned by the Ofer Global Group. Among other interests, NZ Oil and Gas produces from fields offshore Taranaki, NZ.

Because they are jointly and severally liable for safe operations and decommissioning, minority investors should take a strong interest in safety management and financial assurance. Investors should remember that partners are adversely affected by the mistakes of the operating company. Anadarko and Mitsubishi took a hit following the Macondo blowout. To what extent had they been monitoring bp’s risk and safety management programs for drilling operations?

Read Full Post »

… and you deniers are fully responsible. There’s a reason why Texas is the most affected state 😉

But fear not, we will line our shores with wind turbines, restrict offshore oil and gas leasing, and subsidize carbon disposal in the Gulf of Mexico. All of this “help” will have a negligible effect on the climate, which will continue to change as it always has and always will.

Read Full Post »

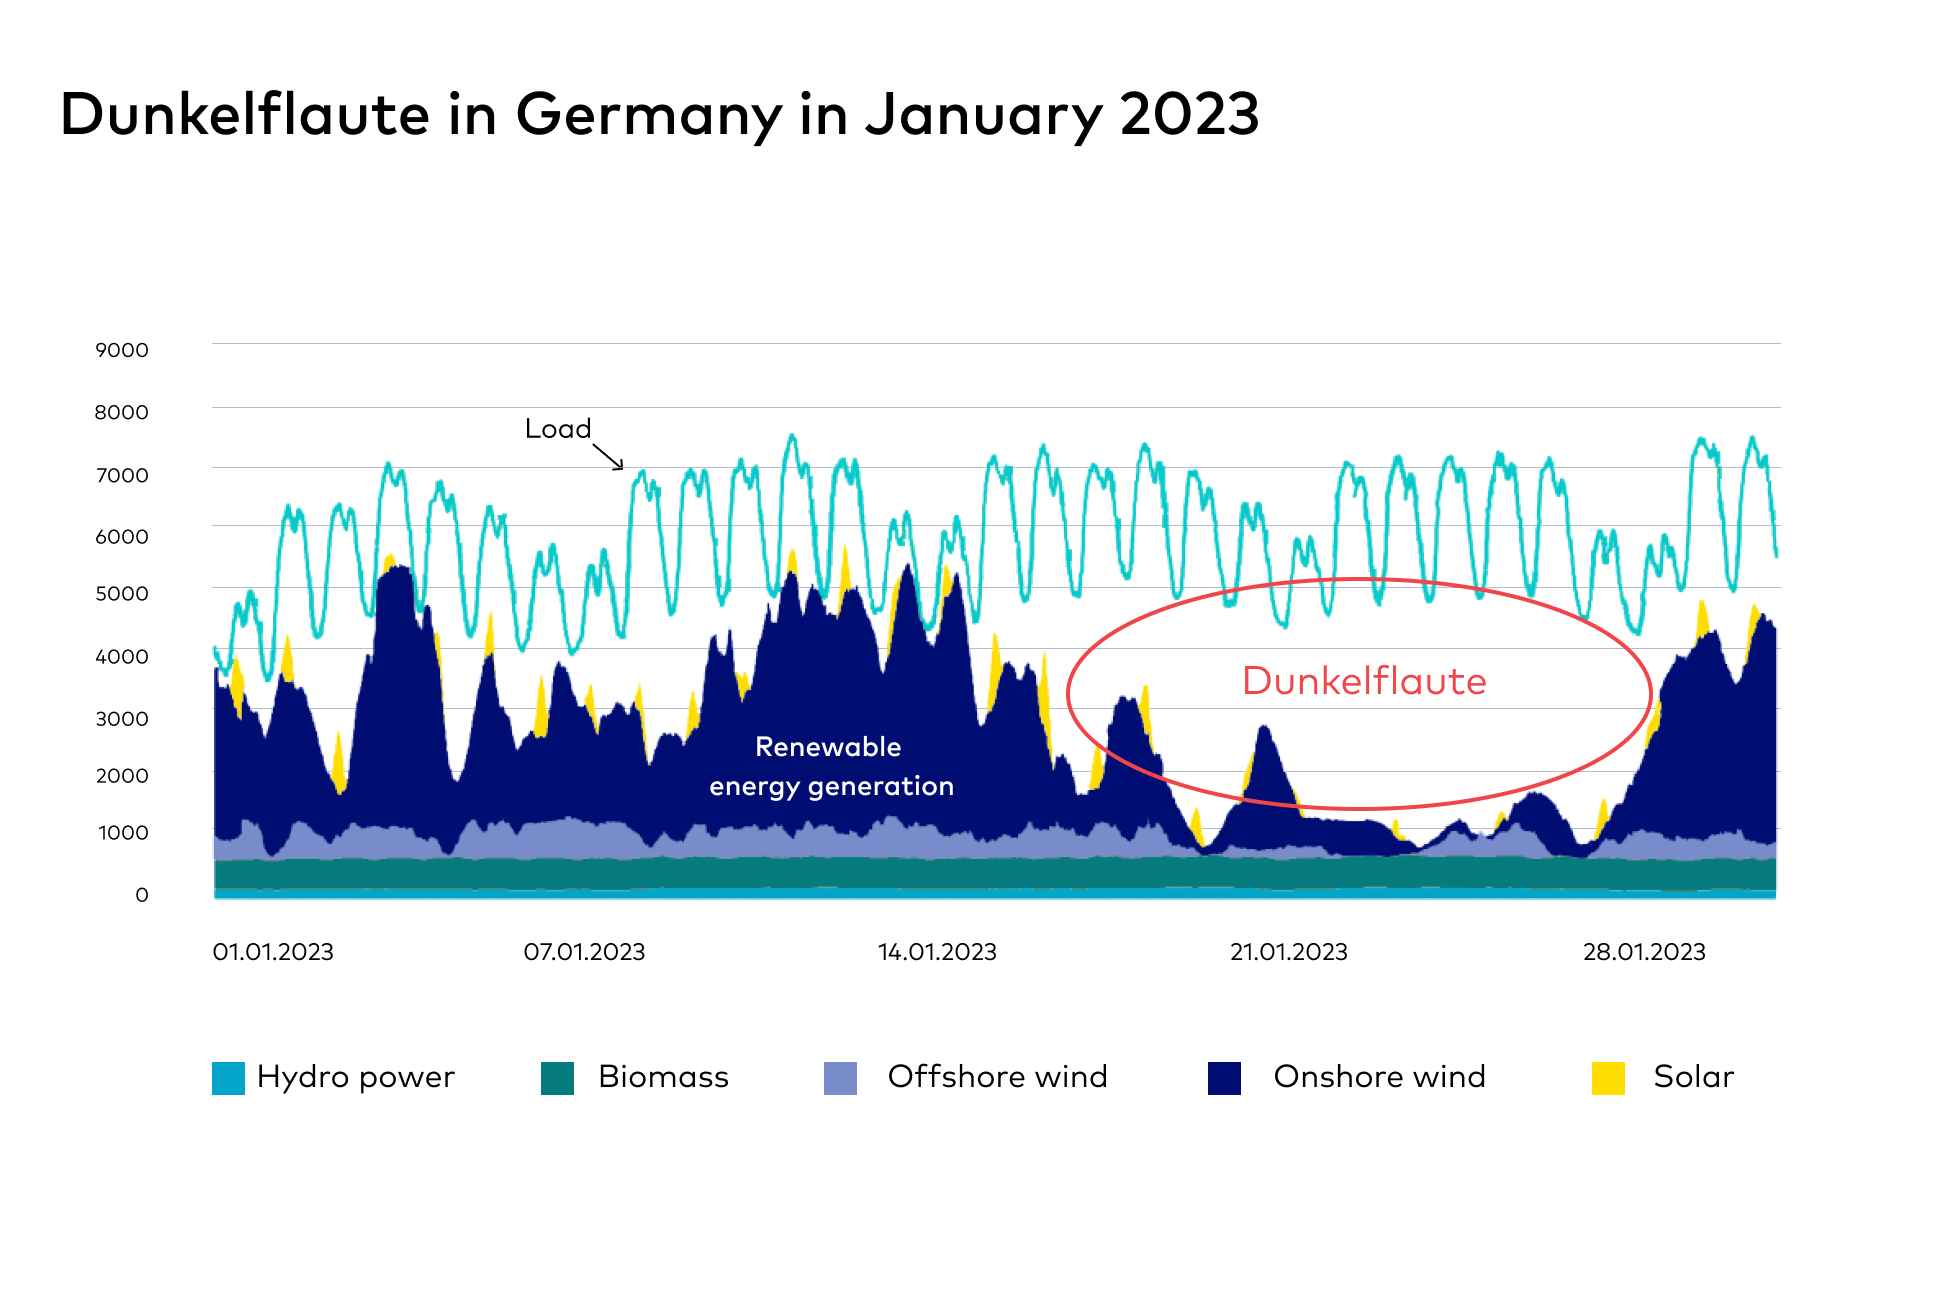
Add Dunkelflaute to the list of interesting and expressive compound German words. Die Dunkelflaute is a dark lull, a period of time in which minimal energy can be generated by the sun or wind. More specifically in German:

Die Dunkelflaute als sogenanntes Kofferwort beschreibt das gleichzeitige Auftreten von Dunkelheit und Windflaute. Diese Wetterlage entsteht typischerweise im Winter und sorgt für geringe Erträge aus Solar- und Windenergie bei gleichzeitig saisonal hohem Strombedarf. Eine Dunkelflaute kann mehrere Tage andauern. Kommen zu Dunkelheit und Windflaute noch niedrige Temperaturen hinzu, die für gewöhnlich den Strombedarf weiter ansteigen lassen, spricht man auch von “kalter Dunkelflaute.”

Note the prolonged Dunkelflaute (below) during which renewables provided minimal power in the middle of winter.

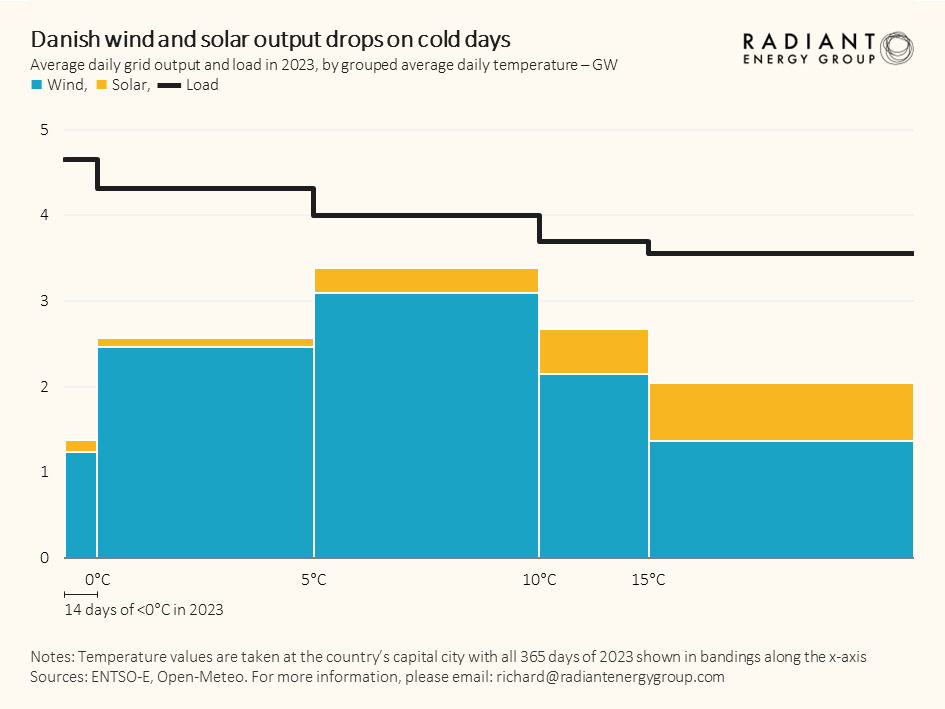
Unsurprisingly, wind and solar output are the lowest when the temperatures are the coldest. See the Danish summary for 2023 below. Note that wind output was also low when temperatures were above 15 deg. C.

Regional wind energy grids are not always an effective solution as Danish physicist Jens Christiansen, a nuclear energy advocate, has illustrated:

‘The wind always blows somewhere.’ Is that really true though? Here I’ve looked at the capacity factors of wind from five northern European countries in August The winds seem highly correlated, and there is almost a week-long period without significant wind anywhere.

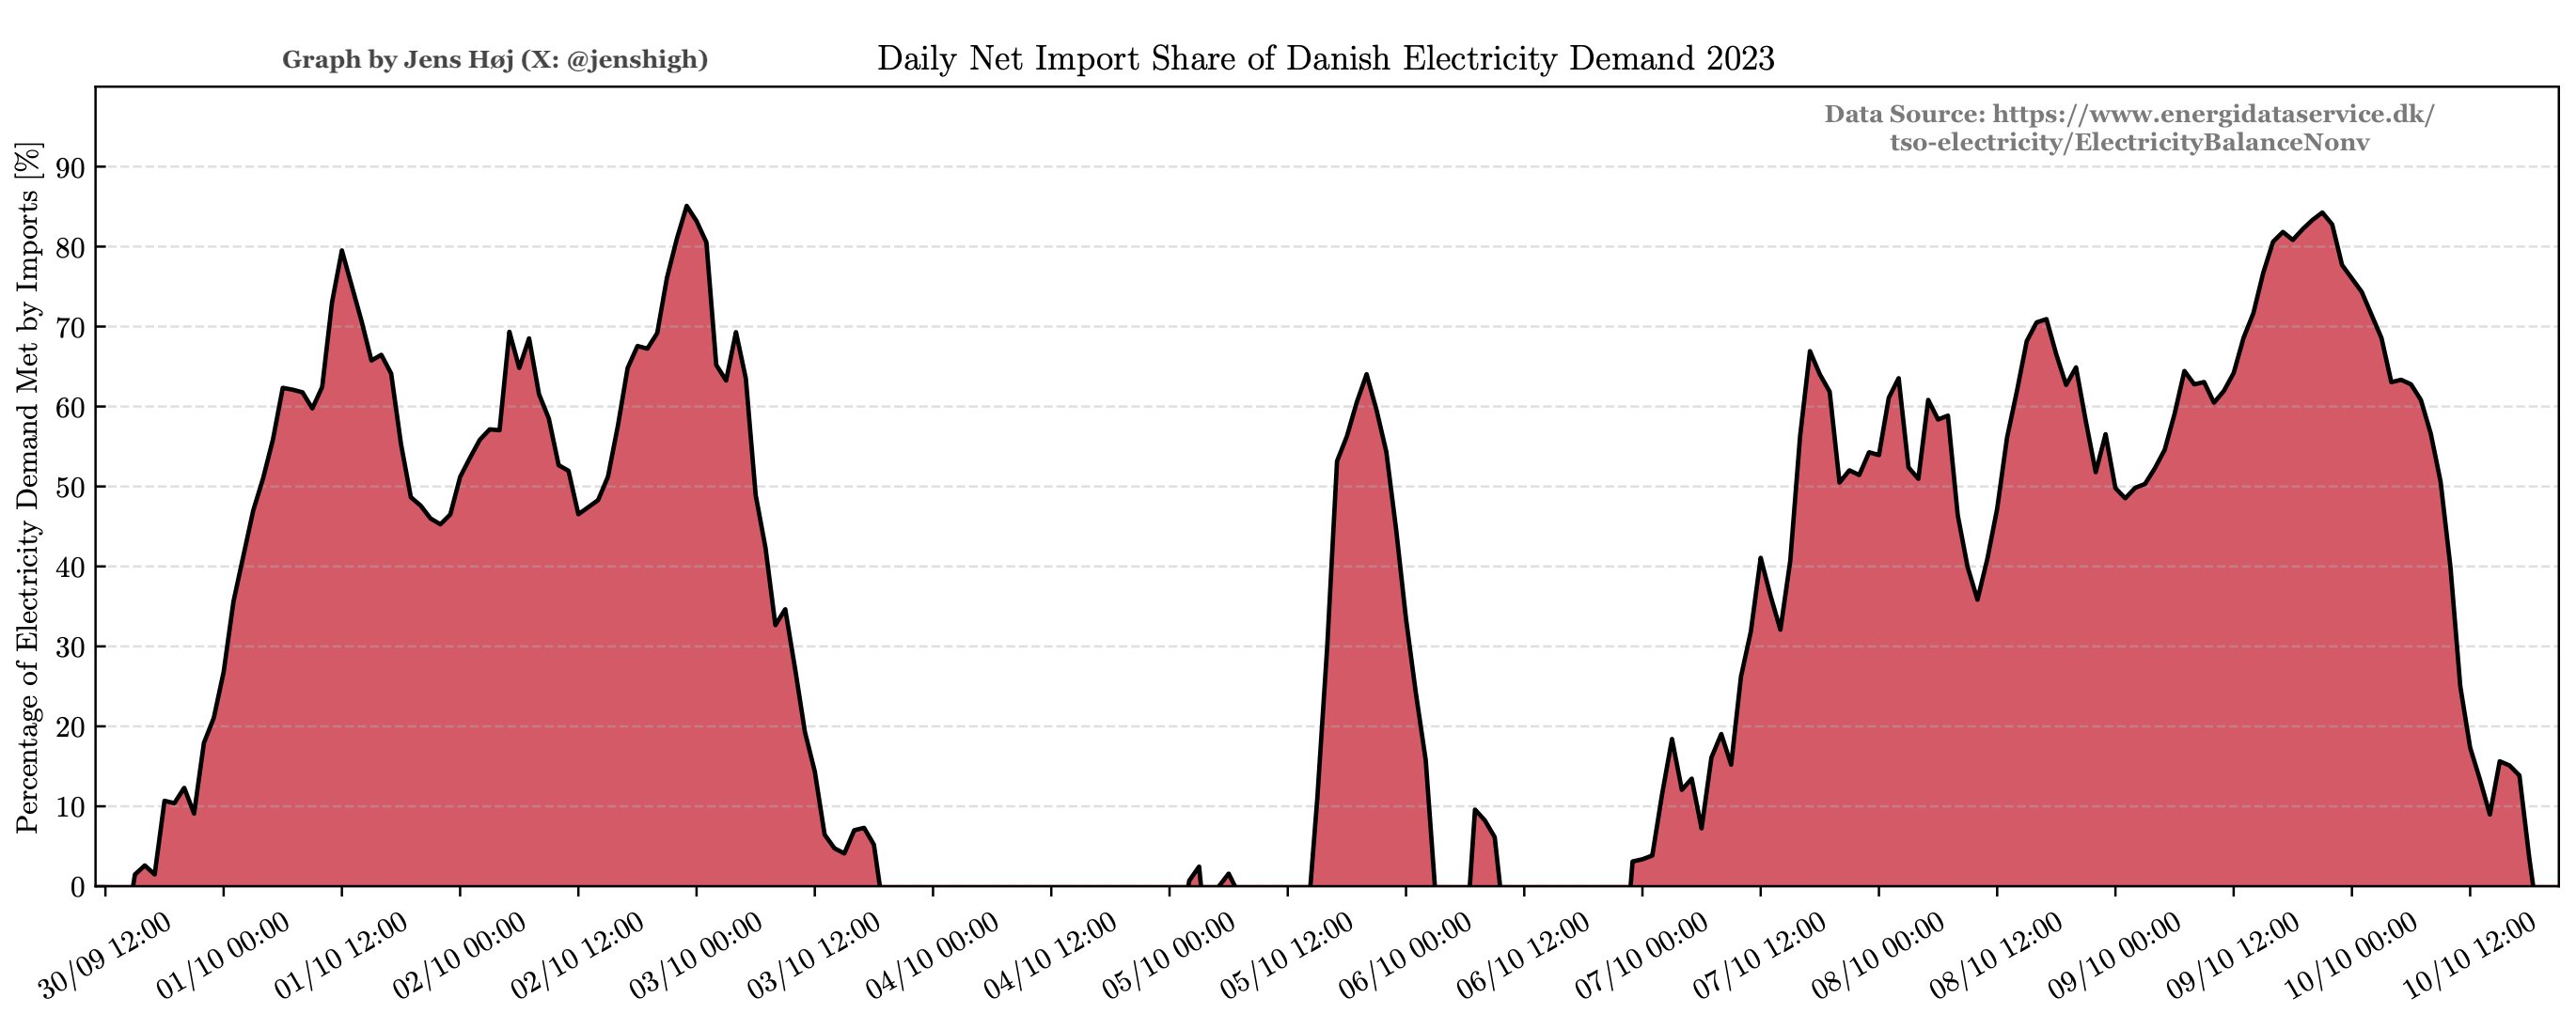
Christiansen illustrates Denmark’s reliance on imported electricity:

Paraphrasing Margaret Thatcher: “The problem with electricity imports is that you eventually run out of other people’s electricity.” In the U.S., California imports more electricity than any other state and typically receives between one-fifth and one-third of its electricity supply from outside of the state.

Given that massive battery storage is well beyond current capabilities and restrictions on electricity consumption and economic growth are undesirable, redundant or complementary power sources are essential for a reliable grid. Natural gas power generation is most responsive to variable demand, and is thus a good complement to variable sources like wind turbines and solar panels.

Read Full Post »

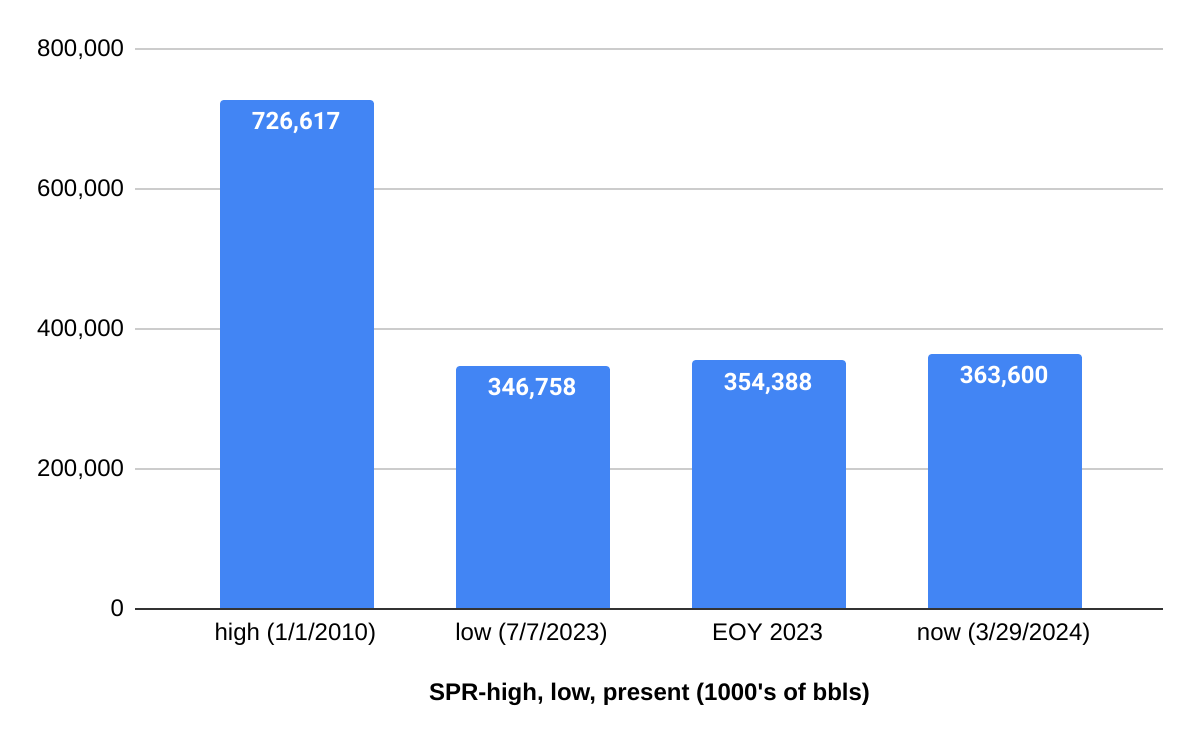
After announcing that the planned 40 million barrel SPR refill would be the equivalent of the massive 180 million barrel withdrawal, DOE has halted the refill at < half the planned amount. There is no end in sight for the SPR deficit (chart below).

Citing rising oil prices, the DOE said, “We will not award the current solicitations for the Bayou Choctaw SPR site and will solicit available capacity as market conditions allow.” Three million barrels of oil had been slated for delivery to the Bayou Choctaw SPR site in August and September.

Forbes

Read Full Post »

« Newer Posts - Older Posts »