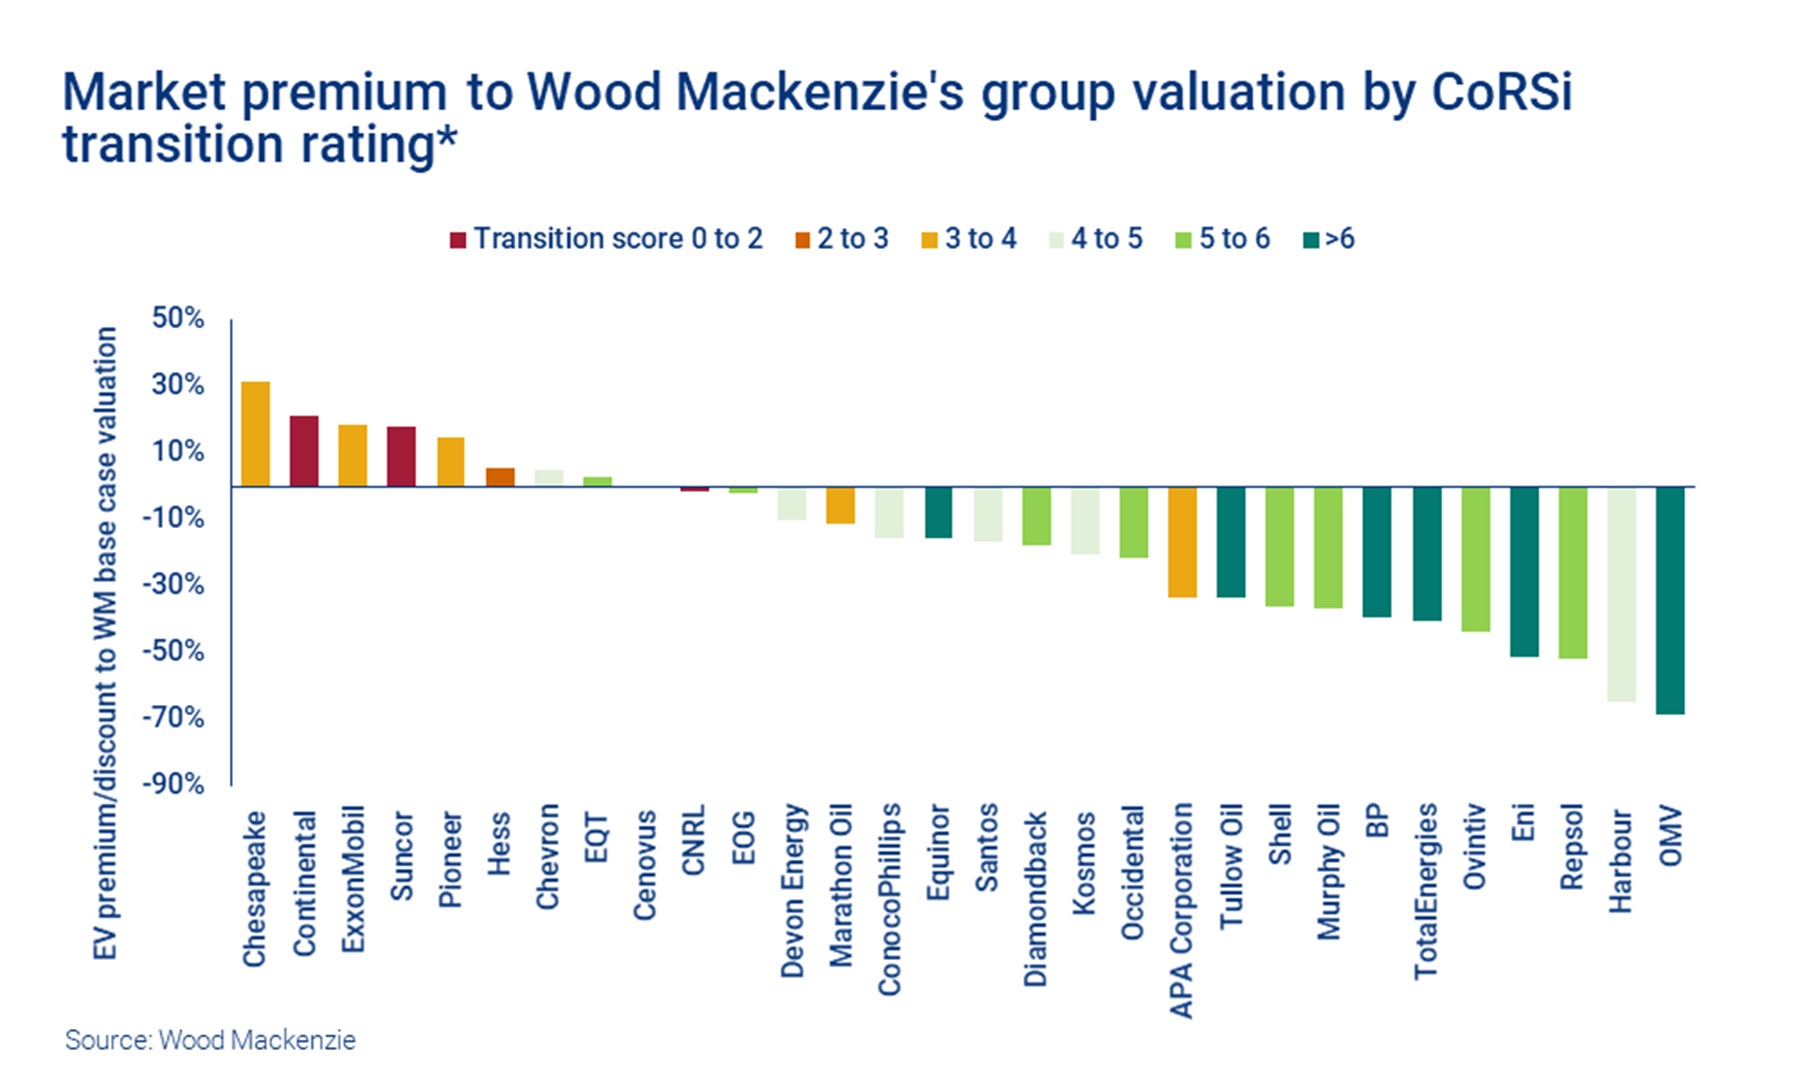
Per Wood Mackenzie, companies with low transition scores (i.e. the purer oil and gas plays) command higher valuations. I’d like to see the scores for other US independents.
“First, investors piled into the pure play oil and gas producers that are most leveraged to oil prices, much as they would in any upcycle. US independents led the sector rise through early June before the oil price and shares fell back over the last month.“
“Euro Majors are also reaping the earnings and cash flow boom. Share price performance has been strong relative to the wider stock market, but most have lagged their US peers. US Majors have long commanded a premium rating to their European counterparts, partly a function of the relatively high rating of the US stock market. The gap though has widened.”
Given the differences in our views on energy policy, particularly with regard to oil and gas, this WP opinion piece is pretty reasonable. The Post acknowledges the continued need for oil and gas, and the importance of domestic production. That said, two statements in the paragraph pasted below warrant immediate comment.
“In reality, neither argument is convincing. The Biden administration’s proposal — which opens the door to up to 11 potential lease sales, 10 in the Gulf of Mexico and one off the coast of Alaska — would have little impact on current energy prices. It would take between five and 10 years to produce oil after a new offshore lease issuance, according to the Interior Department, while more than three-quarters of already-leased offshore federal waters are not in production.”
The purpose of the 5 year leasing plan is to minimize future energy supply and security risks, not to reduce current prices. However, acknowledgement of the importance of offshore production and support for regular lease sales could influence market psychology.
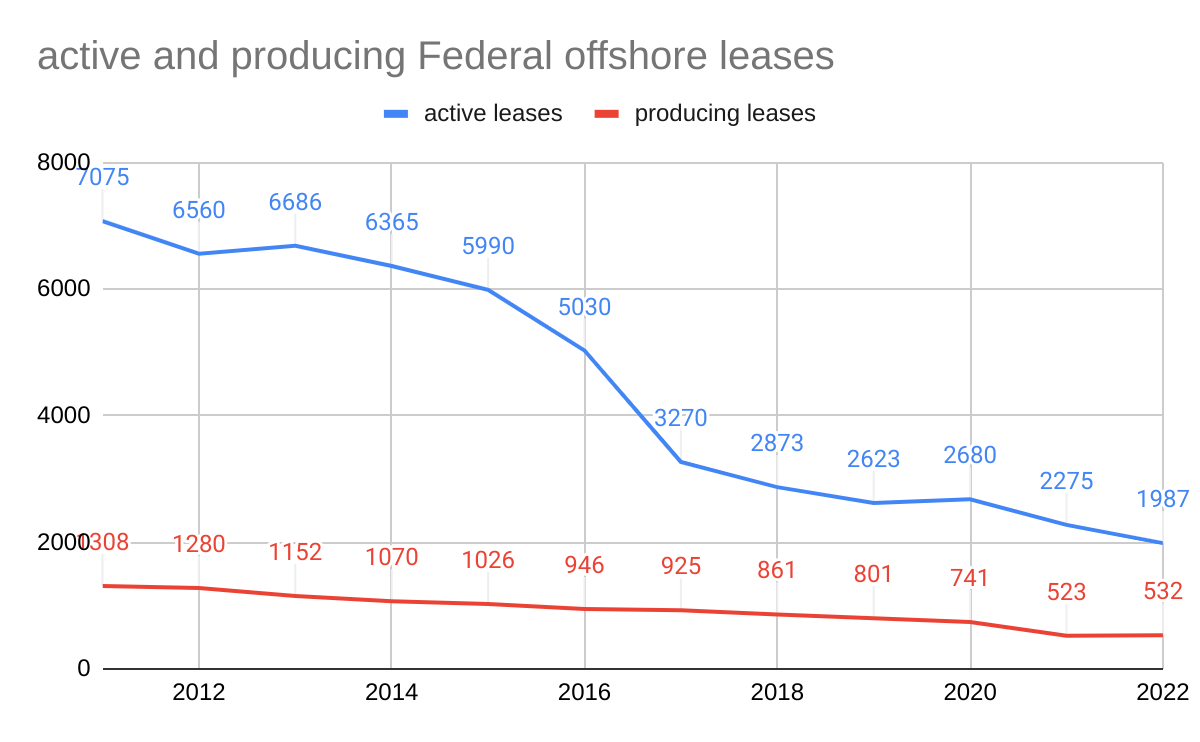
The old and tired arguments about non-producing leases have been frequently addressed on this blog. When you purchase leases, you are not buying oil and gas. You are buying only the opportunity, for a limited period of time, to explore for these commodities. The current percentage of producing leases is actually rather high by historical standards. For more on this topic, see this and this.
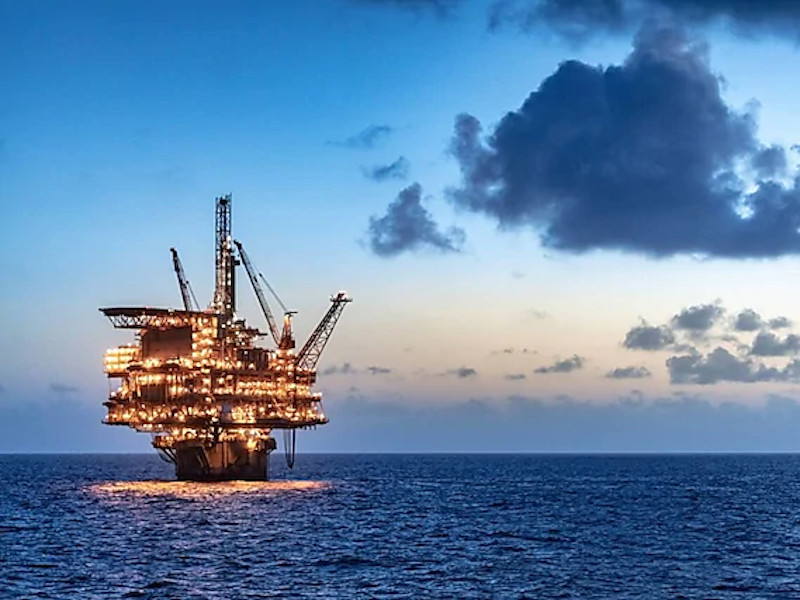
In particular, the Energy and Interior Secretaries would benefit from a visit to a deepwater production facility. They would no doubt be impressed and would be better able to make informed decisions affecting US offshore leasing, exploration, and development.
The offshore workers would be respectful and would welcome the opportunity to discuss the technology, safety precautions, and environmental protection measures.
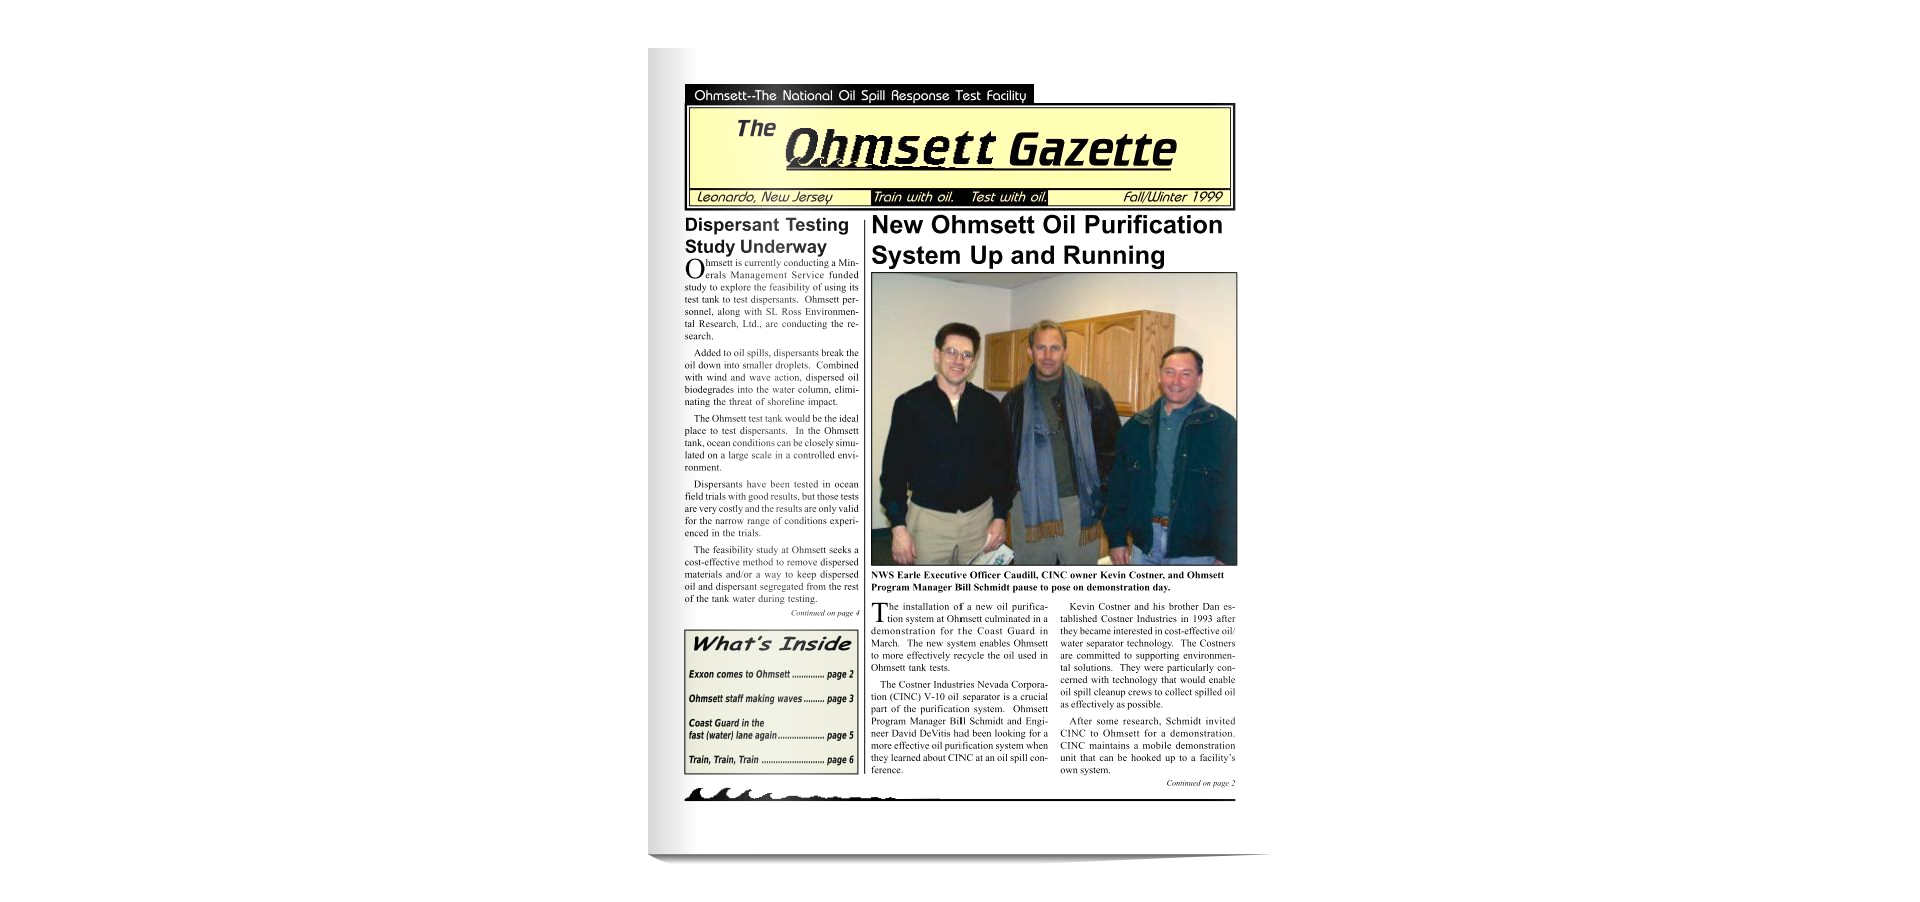
My involvement with Ohmsett dates back to the 1970s when EPA operated the facility and I was on the Ohmsett Interagency Technical Committee. The facility fell into disrepair in the late 1980s. Thanks largely to the vision and initiative of my Minerals Management Service (MMS) colleague Ed Tennyson and the enactment of the Oil Pollution Act of 1990, the MMS began restoring the facility in 1990 and resumed testing activities in 1992. Senator Frank Lautenberg (NJ) and a host of dignitaries participated in the grand reopening event.
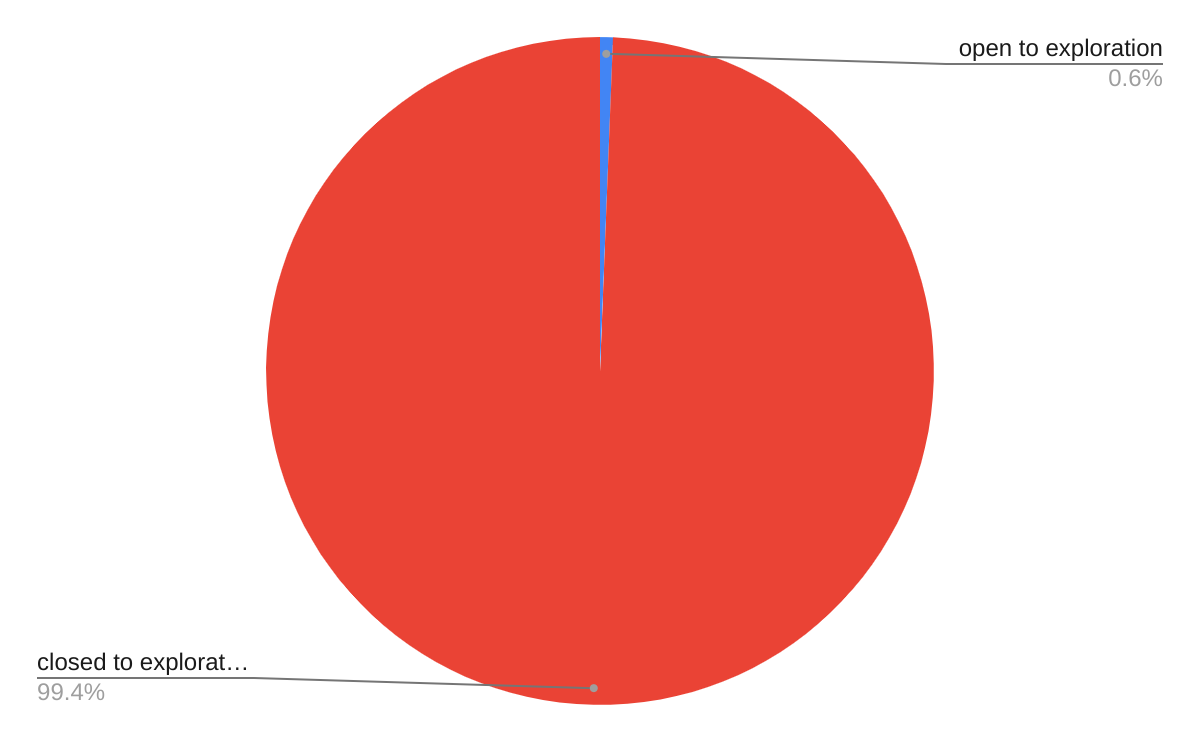
“The (worldwide) drop in reserves is driven by the 30 billion barrels of oil produced last year, plus a significant reduction in undiscovered resources, to the tune of 120 billion barrels. The US offshore sector has contributed the largest total to that drop, where 20 billion barrels of oil will remain in the ground, largely thanks to leasing bans on federal land.“
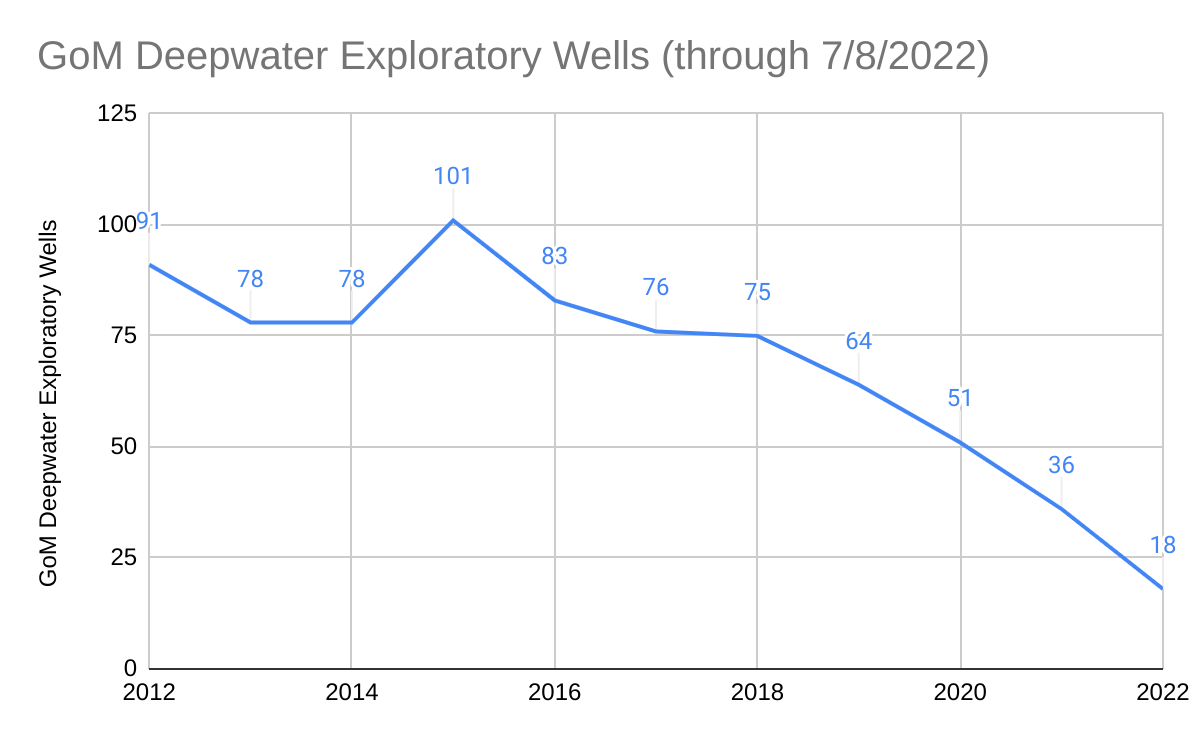
The decline in reserves should come as no surprise to those who follow the US offshore sector. Note the sharp decline in exploratory drilling in the (updated chart below) and the calls for action on this blog a year ago and more recently.
The OCS oil and gas program requires a sustained, consistent commitment by government and industry. Such a consistent commitment, even though required by legislation, is difficult to achieve in our political system, .
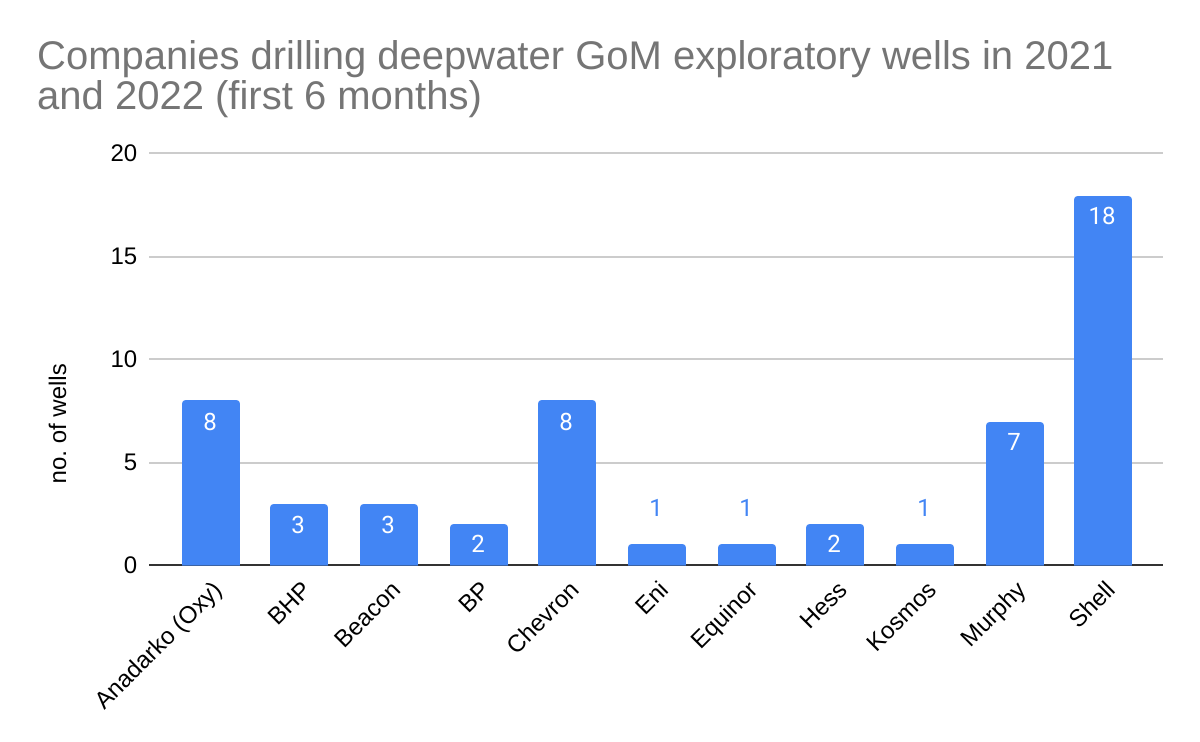
The commitment by the oil and gas industry has also been uneven and in some cases disappointing. BOE continues to be troubled by the reduction in exploration by some companies and the decision by others, including leading US companies with a long history of Gulf of Mexico operations, to exit the US offshore sector completely (see the chart below). The exploration decline began before the leasing shutdown (now 600 days in duration). Inconsistent signals from the Federal government and corporate directors, market considerations, and competing investment opportunities are major factors, but there are no doubt other considerations. Constructive dialogue to address these issues is badly needed.
“BOEM’s short-term (20-year) production forecast for existing leases shows steady growth from 2022 through 2024 and declining thereafter (see Section 5.2.1). The long-term nature of OCS oil and gas development, such that production on a lease can continue for decades makes consideration of future climate pathways relevant to the Secretary’s determinations with respect to how the OCS leasing program best meets the Nation’s energy needs.“
Basing leasing decisions on “future climate pathways” would seem to be a considerable stretch of the Secretary’s authority under the OCS Lands Act and may be inconsistent with the recent SCOTUS decision in West Virginia vs. EPA. A strategic shutdown of the offshore oil and gas program would dramatically increase energy supply and security risks going forward, and should be authorized by Congress.
“Norwegian offshore oil and gas workers went on strike Tuesday. The stoppage could reduce the country’s gas output by almost a quarter and intensify supply chain shortages due to Russian gas boycotts by EU nations.”
Yet the proposed 5 Year OCS leasing program (p. 3) tells us that long term offshore production is not needed because the IEA’s “roadmap to net-zero emissions by 2050 for the global energy sector would require no new investment in fossil fuel supply projects (IEA 2021).”
Does the IEA dictate US energy policy? Dan Yergin has a far better grasp on the realities of energy consumption and transitions.
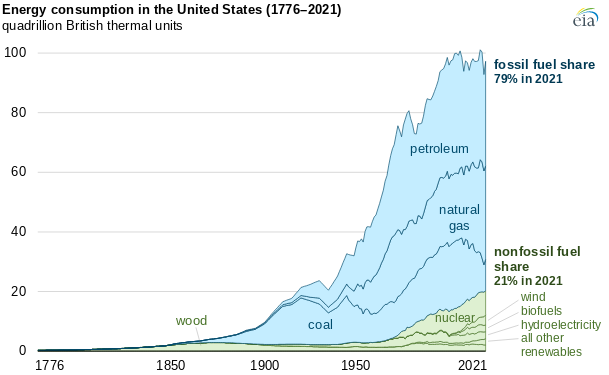
“Oil, discovered in 1859, did not surpass coal as the world’s primary energy source until the 1960s, yet today the world uses almost three times as much coal as it did in the ’60s.“
 Bud's Offshore Energy (BOE)
